


EN
Will TCL License Renewal Change Adeia (ADEA) Narrative
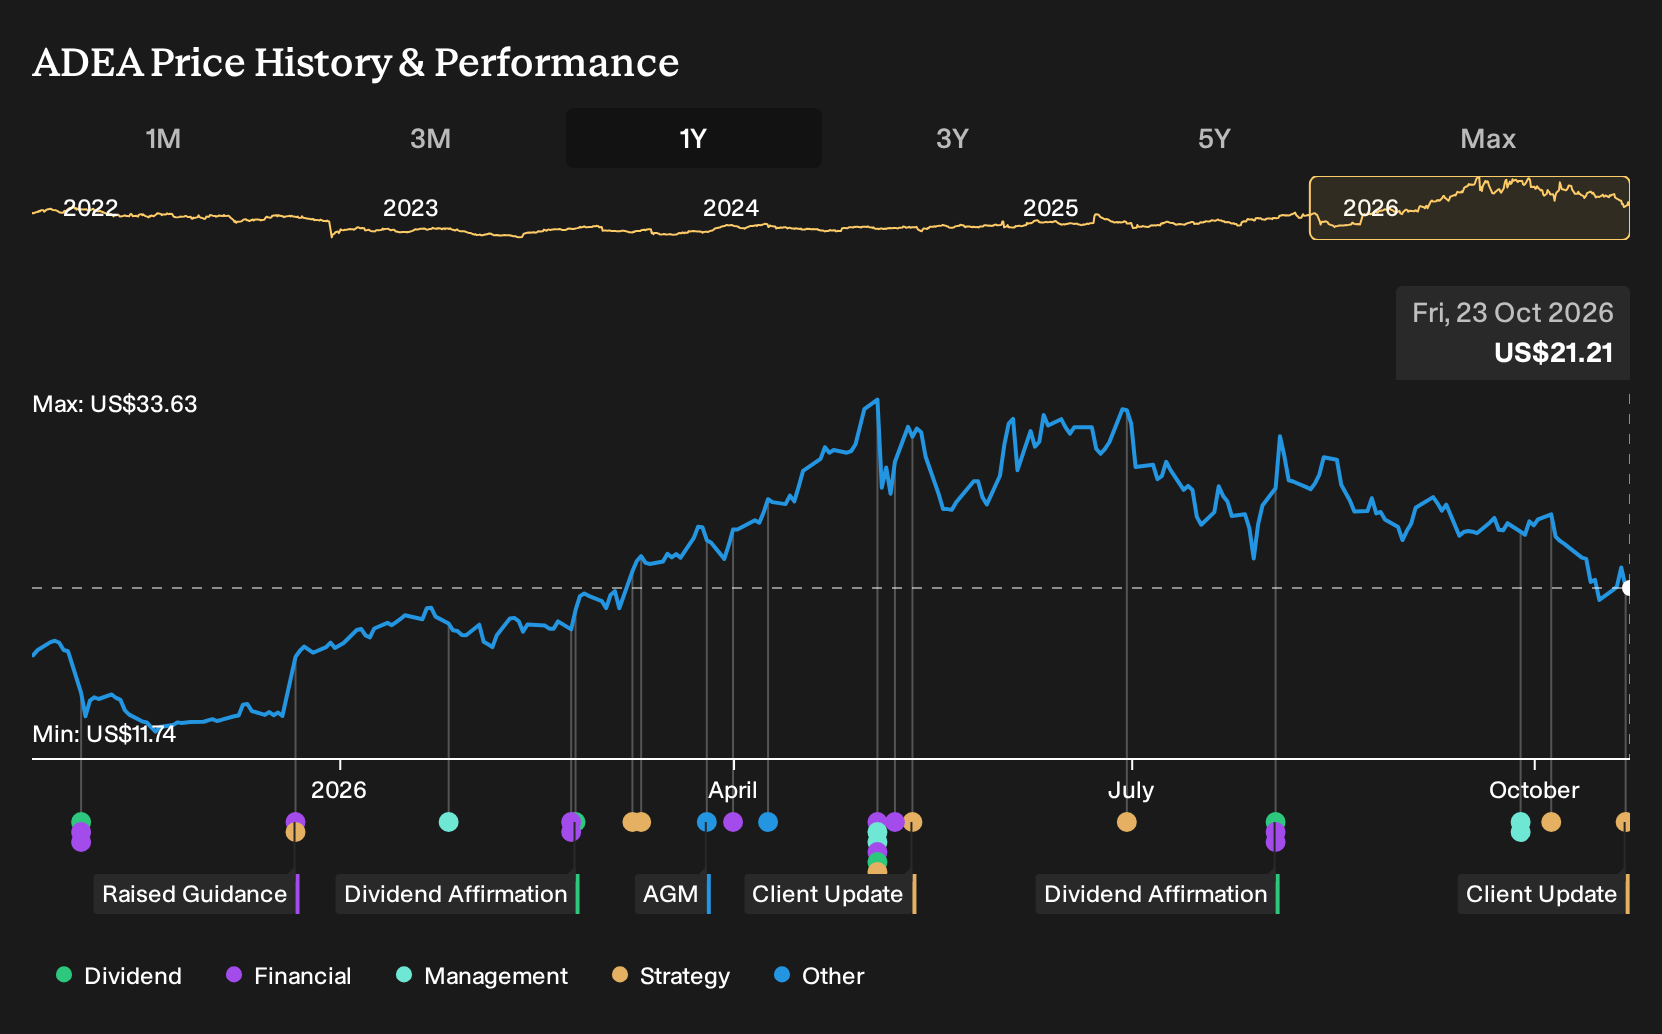
- On 22 October 2026, Adeia Inc. reported that TCL Electronics Holdings renewed a multi-year license for Adeia's media intellectual property portfolio.
- The renewal with TCL underscores Adeia's ability to secure repeat licensing arrangements, which can support recurring IP revenue and validate demand for its media technology.
- This development highlights how Adeia's investment narrative can be influenced by TCL's multi-year IP license renewal and the visibility of recurring media royalties.
Scan beyond Adeia and see how other IP rich media and tech players are positioned by moving through our hand picked 21 high quality undiscovered gems.
Adeia Investment Narrative Recap
Adeia stock appeals to investors who buy into a simple idea. The business needs to keep turning a large patent pool into steady license renewals across Pay TV, streaming, consumer devices and semiconductors. TCL’s multi year renewal supports that narrative by adding evidence of stickiness in the media portfolio, although on its own it is not a transformational catalyst.
The more immediate swing factor still sits in Adeia’s ability to land and time large agreements while containing rising legal costs. Customer concentration, disputes with major operators and higher litigation spend remain key operational risks. The TCL renewal slightly improves visibility on media royalties but does not change those bigger moving pieces.
Against this backdrop, the TCL announcement lines up with past multi year media deals such as the Google renewal referenced in prior commentary. Together, they illustrate how Adeia’s media franchise can lean on recurring royalties from large distribution and device partners, which matters when analysts expect relatively flat top line performance over the next few years.
That context is important as you weigh catalysts and pressure points. Management is pursuing a larger semiconductor royalty opportunity, a higher OTT mix and ongoing patent monetization while dealing with higher legal expenses and a meaningful debt load. TCL’s agreement fits the pattern of high renewal rates across the 14,250 patent portfolio, but execution on new licenses and litigation outcomes still drive the bigger operational story.
Adeia's current earnings sit at $122.7 million, with analysts expecting $106.8 million of earnings on $465.5 million of revenue by 2029. That outlook reflects flat revenue assumptions and an earnings decrease of $15.9 million from today.
Uncover why Adeia's fair value indicates a 103% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Adeia’s potential to grow recurring royalties faster than the baseline view, using renewals like TCL’s as a springboard. Before this news, the bullish group was already penciling in about US$477.0 million of revenue and US$111.5 million of earnings for 2029. That more upbeat story may shift again once this latest contract gets fully factored in, so treat it as one of several viewpoints to compare as you build your own thesis.
Explore 4 other Adeia fair value estimates, including one that suggests as much as 136% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Adeia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Adeia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Adeia?
If Adeia has sharpened your thinking about royalties, balance sheets and future cash flows, it can be useful to line that up against other opportunities using the Simply Wall St Screener.
- For investors hunting for quality at a reasonable entry price, review companies flagged in the 29 high quality undervalued stocks.
- If capital preservation matters just as much as return potential, consider stocks highlighted in the 30 resilient stocks with low risk scores.
- When financial resilience is your first filter, start with businesses surfaced in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com