


EN
Is Wayfair (W) Undervalued After Its UK Fine Or Is The Recovery Priced In?
Wayfair (W) is in focus after the UK Competition and Markets Authority fined the retailer £4.8 million for misleading flash sale promotions. The penalty has put its discounting practices and broader customer trust squarely on investors' radar.
The fine comes after a strong run in Wayfair’s share price, with an 18.99% 90-day share price return and a 30.12% 1-year total shareholder return. However, the 5-year total shareholder return is down 55.45%, which points to improving but still fragile momentum.
Spot opportunities beyond Wayfair by reviewing a curated 21 high quality undiscovered gems that may offer strong fundamentals without being front-page news.Bulls point to Wayfair’s recent share price strength and improving income trends. Bears highlight the fresh UK fine and ongoing losses. As you weigh the next move, which side does the current valuation appear to favor?
Most Popular Narrative: 9% Undervalued
Wayfair last closed at $112.49, while the most followed narrative anchors fair value at $123.34. This frames the recent share price strength against a still discounted valuation in that model.
Wayfair's proprietary logistics network, CastleGate, is expected to provide a meaningful growth unlock by improving efficiency and customer experience, which can positively impact revenue growth through higher conversion rates and potentially improved net margins.
The opening of physical retail locations, such as the Wayfair store outside Chicago, has shown a halo effect on sales growth in nearby areas, which could lead to expanded market reach and increased revenues as additional stores open.
See why 15 investors see Wayfair as 9% undervalued.
Result: Fair Value of $123.34 (UNDERVALUED)
Still, the narrative can crack if housing related demand stays muted for longer, or if heavy advertising and tech spending fail to translate into stronger profitability.
Find out about the key risks to this Wayfair narrative.
Another View: Wayfair Looks Expensive On Sales
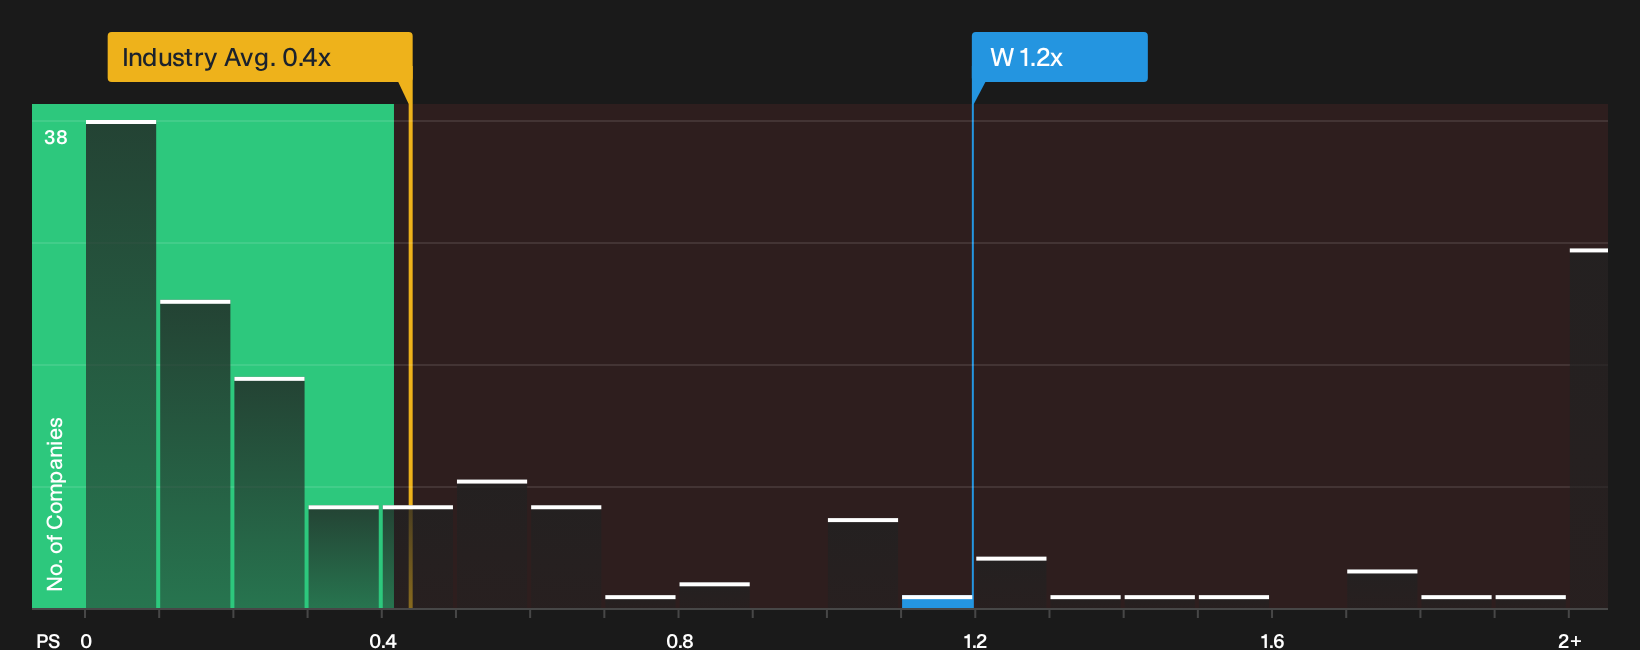
While the most-followed narrative sees Wayfair as 9% undervalued, the P/S lens sends a different signal. The stock trades at 1.2x sales, richer than both the US Specialty Retail industry at 0.4x and its own fair ratio of 0.8x. This points to higher downside risk if sentiment cools.
That gap raises a simple question for investors: Is the current price rewarding Wayfair for progress that still needs to show up in consistent profits, or is it a premium you are comfortable paying for a recovery story that is still in motion?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Wayfair is split. This is exactly why it helps to move quickly, review the numbers yourself, and pressure test both sides using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Wayfair?
Do not stop with a single stock. Broader context helps you judge risk and reward, and a focused screener can surface opportunities you might otherwise miss.
- Target resilient cash generators by reviewing a 29 high quality undervalued stocks that combine quality fundamentals with appealing prices.
- Prioritise capital preservation by scanning a 30 resilient stocks with low risk scores built around businesses with steadier profiles.
- Get ahead of the crowd by working through a list of solid balance sheet and fundamentals (24 results) that highlights companies with robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com