


EN
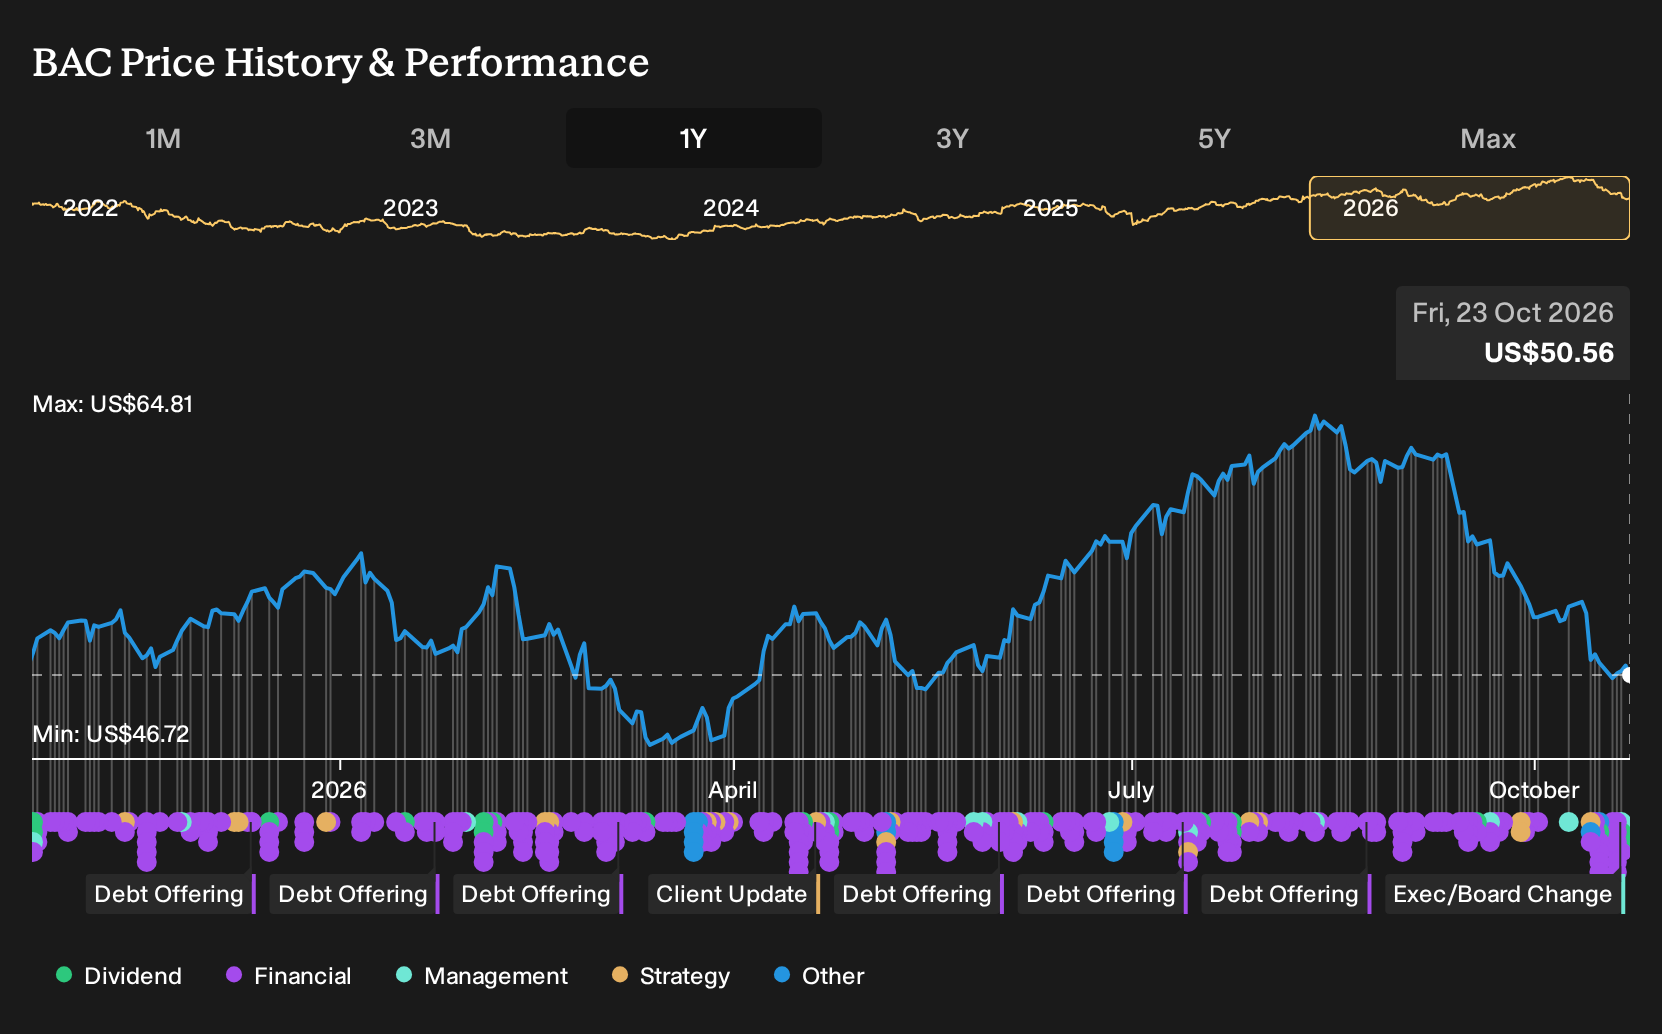
How Investors Are Reacting To Bank of America (BAC) $1.21b Compliance Penalties
- Bank of America was hit with more than US$1.21b in penalties for past anti money laundering and sanctions compliance failures, after regulators detailed long running gaps in monitoring, reporting, and customer due diligence.
- The enforcement orders require intensive remediation and independent reviews. This points to higher compliance spend and a greater operational focus on fixing Bank of America’s control framework.
- We will now look at how this regulatory hit to Bank of America’s compliance track record could reshape the existing investment narrative.
Scan how Bank of America’s regulatory hit compares with large peers by reviewing our hand picked list of 30 resilient stocks with low risk scores before you decide where compliance strength really sits in your portfolio.
Bank of America Investment Narrative Recap
To stay invested in Bank of America, you need to be comfortable with a story built on a US$2t transactional deposit base, ongoing digital and AI spend, and a push to grow fee and wealth revenues while holding quarterly expenses near US$18.6b. The recent US$1.21b compliance penalties and related lawsuit concentrate the near term narrative around execution on remediation and the risk of further regulatory costs.
The key short term swing factor is whether management can contain noninterest expense and protect earnings while upgrading controls. The biggest risk is that regulatory and legal issues persist, which could weigh on operating leverage just as guided investment banking fees soften and sales and trading revenue is expected to be roughly flat year on year.
The Board’s appointment of Jim Fitterling and Bill Thomas looks most relevant here, given the enforcement actions and the scale of Bank of America’s compliance and transformation agenda. Both have experience overseeing large, complex organizations with capital intensive operations, global supply chains, technology programs and extensive regulatory touchpoints, which directly intersects with what the bank is being asked to fix.
For catalysts, these additions broaden the oversight bench at a time when Bank of America is rolling out more than 140 AI applications within a US$14b technology budget and issuing multiple senior and preferred securities. Investors can watch how the refreshed board engages with spending discipline, risk controls and capital allocation, since those decisions will influence how much of the digital and international expansion thesis actually shows up in earnings.
Bank of America's narrative projects US$138.0b revenue and US$37.4b earnings by 2029. This assumes 6.3% yearly revenue growth and about a US$6.6b earnings increase from US$30.8b today.
Uncover why Bank of America's fair value indicates a 25% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Seven fair value estimates from the Simply Wall St Community cluster between about US$63 and US$85 per share, so some retail investors see Bank of America as materially mispriced in both directions. Layer in the recent class action, large AML penalties, fresh board appointments and ongoing bond issuance, and you get very different conclusions about future resilience. Use those contrasts to test your own view against several alternative perspectives before taking the compliance story at face value.
Explore 6 other Bank of America fair value estimates, including one that suggests there may be as much as 68% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of America research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Bank of America. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of America's overall financial health at a glance.
Looking for more investment ideas beyond Bank of America?
Once you have a view on Bank of America, it often helps to widen the lens and line it up against other opportunities with different risk, income and balance sheet profiles. The Simply Wall St Screener can be a quick way to build that wider watchlist without getting lost in noise.
- If you want potential mispricing plus quality, start with a focused set of businesses that score well on fundamentals and valuation by reviewing 29 high quality undervalued stocks.
- For income oriented investors, you can scan companies that combine higher yields with an emphasis on stability by checking out 5 dividend fortresses.
- To keep risk in check across your holdings, consider adding candidates from a curated 30 resilient stocks with low risk scores to balance out more volatile positions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com