


EN
3 European Stocks Estimated To Be Up To 48.8% Below Intrinsic Value
European markets have recently faced challenges, with the pan-European STOXX Europe 600 Index declining amid heightened inflationary pressures and geopolitical tensions. Despite these hurdles, opportunities may exist for investors seeking undervalued stocks that are trading below their intrinsic value. Identifying such stocks involves assessing fundamentals like earnings potential and market position, which can offer a cushion against broader market volatility.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Sentia (OB:SNTIA) | NOK80.00 | NOK159.56 | 49.9% |
| Peab (OM:PEAB B) | SEK94.00 | SEK180.11 | 47.8% |
| Konecranes (HLSE:KCR) | €26.44 | €51.61 | 48.8% |
| Huuuge (WSE:HUG) | PLN24.45 | PLN46.03 | 46.9% |
| Grupa Pracuj (WSE:GPP) | PLN55.10 | PLN108.18 | 49.1% |
| DWS Group GmbH KGaA (XTRA:DWS) | €63.60 | €126.79 | 49.8% |
| DEME Group (ENXTBR:DEME) | €164.40 | €310.08 | 47% |
| Colt CZ Group (SEP:COLT) | CZK829.00 | CZK1561.55 | 46.9% |
| Boliden (OM:BOL) | SEK483.20 | SEK944.05 | 48.8% |
| Apator (WSE:APT) | PLN26.10 | PLN50.68 | 48.5% |
Let's take a closer look at a couple of our picks from the screened companies.
Vestas Wind Systems (CPSE:VWS)
Overview: Vestas Wind Systems A/S is involved in the design, manufacture, installation, and servicing of wind turbines across the United States, Denmark, and internationally with a market cap of DKK181.56 billion.
Operations: The company's revenue segments consist of €3.63 billion from Service and €16.67 billion from Power Solutions.
Estimated Discount To Fair Value: 31.9%
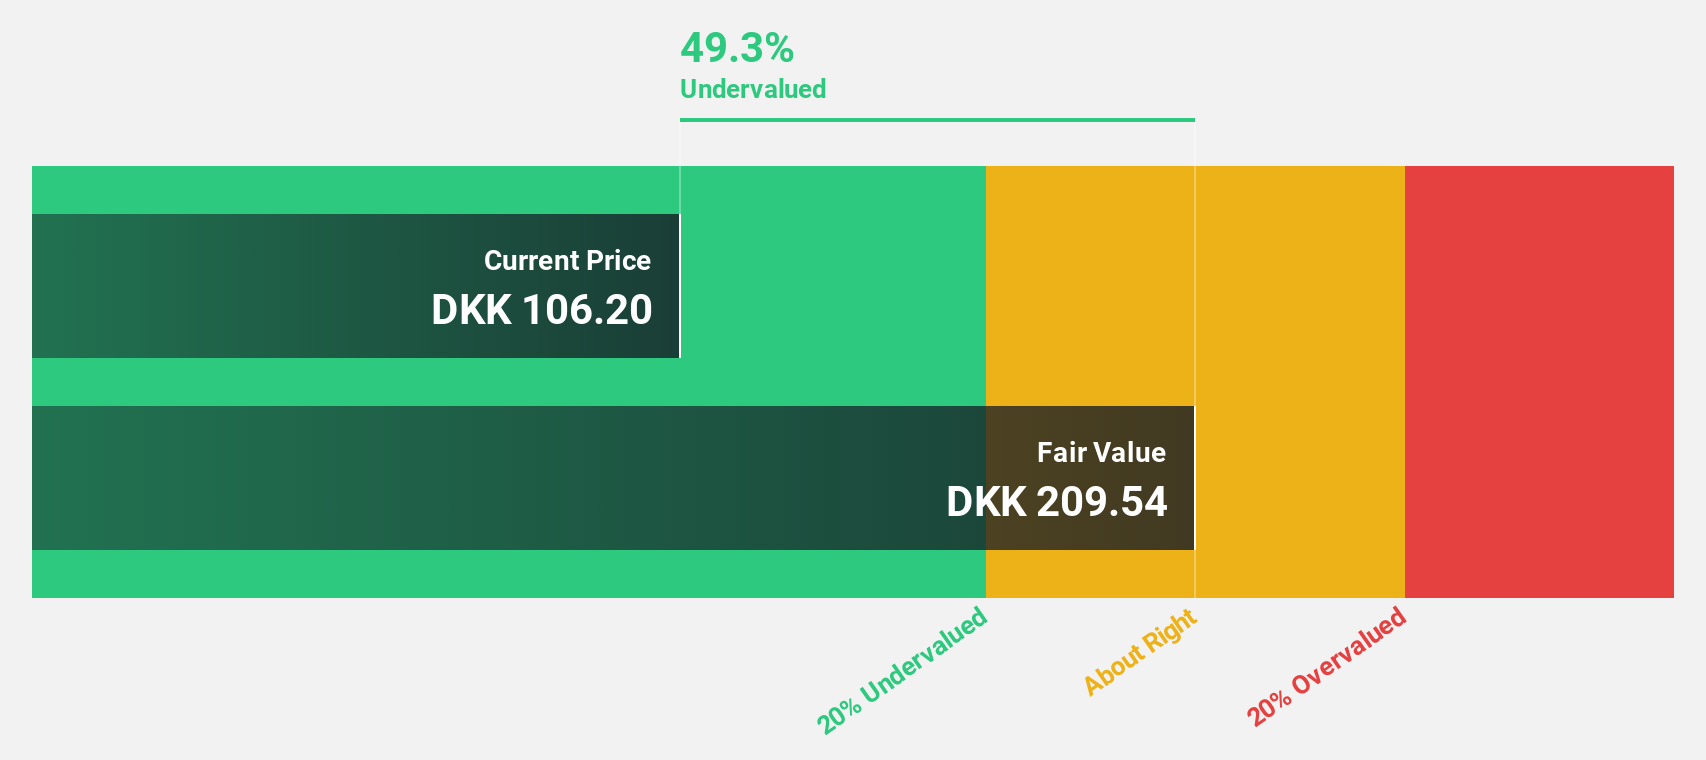
Vestas Wind Systems appears undervalued, trading at DKK185.6 below its estimated cash flow value of DKK272.57, suggesting a significant discount. Recent earnings guidance revisions indicate improved profitability with an EBIT margin now expected between 7% and 9%. Despite high share price volatility, Vestas's earnings grew 44.8% last year and are forecasted to grow at 16.8% annually, outpacing the Danish market's growth rate of 7.7%.
- Our growth report here indicates Vestas Wind Systems may be poised for an improving outlook.
- Navigate through the intricacies of Vestas Wind Systems with our comprehensive financial health report here.
Konecranes (HLSE:KCR)
Overview: Konecranes Plc is a company that manufactures, sells, and services material handling products across Europe, the Middle East, Africa, the Americas, and the Asia-Pacific with a market capitalization of €6.28 billion.
Operations: The company's revenue segments consist of Port Solutions (€1.52 billion), Industrial Service (€1.55 billion), and Industrial Equipment (€1.29 billion).
Estimated Discount To Fair Value: 48.8%
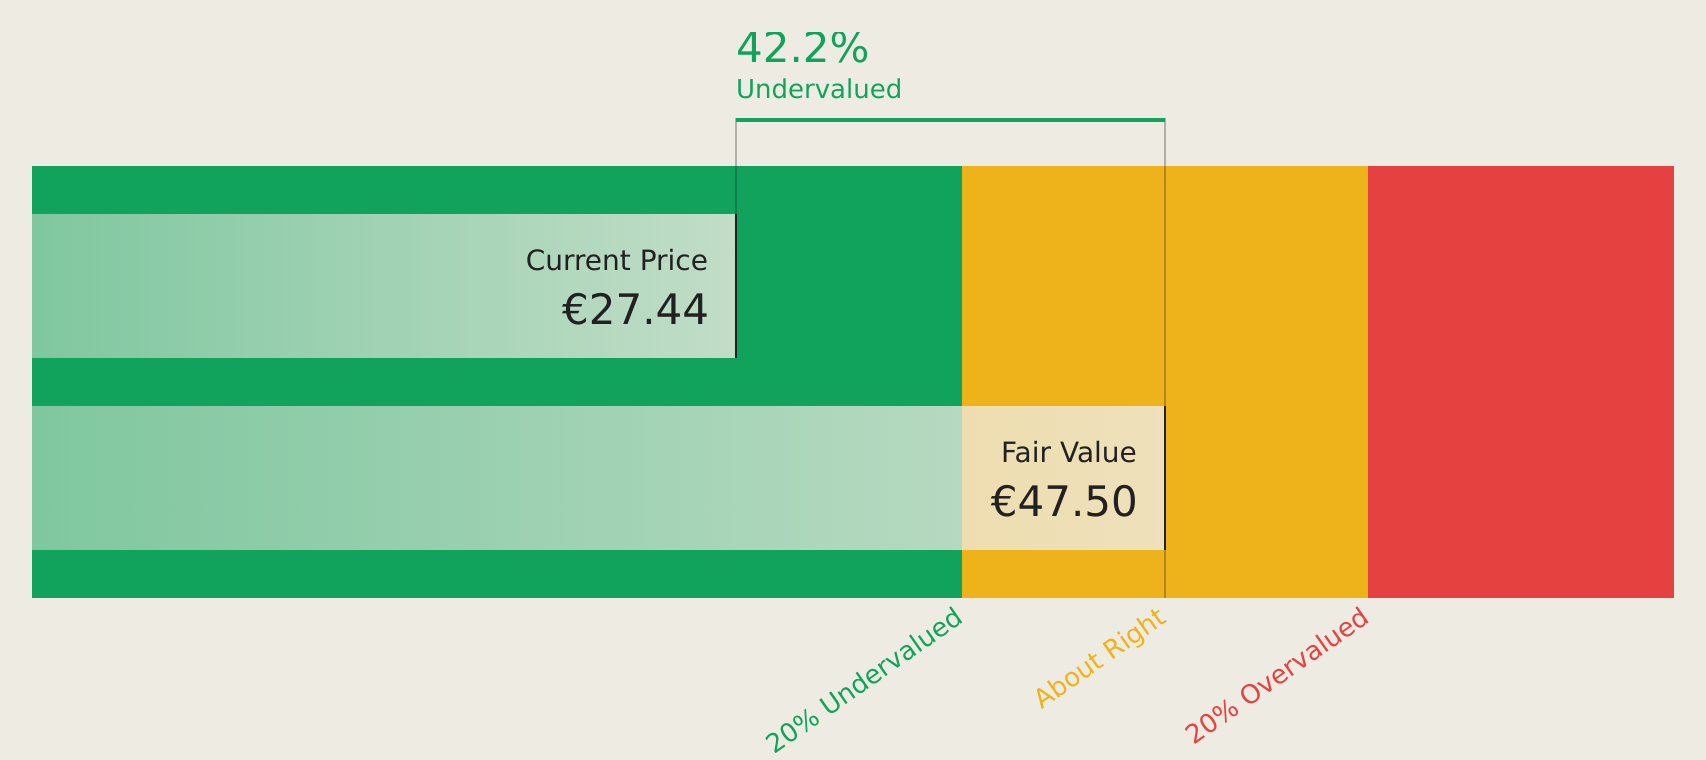
Konecranes is trading at €26.44, significantly below its estimated future cash flow value of €51.61, indicating it may be undervalued based on cash flows. Despite a slower forecasted earnings growth of 11.6% annually compared to the Finnish market's 14.8%, recent third-quarter results showed increased sales and net income year-over-year, with a confirmed stable revenue outlook for 2026. Recent strategic orders enhance its automation and electrification capabilities in port solutions, supporting long-term growth prospects.
- Upon reviewing our latest growth report, Konecranes' projected financial performance appears quite optimistic.
- Dive into the specifics of Konecranes here with our thorough financial health report.
Auto Partner (WSE:APR)
Overview: Auto Partner SA imports and distributes parts for passenger cars, delivery vans, and motorcycles in Poland, with a market cap of PLN3.64 billion.
Operations: The company's revenue is primarily derived from the sale of spare parts and accessories to motor vehicles, totaling PLN4.67 billion.
Estimated Discount To Fair Value: 25.6%
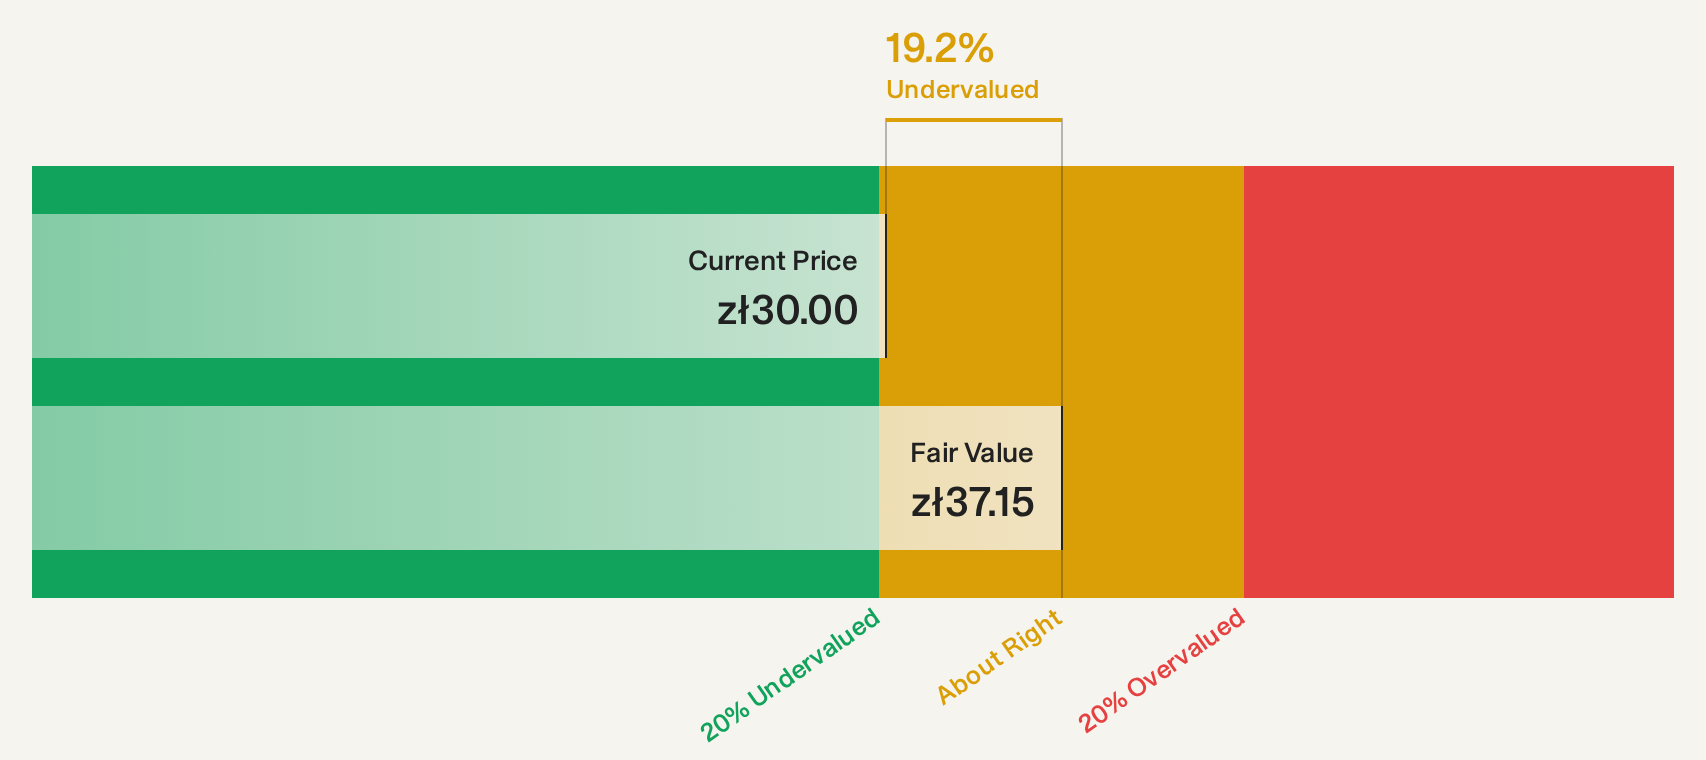
Auto Partner is trading at PLN27.85, significantly below its estimated future cash flow value of PLN37.41, highlighting potential undervaluation based on cash flows. Recent earnings results for Q2 2026 show sales increased to PLN1.29 billion from PLN1.14 billion year-over-year, with net income rising to PLN94.14 million from PLN57.94 million. Revenue growth is forecasted at 10.1% annually, outpacing the Polish market's 5.4%, while earnings are expected to grow by 16.7% per year.
- Our expertly prepared growth report on Auto Partner implies its future financial outlook may be stronger than recent results.
- Take a closer look at Auto Partner's balance sheet health here in our report.
Summing It All Up
- Explore the 63 names from our Undervalued European Stocks Based On Cash Flows screener here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Enhance your investing ability with the Simply Wall St app and enjoy free access to essential market intelligence spanning every continent.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com