


EN
Exploring 3 European Hidden Gems with Strong Potential
Amidst a backdrop of rising oil prices and geopolitical tensions, European markets have experienced a dip, with the STOXX Europe 600 Index down by 1.39% recently. This environment of heightened inflationary pressures and political unrest across key regions has created unique opportunities for discerning investors to explore lesser-known stocks that may offer strong potential. In this context, identifying companies with robust fundamentals and resilience in challenging conditions becomes crucial for those looking to uncover hidden gems in the European market landscape.
Top 10 Undiscovered Gems With Strong Fundamentals In Europe
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apator | 13.65% | 6.21% | 20.01% | ★★★★★★ |
| B&C Speakers | 39.08% | 14.82% | 13.88% | ★★★★★★ |
| Angler Gaming | NA | -4.50% | -4.71% | ★★★★★★ |
| innoscripta | 30.37% | 42.47% | 38.04% | ★★★★★☆ |
| Byggmax Group | 3.28% | -5.41% | -33.83% | ★★★★★☆ |
| Sotkamo Silver | 33.93% | 8.37% | 33.34% | ★★★★★☆ |
| Edel SE KGaA | 142.35% | 1.36% | 12.24% | ★★★★☆☆ |
| SP Group | 83.41% | 5.40% | 9.36% | ★★★★☆☆ |
| Lea Bank | 14.47% | -7.37% | -27.19% | ★★★★☆☆ |
| ITAB Group | 71.44% | 16.24% | 17.06% | ★★★★☆☆ |
We'll examine a selection from our screener results.
Atea (OB:ATEA)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Atea ASA offers IT infrastructure and related solutions to businesses and public sector organizations across the Nordic countries and Baltic regions, with a market capitalization of NOK 18.23 billion.
Operations: Revenue streams for Atea ASA primarily come from its operations in Sweden (NOK 16.16 billion), Norway (NOK 10.42 billion), and Denmark (NOK 9.05 billion). The company also generates revenue from Finland and the Baltic regions, contributing NOK 3.68 billion and NOK 2.25 billion, respectively. Group Shared Services adds NOK 14.54 billion to the overall revenue mix, while eliminations account for a reduction of NOK -14.91 billion in total revenues.
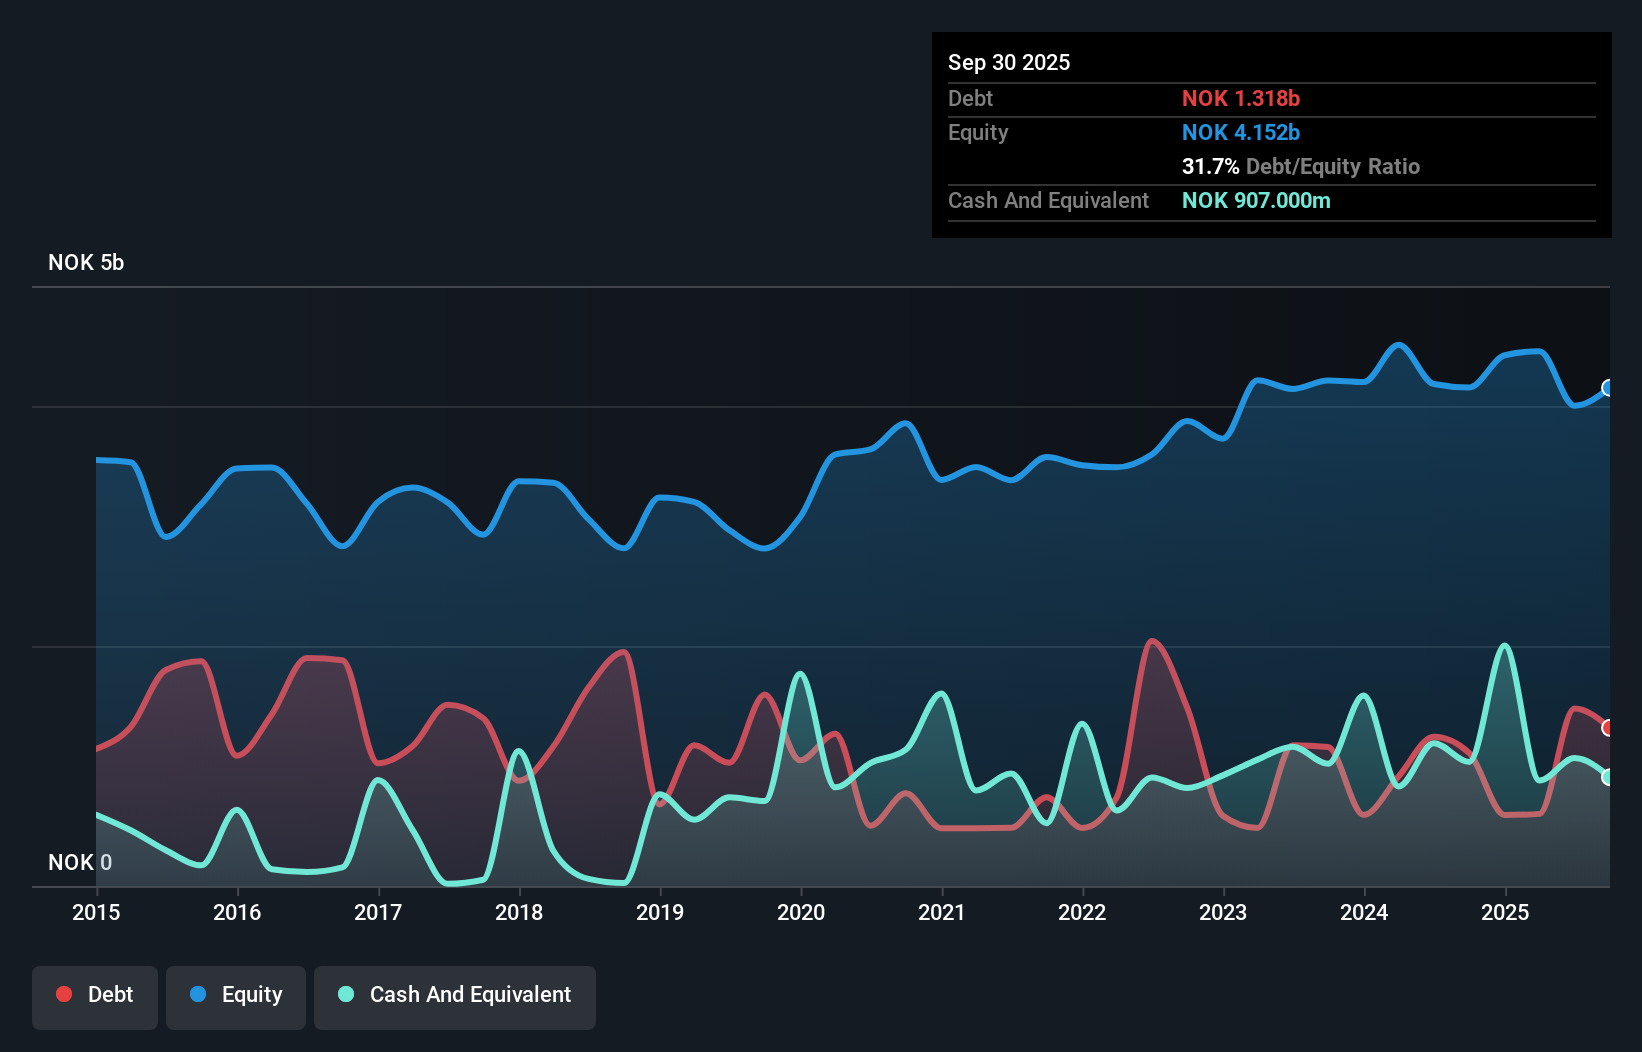
Atea, a promising player in the Nordic IT space, has shown robust earnings growth of 54% over the past year, far outpacing the IT industry's average of 8.8%. The company's net income for Q3 2026 was NOK 279 million, an increase from NOK 226 million a year ago. Trading at nearly 56% below estimated fair value, Atea's valuation appears attractive. With a satisfactory net debt to equity ratio of 31.5%, its financial health seems solid. As public sector contracts and AI demand rise, Atea is well-positioned to capitalize on these trends despite potential risks in services revenue and inventory management.
Multiconsult (OB:MULTI)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Multiconsult ASA, along with its subsidiaries, offers engineering design, consultancy, and architecture services across Norway and several international markets including Sweden, Denmark, and Poland; it has a market capitalization of NOK 3.74 billion.
Operations: Multiconsult generates revenue primarily from its operations in Norway, contributing NOK 4.70 billion, and from architecture services amounting to NOK 766.02 million. The international segment adds NOK 426.16 million to the total revenue stream.
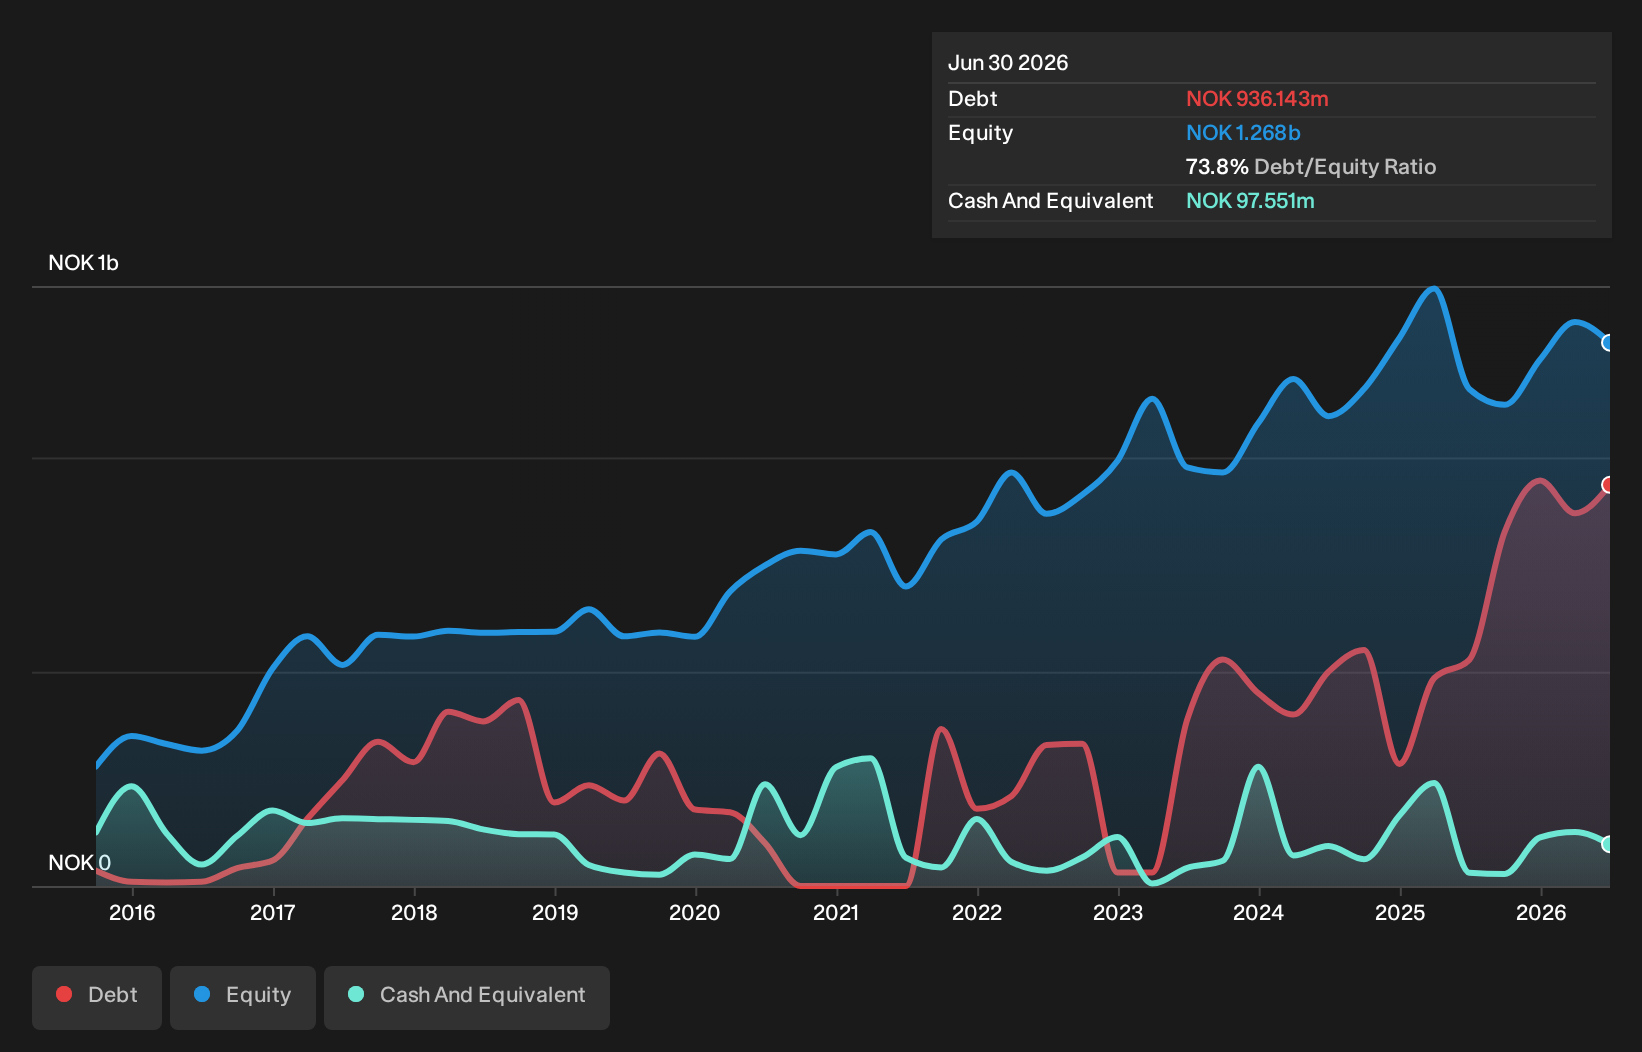
With a debt to equity ratio climbing from 0% to 73.8% over five years, Multiconsult's financial structure shows a significant shift, yet its interest payments are well covered by EBIT at 10.7 times. Despite negative earnings growth of -19.5%, the company is trading at an attractive value, 42% below its estimated fair value and boasts high-quality past earnings. The recent merger with Rejlers AB positions it as a pan-Nordic consultancy powerhouse with nearly 8,000 employees across multiple regions, potentially enhancing future prospects despite current challenges in matching industry growth averages of around 24%.
- Take a closer look at Multiconsult's potential here in our health report.
Evaluate Multiconsult's historical performance by accessing our past performance report.
MBB (XTRA:MBB)
Simply Wall St Value Rating: ★★★★★★
Overview: MBB SE, with a market cap of approximately €1.08 billion, focuses on acquiring and managing medium-sized companies in Germany and internationally through its subsidiaries.
Operations: MBB SE generates revenue primarily from its subsidiaries, with Friedrich Vorwerk contributing the largest share at approximately €738.55 million, followed by Aumann at €166.33 million. The company reported a total revenue of around €1.16 billion after accounting for segment reconciliation adjustments of -€0.70 million.
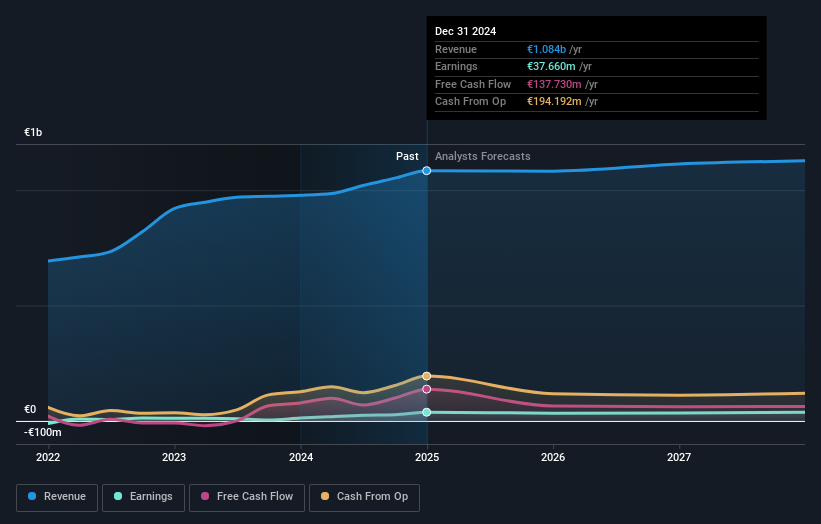
MBB is making waves with a notable earnings growth of 53.3% over the past year, outpacing the Industrials sector's 16.9%. The company’s debt to equity ratio has impressively reduced from 8.2% to 3.6% in five years, highlighting prudent financial management. Trading at about 60% below its estimated fair value, MBB seems undervalued despite its strong performance and strategic buybacks worth €25 million this year alone. With a forecasted annual earnings growth of nearly 31%, MBB appears well-positioned for future gains, supported by robust cash reserves and significant order backlogs in energy infrastructure projects.
Next Steps
- Click this link to deep-dive into the 39 companies within our European Undiscovered Gems With Strong Fundamentals screener.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com