


EN
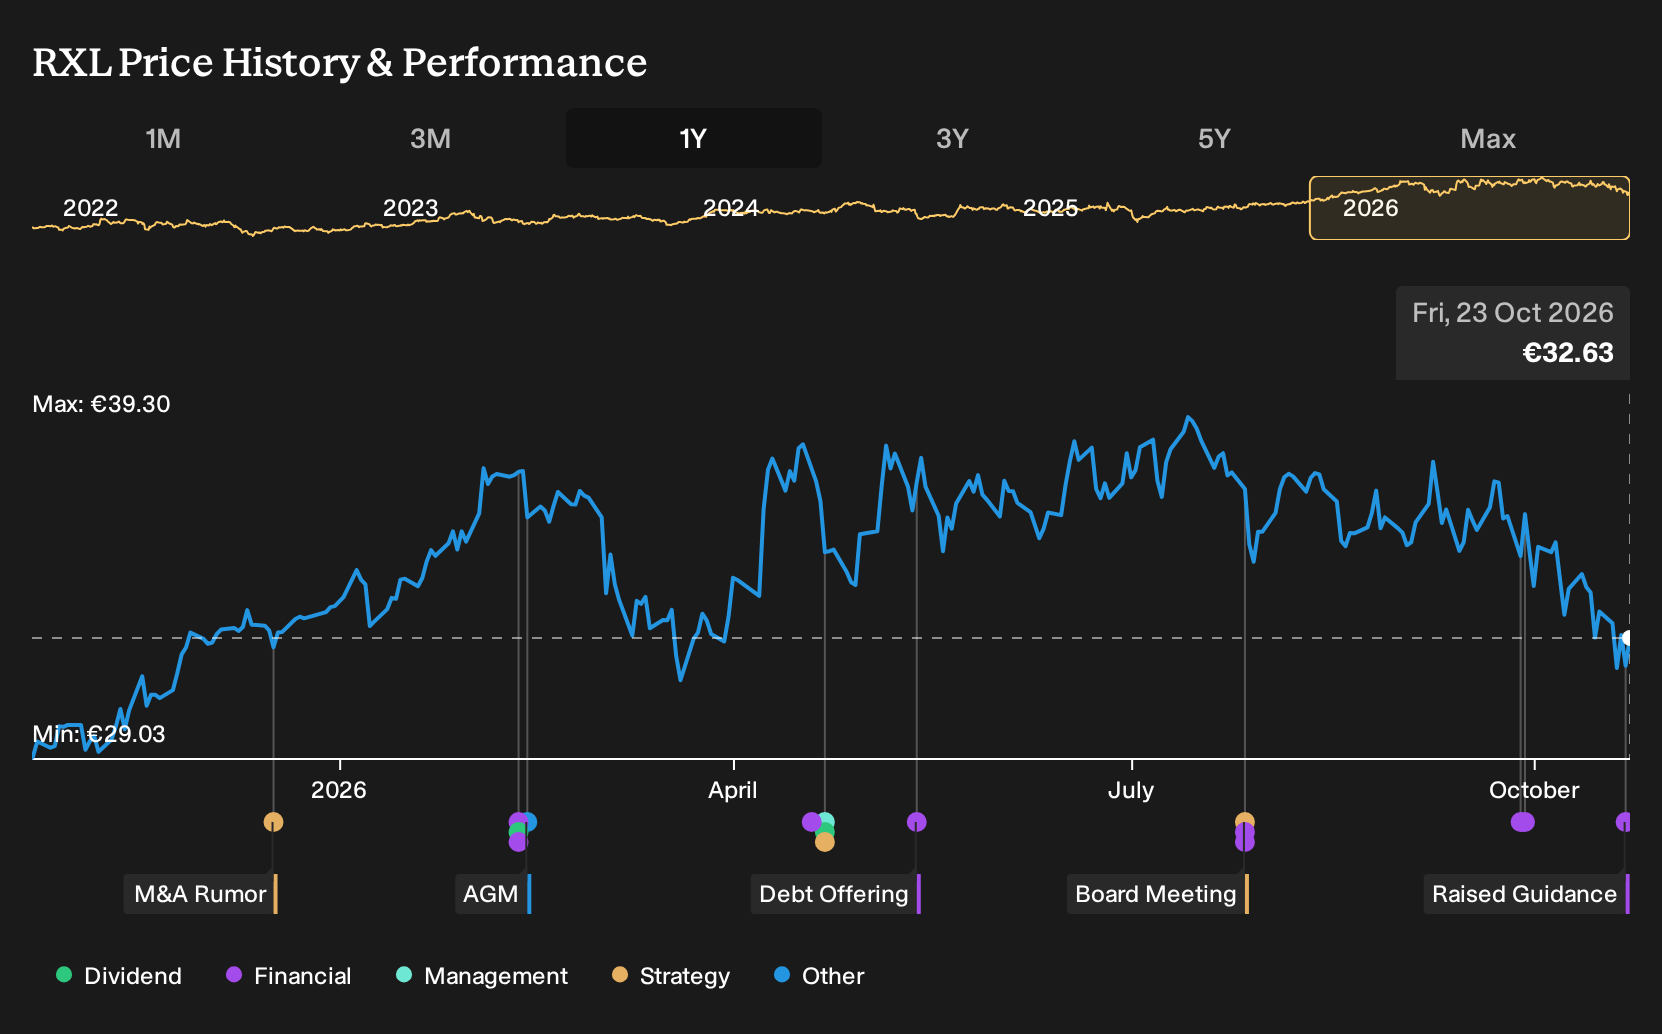
Raised 2026 Outlook Will Impact Rexel (ENXTPA:RXL) Investors
- Rexel raised its 2026 earnings guidance, now projecting around 7% same-day sales growth instead of the around 5% outlook communicated in July. This signals higher expected activity across its electrical distribution network.
- The higher same-day sales target points to stronger anticipated demand across Rexel's customer base, which could reshape how investors think about the durability of its order pipeline and day-to-day trading performance.
- Next, the focus is on how Rexel's higher 7% same-day sales target might reshape the broader investment narrative around its business model.
Compare Rexel's upgraded outlook with a curated group of electrical and infrastructure players by scanning our 42 power grid technology and infrastructure stocks for companies positioned for similar demand-driven momentum.
What Is Rexel's Investment Narrative?
The core belief for owning Rexel is simple. You have to trust that a broad network of low voltage electrical distribution, plus decent digital tools, can turn steady 6.2% forecast annual revenue growth into consistently higher earnings without blowing out capital needs. The raised 2026 same day sales goal to around 7% sits within that story. It points to healthier near term demand across France, North America and other regions where the distributor already has scale.
In the short term, the higher target sharpens the spotlight on execution. Order fulfilment, pricing discipline and working capital management need to match this more ambitious outlook if the business is to keep improving from a 3.4% net margin and €668.8m of profit on €19.6b of revenue. Analysts already see upside, and the stock trades at a 15.1x P/E, which screens as good value versus both fair value estimates and peers. Debt levels and an unsteady dividend track record still frame the main pressure points if momentum wobbles.
That said, there is a less comfortable angle to this higher growth ambition that starts with how Rexel is funded and...
There's only one way to know the right time to buy, sell or hold Rexel. Head to Simply Wall St's company report for the latest analysis of Rexel's Fair Value.
Exploring Other Perspectives
One alternate view on Rexel leans heavily on project risk. The most cautious analysts worry that data center and infrastructure pipelines could cool, which would test returns from the GCG deal. They were only pencilling in about 5.3% annual revenue growth and earnings of €877.6m by 2029, so their story is far more restrained. These estimates were set before the new 7% same day sales goal, so you might see those forecasts shift. Use this gap in expectations as a reminder that reasonable people can read the same numbers very differently, and that you should explore both optimistic and cautious cases before making a call.
Explore 4 other Rexel fair value estimates, including one that suggests it could be worth just €31.89.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Rexel research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Rexel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rexel's overall financial health at a glance.
Looking For More Investment Ideas Beyond Rexel?
Once you have a view on Rexel, it can help to cross check that thesis against other opportunities that share similar qualities or offer a different mix of risk and reward.
- If capital preservation sits near the top of your priorities, start with a shortlist of resilient businesses by reviewing 221 resilient stocks with low risk scores.
- For readers who want income on top of potential price returns, consider high yielding payers by scanning 230 dividend fortresses.
- Anyone hunting for underfollowed opportunities with solid fundamentals can cast a wider net using 611 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com