


EN
Why Honeywell International (HON) Is Getting Attention Today
Honeywell raises guidance after earnings beat
Honeywell International (HON) lifted full year 2026 earnings and sales guidance after adjusted third quarter results topped analyst expectations, with margin expansion and its shift to a pure play automation business drawing investor attention.
The recent guidance hike and Q3 beat come as the share price has climbed 4.6% over the past week and 4.1% over the past month, while the 90 day share price return is down about 10% and the year-to-date move is weaker. A 1 year total shareholder return of 5.6% and 3 year total shareholder return of 34.6% suggest that longer term holders have still seen positive compounding.
Scan beyond Honeywell International and size up other automation focused industrials with the hand picked 95 robotics and automation stocks that are riding similar AI and IoT tailwinds.
Honeywell International has rerated on guidance upgrades and its pure play automation story, while near term returns remain mixed. Does that backdrop still skew the risk and reward towards fresh buyers or favour patience on the sidelines?
Most Popular Narrative: 30.9% Undervalued
Honeywell International last closed at $221.15, while the most followed narrative pegs fair value closer to $320.19. This frames the recent automation pivot as more than just a short term rerating story.
HON RemainCo is a pure-play industrial automation and energy technology compounder with a confirmed June 29 catalyst, $19B+ in contracted backlog, a sold-out LNG order book, a global SAF technology licensing position, a recurring revenue platform transition underway via Forge, and an embedded position on both sides of the energy transition, all trading at a conglomerate discount that disappears in 53 days.
The floor is a durable, dividend-growing, installed-base compounder with products in virtually every commercial building and industrial facility on earth. The ceiling is the moment the market realizes RemainCo sits at the intersection of every secular theme that has driven the best-performing industrial stocks of the last two years, and nobody has written that headline yet.
See why 67 investors see Honeywell International as 31% undervalued.
Result: Fair Value of $320.19 (UNDERVALUED)
Still, the Honeywell International story can be knocked off course if the planned separation fails to unlock a pure play P/E re rating, or if weaker organic growth trends persist beyond 2026 and undermine confidence in that automation led thesis.
Find out about the key risks to this Honeywell International narrative.
Another View: Honeywell and the DCF Check
While many Honeywell International narratives lean on a fair value of $320.19, our DCF model points a different way. At a current price of $221.15, the stock sits above an estimated future cash flow value of $172, which signals overvaluation on this framework. Which story do you trust more: the cash flows or the narrative multiple?
Look into how the SWS DCF model arrives at its fair value.
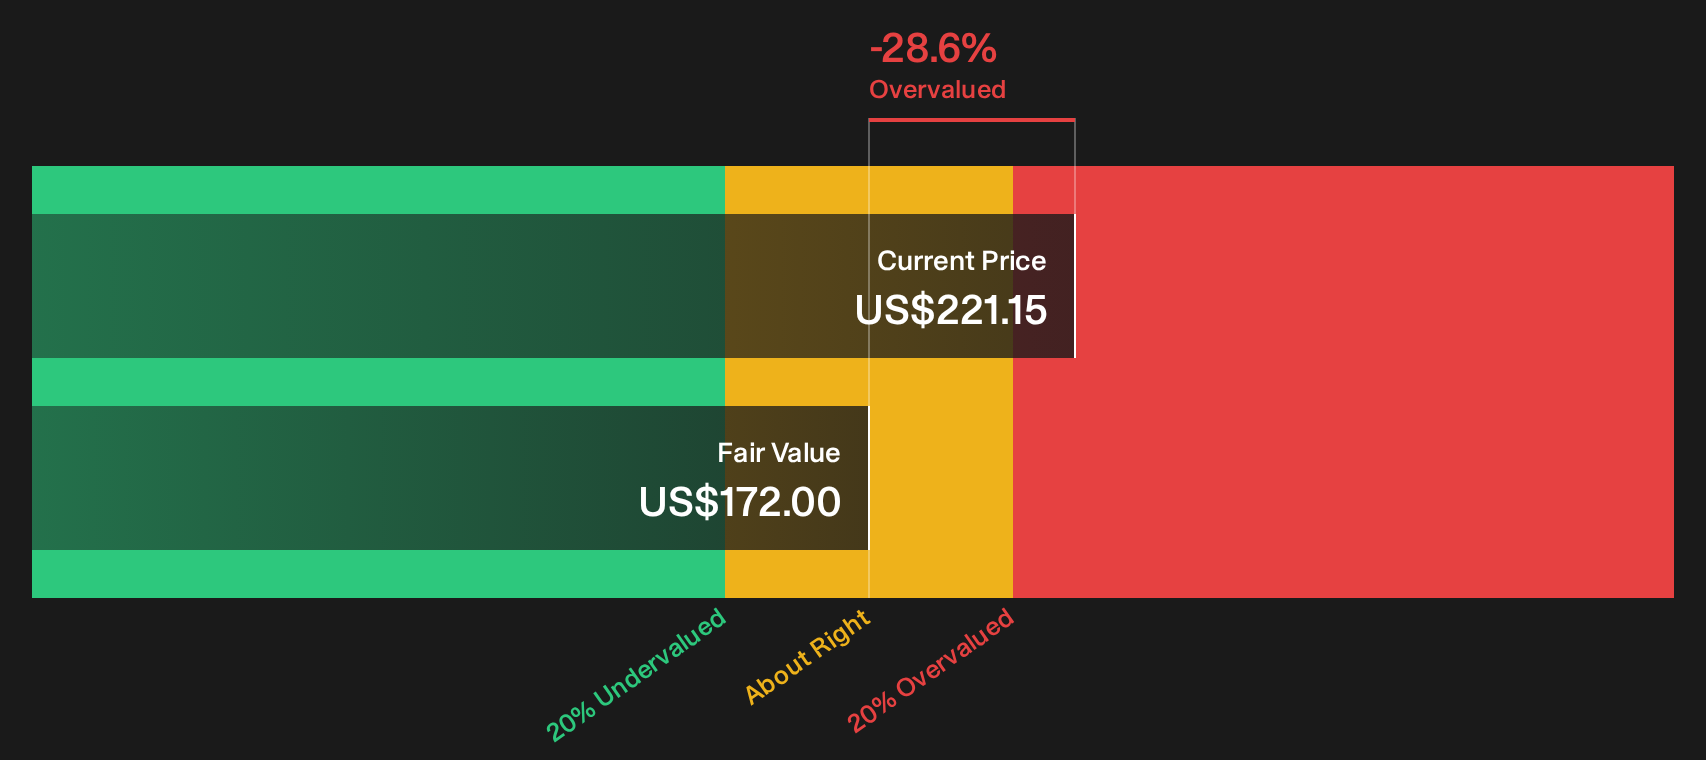
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Honeywell International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Honeywell International feels familiar, consider acting promptly. Review the numbers and form your own stance using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Honeywell?
Do not stop at Honeywell International. Broaden your watchlist with fresh ideas that match your risk comfort and income goals using the Simply Wall St Screener.
- Target potential mispricing by scanning a curated set of quality opportunities through the 29 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that aim to combine higher yields with resilience via the 5 dividend fortresses.
- Dial down portfolio stress by concentrating on sturdier businesses screened through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com