


EN
October 2026's Asian Stocks That May Be Trading Below Estimated Value
As October 2026 unfolds, the Asian markets are navigating a landscape marked by volatility driven by AI investment concerns and rising oil prices. Amid these fluctuations, investors are increasingly focused on identifying stocks that may be trading below their estimated value, presenting potential opportunities in an unpredictable environment. In such conditions, a good stock often exhibits strong fundamentals and resilience to market shifts, making it crucial for investors to assess intrinsic value carefully while considering broader economic trends.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wus Printed Circuit (Kunshan) (SZSE:002463) | CN¥107.06 | CN¥210.84 | 49.2% |
| Thai Credit Bank (SET:CREDIT) | THB22.90 | THB45.74 | 49.9% |
| Smartsens Technology (Shanghai) (SHSE:688213) | CN¥110.16 | CN¥216.15 | 49% |
| P.S.P. Specialties (SET:PSP) | THB7.40 | THB14.65 | 49.5% |
| P&H Tech (KOSDAQ:A239890) | ₩3135.00 | ₩6206.43 | 49.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1483.00 | ¥2915.30 | 49.1% |
| Nissei ASB Machine (TSE:6284) | ¥8030.00 | ¥15788.69 | 49.1% |
| Morinaga Milk Industry (TSE:2264) | ¥1083.00 | ¥2134.38 | 49.3% |
| KB Financial Group (KOSE:A105560) | ₩153000.00 | ₩304946.07 | 49.8% |
| Ichikoh Industries (TSE:7244) | ¥532.00 | ¥1057.60 | 49.7% |
Let's explore several standout options from the results in the screener.
WuXi AppTec (SHSE:603259)
Overview: WuXi AppTec Co., Ltd. is an investment holding company offering research and manufacturing services for small molecule drugs across China, the United States, Europe, and internationally with a market cap of CN¥431.48 billion.
Operations: WuXi AppTec generates revenue through its provision of research and manufacturing services aimed at the discovery, development, and production of small molecule drugs across various regions including China, the United States, Europe, and other international markets.
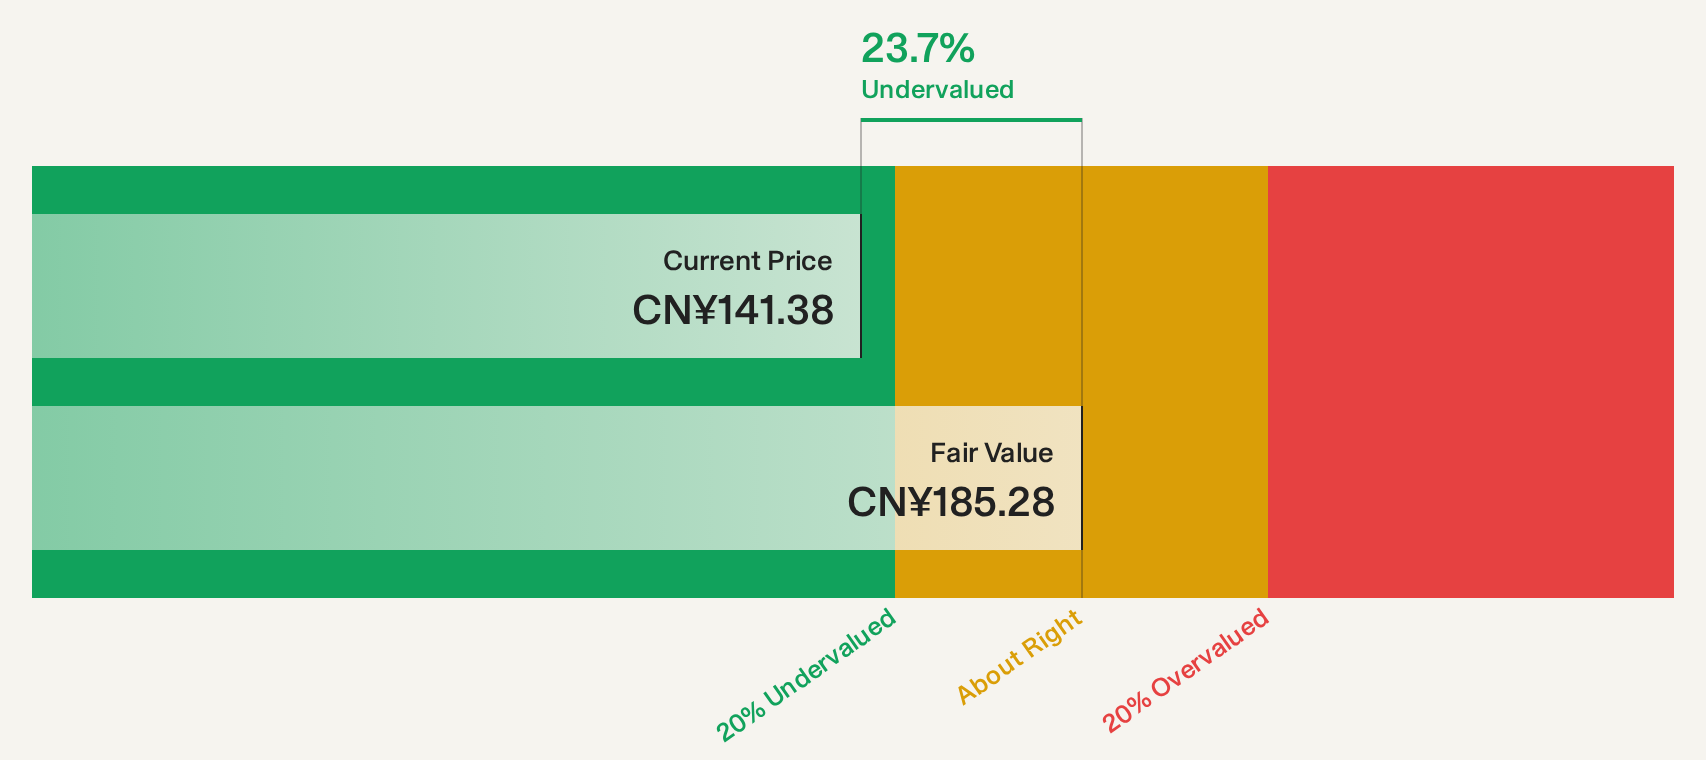
Estimated Discount To Fair Value: 21.2%
WuXi AppTec is trading at CN¥144.72, below its estimated future cash flow value of CN¥183.65, indicating it may be undervalued based on cash flows. Despite a slower forecasted earnings growth of 14.6% per year compared to the Chinese market's 26.6%, its revenue target for 2026 was raised significantly, suggesting robust operational performance. Recent amendments to company bylaws and an upcoming board meeting highlight active corporate governance efforts amidst these financial developments.
- According our earnings growth report, there's an indication that WuXi AppTec might be ready to expand.
- Delve into the full analysis health report here for a deeper understanding of WuXi AppTec.
Inspur Electronic Information Industry (SZSE:000977)
Overview: Inspur Electronic Information Industry Co., Ltd. and its subsidiaries offer cloud computing and big data services both in China and internationally, with a market cap of CN¥85.91 billion.
Operations: The company generates revenue primarily from its Electronics Industry segment, amounting to CN¥168.97 billion.
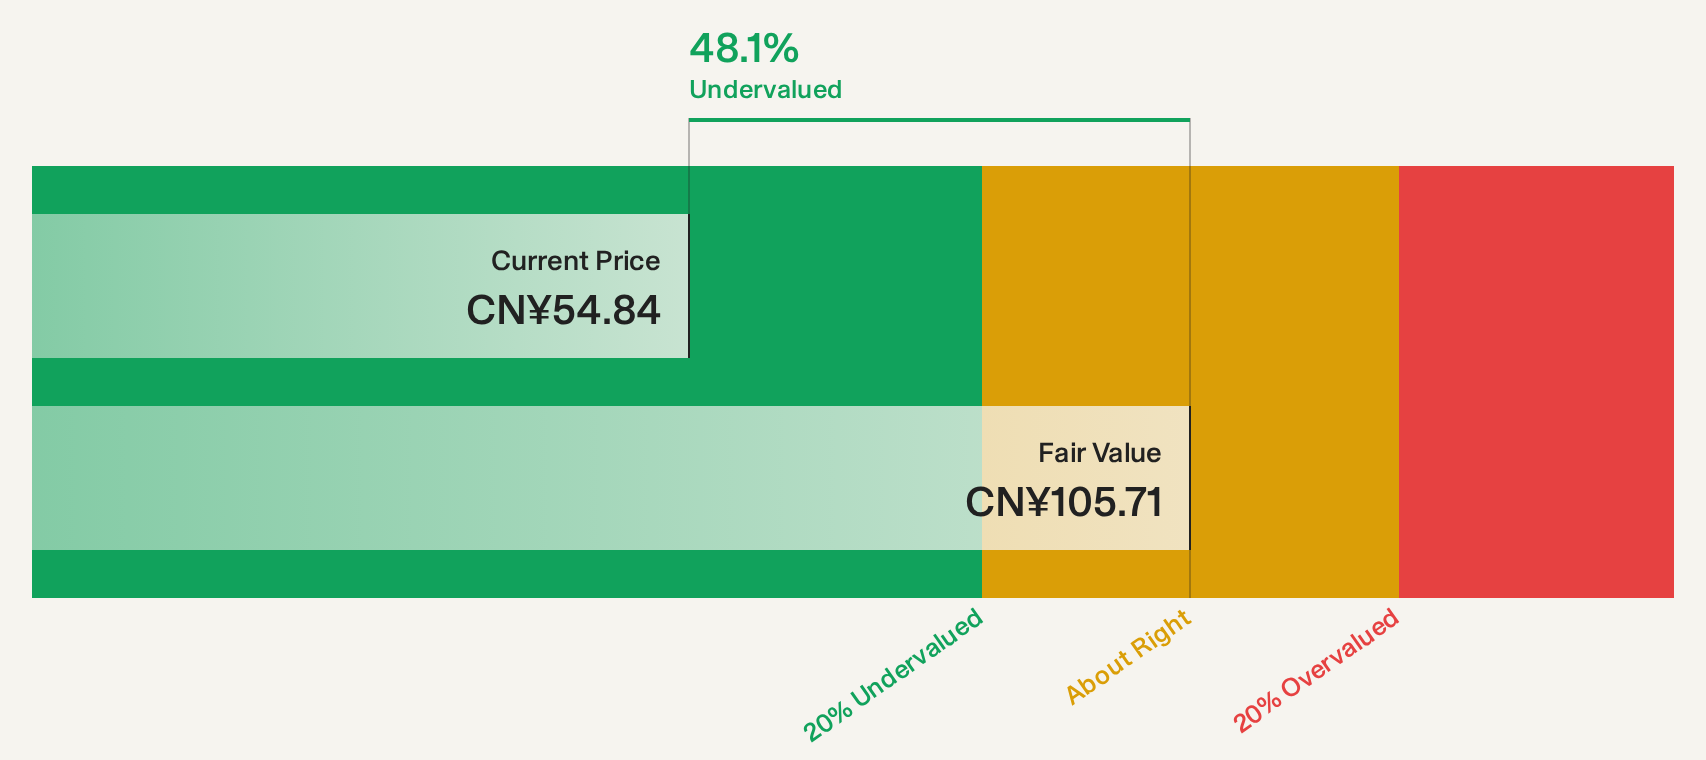
Estimated Discount To Fair Value: 45.2%
Inspur Electronic Information Industry, trading at CN¥58.5, is significantly undervalued based on cash flows with an estimated future value of CN¥106.74. Despite forecasted earnings growth of 19.8% per year being slower than the market's 26.6%, its revenue is expected to grow faster than the market at 25% annually. Recent financial results showed a substantial increase in net income and sales, while corporate governance activities include amendments to bylaws and a private placement initiative raising up to CN¥9 billion.
- Our comprehensive growth report raises the possibility that Inspur Electronic Information Industry is poised for substantial financial growth.
- Click here to discover the nuances of Inspur Electronic Information Industry with our detailed financial health report.
Pharmaron Beijing (SZSE:300759)
Overview: Pharmaron Beijing Co., Ltd. operates as a pharmaceutical research and development service platform across North America, Europe, Mainland China, Asia, and internationally with a market cap of CN¥64.39 billion.
Operations: Pharmaron Beijing Co., Ltd.'s revenue segments encompass pharmaceutical research and development services across various global regions, including North America, Europe, Mainland China, and Asia.
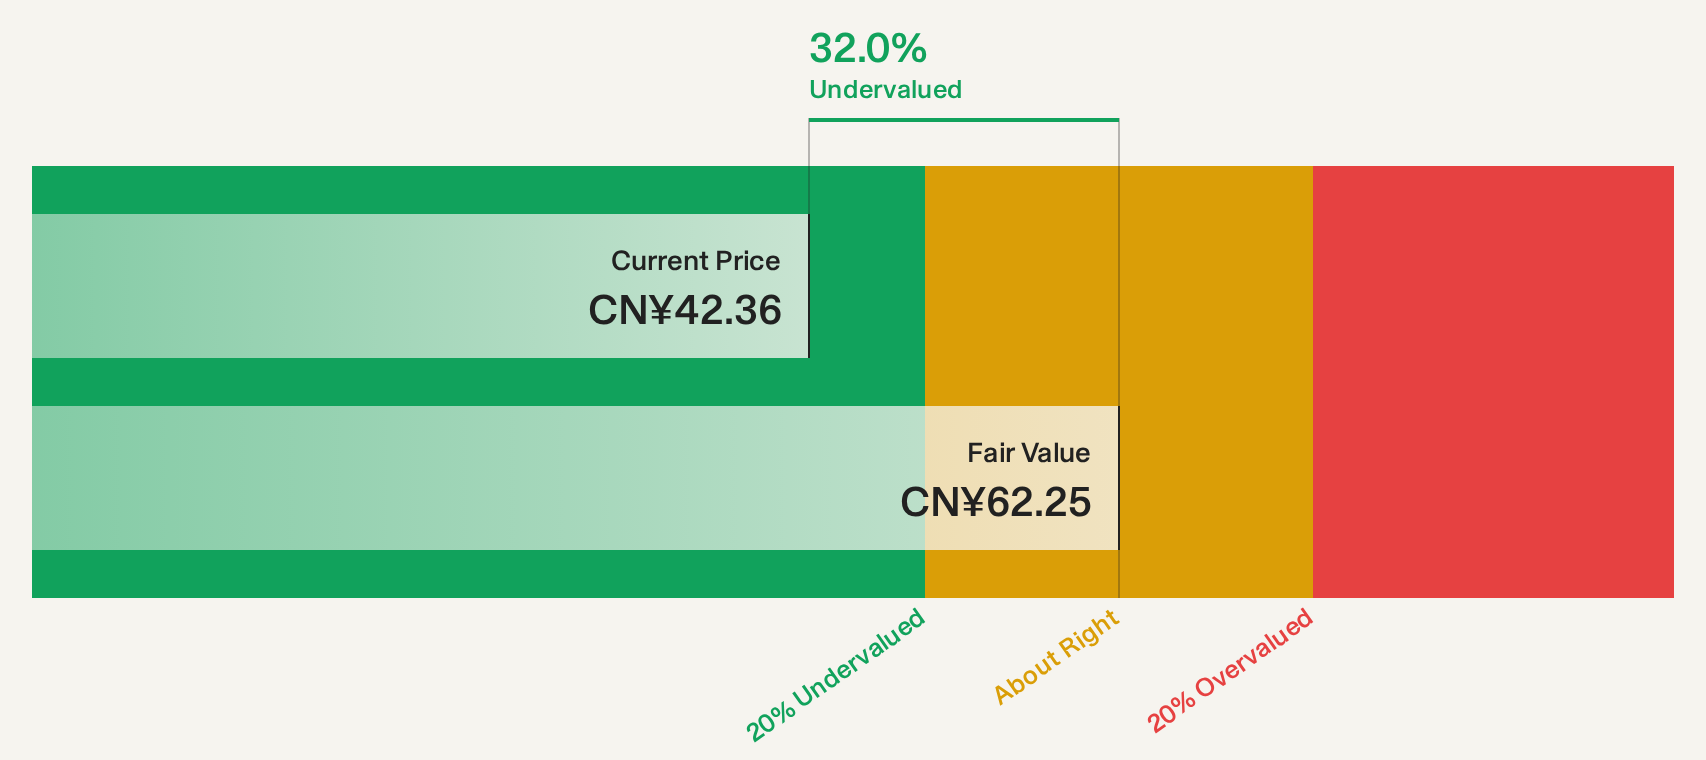
Estimated Discount To Fair Value: 38.3%
Pharmaron Beijing, trading at CN¥38.02, is highly undervalued with a future cash flow estimate of CN¥61.59. Earnings are projected to grow significantly at 26.6% annually, though slightly slower than the market, while revenue growth outpaces the Chinese market at 16.9%. Recent financials show increased sales and net income for H1 2026. The company completed a CNY 2.22 billion fixed-income offering and revised its accounting policies to align with business trends without affecting financial figures.
- Insights from our recent growth report point to a promising forecast for Pharmaron Beijing's business outlook.
- Take a closer look at Pharmaron Beijing's balance sheet health here in our report.
Key Takeaways
- Click here to access our complete index of 183 Undervalued Asian Stocks Based On Cash Flows.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com