


EN
Why Ladder Capital (LADR) Is Back In The Spotlight
Ladder Capital Q3 earnings put fresh numbers in focus for investors
Ladder Capital (LADR) just put new numbers on the table with its third quarter 2026 results, reporting US$30.66 million in sales and US$65.87 million in net income.
The earnings release on 16 October arrives after a mixed stretch for Ladder Capital, with the share price down 16.13% year to date but supported by a 26.52% three year total shareholder return. Recent momentum has started to stabilise, with a 2.53% 30 day share price return around the US$9.31 mark. This suggests investors are reassessing the risk and income profile of the real estate focused lender as fresh quarterly figures reset expectations.
Compare Ladder Capital's latest earnings reset with a curated group of resilient financials screened for balance sheet strength and fundamentals in our list of solid balance sheet and fundamentals (24 results).
Ladder Capital now trades around US$9.31 while sitting close to a near 18% discount to one fair value estimate and about 20% below analyst targets. Is that caution a warning sign, or an opening for value hunters?
Most Popular Narrative: 22% Undervalued
Ladder Capital's most followed narrative puts fair value at $12.00, above the last close at $9.31. This frames the current discount as a question of whether the income mix and funding profile justify closing that gap.
The company's diversified business model, with granular secured loans alongside a roughly US$1b income producing net lease real estate portfolio that generated US$18 million of NOI in Q2 2026, continues to provide multiple income streams that can help stabilize revenue and net operating margins through different parts of the credit cycle.
See why 7 investors see Ladder Capital as 22% undervalued.
Result: Fair Value of $12.00 (UNDERVALUED)
Still, the narrative can break if multifamily loan collateral softens, or if higher funding costs persist and squeeze Ladder Capital's net interest margins.
Find out about the key risks to this Ladder Capital narrative.
Another View: Ladder Capital Through The Earnings Multiple Lens
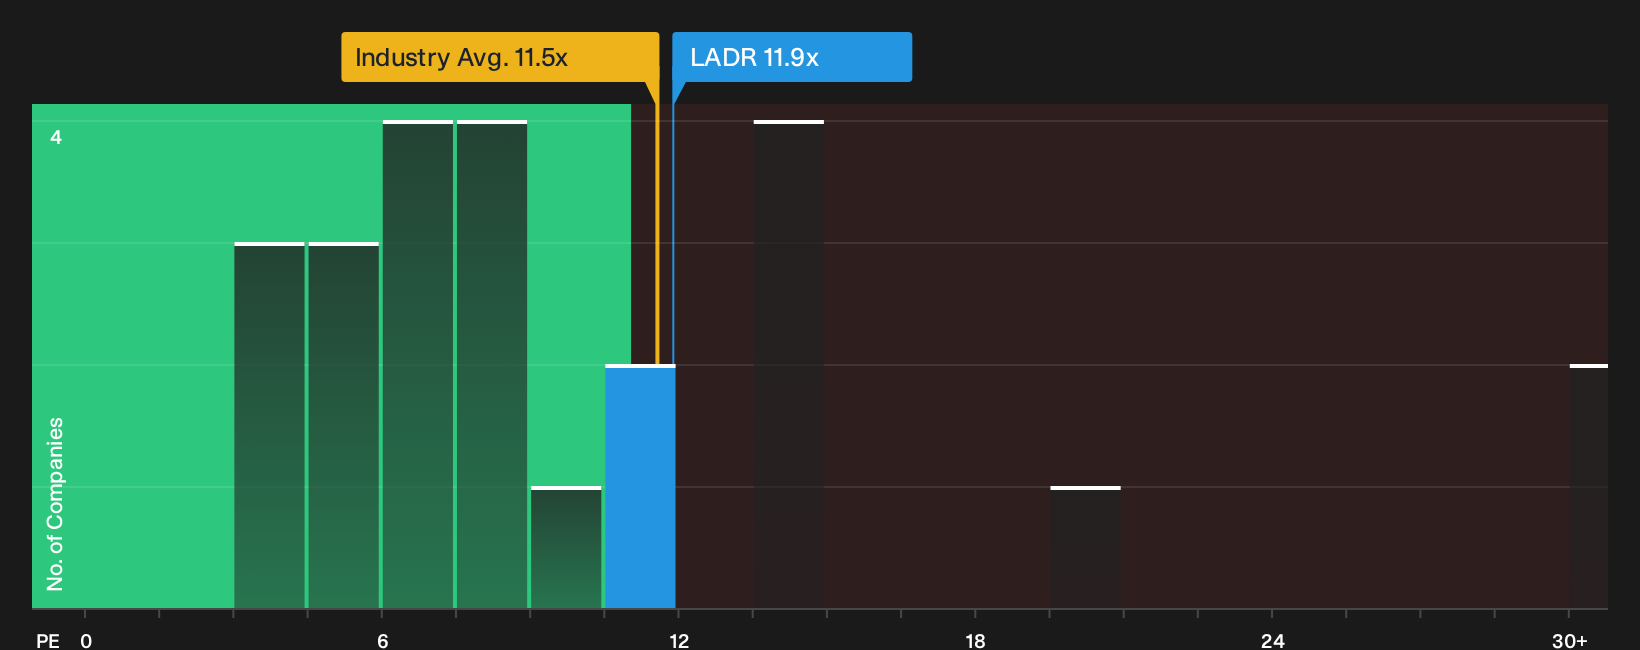
Ladder Capital may look inexpensive compared with one fair value estimate, but the earnings multiple suggests a different perspective. The stock trades on a P/E of 11.9x, which is higher than both the estimated fair ratio of 6.5x and the US Mortgage REITs sector on 11.5x. That difference highlights potential valuation risk rather than a straightforward discount. Which perspective do you rely on when you compare this with other options in your portfolio?
For a closer look at how this pricing gap compares with earnings power and sector peers, you can refer to our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ladder Capital can be confusing, so move quickly and stress test the numbers, risks and upside yourself with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Ladder Capital?
If Ladder Capital has you thinking harder about value, do not stop here. Broader context from other opportunities can sharpen your next move.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (24 results) before your next allocation decision.
- Hunt for potential mispricing by comparing Ladder Capital with a 29 high quality undervalued stocks that might fit your risk and return goals.
- Strengthen your income toolkit by lining Ladder Capital up next to a 5 dividend fortresses that could complement your existing holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com