


EN
Is Global Payments (GPN) A Bargain After Weak Returns And Worldpay Synergy Plans?
Global Payments (GPN) has drawn investor attention after recent trading left the shares around $82.82, with returns down over the past month and past 3 months despite positive annual revenue and net income growth.
Recent trading has been choppy for Global Payments, with the share price down 3.56% on the day and 4.24% over 30 days. The year to date share price return of 9.65% contrasts with a 1 year total shareholder return that declined 3.96%, hinting at fading momentum as longer term total shareholder returns over 3 and 5 years fell 16.74% and 39.11% respectively.
Scan beyond Global Payments and compare it with a curated 29 high quality undervalued stocks that includes companies with solid cash generation and balance sheets, while their recent share price performance has lagged.
Global Payments now trades well below both analyst targets and an estimated intrinsic value, after a stretch of weak longer term returns. Is this discount reflecting real business risk, or an overly cautious market setting up a valuation gap?
Most Popular Narrative: 21% Undervalued
Against Global Payments' last close at $82.82, the most followed narrative points to a fair value of $105.00, using a 9.15% discount rate to weigh future cash flows and risks into a single valuation anchor.
The Worldpay acquisition and operational transformation program are being advanced through targeted cost and revenue synergies, with management reaffirming plans for $600 million of cost and $200 million of revenue synergies on a run rate basis by the end of 2028. This can provide a multi year tailwind to earnings growth and net margin improvement.
See why 43 investors see Global Payments as 21% undervalued.
Result: Fair Value of $105.00 (UNDERVALUED)
Still, the Global Payments story depends on smooth Worldpay integration, and on travel exposed volumes not dragging revenue and earnings away from the consensus path.
Find out about the key risks to this Global Payments narrative.
Another View: What Multiples Say About Global Payments
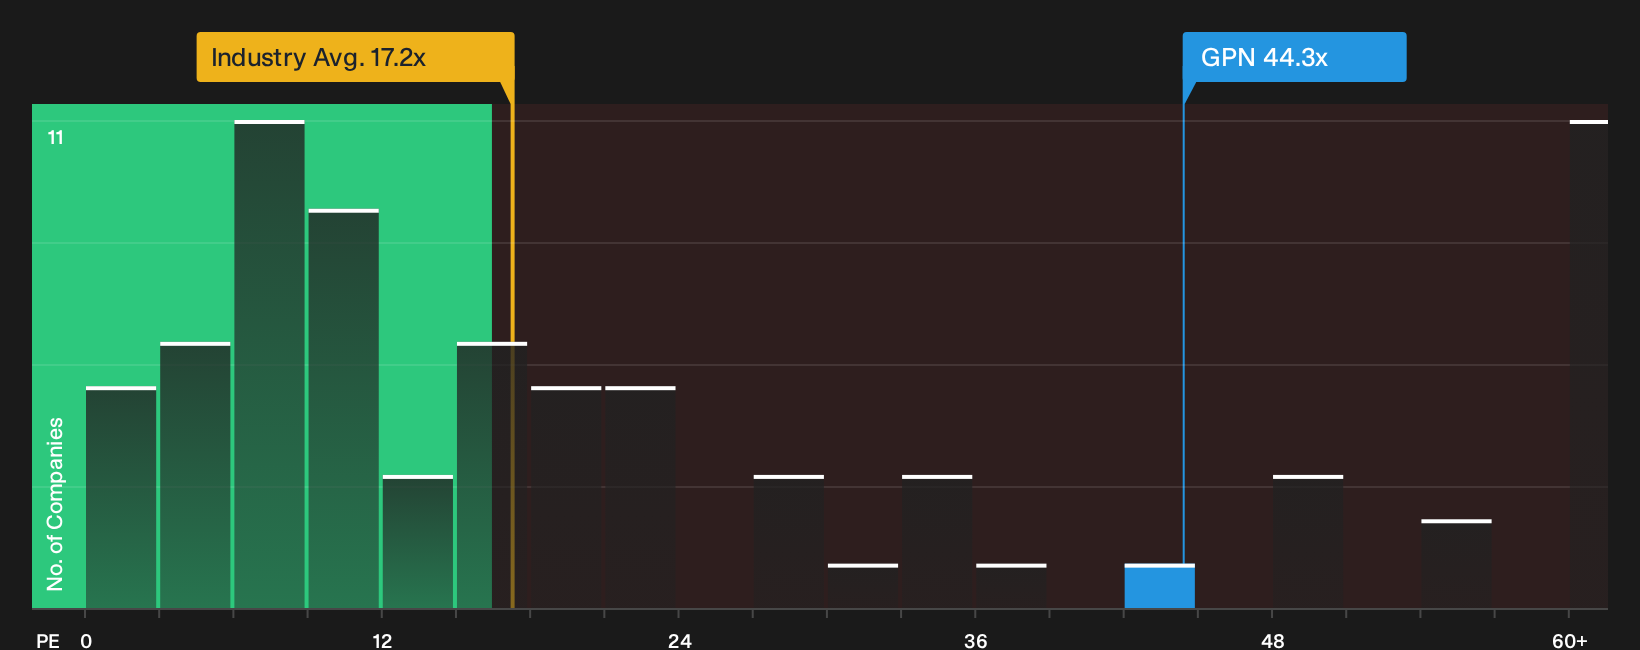
The fair value narrative for Global Payments leans on future cash flows and synergies. Yet on today’s earnings, the picture shifts. GPN trades on a P/E of 44.3x versus 17.2x for the US Diversified Financial industry and 19.4x for peers, while the fair ratio is 30.6x. That gap suggests investors are paying up for execution on forecasts that are still uncertain. If sentiment cools, does the share price move toward the fair ratio before the fundamentals catch up?
For a closer look at how this pricing gap could close over time, including where earnings need to land for today’s valuation to hold, see our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does Global Payments seem like a mispriced opportunity or a value trap in the making? Act while sentiment is still divided and review the 2 key rewards and 3 important warning signs.
Looking for more Global Payments investment ideas?
If Global Payments has you rethinking your watchlist, do not stop at one ticker. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your risk profile and return goals, so you are not chasing the same crowded ideas as everyone else.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Hunt for mispriced quality by reviewing a focused 29 high quality undervalued stocks where strong cash generation and fundamentals meet lagging share prices.
- Spot quieter opportunities before they hit the spotlight by checking a tailored 21 high quality undiscovered gems built around high quality businesses that many investors may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com