


EN
Exelixis (EXEL) Faces An FDA Delay, Is The Stock Fully Valued?
FDA delay puts Exelixis’ pipeline timing in focus
The FDA’s decision to extend its review of Exelixis (EXEL) colorectal cancer candidate zanzalintinib to March 2027 pushes out a potential approval date and puts more attention on the rest of the business.
Exelixis shares trade at US$64.53 after a small 1-day share price decline of 1.19%. Momentum has been strong, with a 10.95% 30-day share price return and a 48.07% year-to-date share price gain. This has contributed to a 1-year total shareholder return of 66.66% and a roughly 3x total shareholder return over five years as investors weigh the FDA delay against the broader oncology portfolio and existing cash-generating therapies.
Scan oncology peers that combine patent-protected cash generators with late-stage trial assets by running the hand picked 29 high quality undervalued stocks alongside Exelixis after this FDA delay.
For Exelixis, a strong year-to-date run has collided with an FDA setback that only slightly dented the share price. Are investors now paying for business resilience, or for a wave of optimism that could fade as expectations reset?
Most Popular Narrative: 18% Overvalued
Exelixis closed at $64.53, while the most followed narrative pegs fair value closer to $54.87. The FDA delay therefore lands on a stock already priced above that central estimate and places more focus on how the pipeline and cash returns evolve from here.
The main execution priority is turning CABOMETYX’s current multi billion dollar run rate and the planned zanzalintinib launches in GI and GU oncology into durable, multi franchise cash generation before the cabozantinib patent cliff early in the next decade.
The current view that Exelixis is fairly valued and bullish implies the share price already reflects a strong CABOMETYX cash engine, successful zanzalintinib approvals across key indications, and disciplined R&D and buyback-driven capital returns, without assigning much premium for additional potential beyond these elements.
See why 75 investors see Exelixis as 18% overvalued.
Result: Fair Value of $54.87 (OVERVALUED)
Still, a slower CABOMETYX NET launch and the extended zanzalintinib PDUFA timeline could both chip away at the current Exelixis optimism narrative.
Find out about the key risks to this Exelixis narrative.
Another View: Market Multiple Says Exelixis Is Cheap
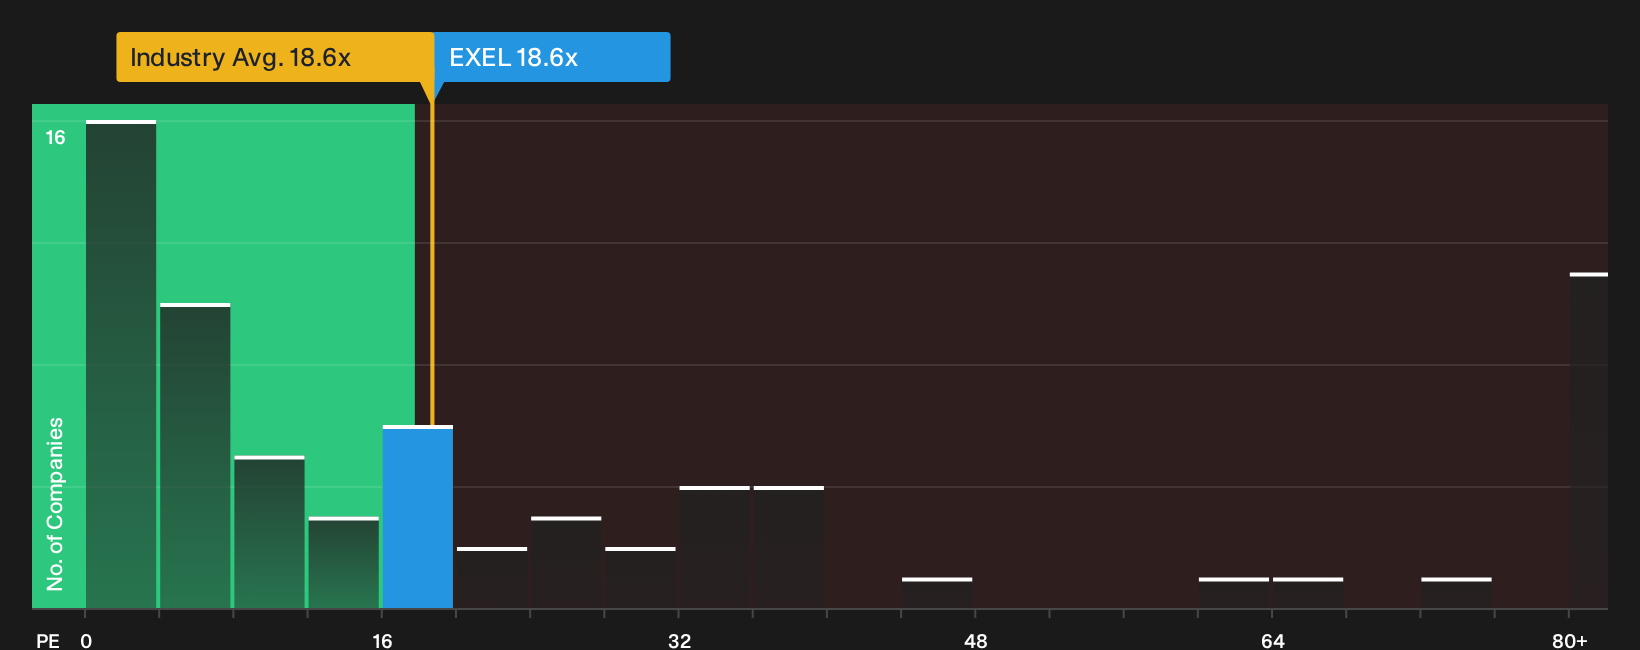
The fair value narrative points to Exelixis trading above a US$54.87 estimate. A different lens tells a very different story. On P/E, EXEL trades at 18.6x versus peers on 54.5x and a fair ratio of 23.2x, which signals less downside risk than the first model suggests. Which signal do you trust more?
For investors who prefer to anchor decisions on earnings multiples rather than cash flow forecasts, the valuation gap flagged by this P/E and fair ratio comparison can be a useful sense check when weighing the FDA delay against long term oncology cash flows. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of caution and optimism around Exelixis feels hard to pin down, it may be helpful to examine the underlying drivers directly and pressure test the upside narrative. Start by weighing the 3 key rewards
Looking for more Exelixis investment ideas?
Do not stop your research with Exelixis. Use the Simply Wall St Screener to spot fresh opportunities before they move and pressure test your current watchlist.
- Surface potentially mispriced opportunities by running the 29 high quality undervalued stocks and compare their valuations against what you see in Exelixis.
- Prioritise balance sheet strength by reviewing the list of solid balance sheet and fundamentals (24 results) so you are not relying only on optimistic stories.
- Spot under-the-radar opportunities early by scanning the 21 high quality undiscovered gems before they land on every analyst’s radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com