


EN
Fresnillo And 2 Top Silver Stocks
AI chip builders are racing ahead, and a recent US$40b debt deal by SpaceX to secure GPUs highlights how hungry the sector is for electricity and advanced hardware. That story points to one thing for investors: the world needs more power and more metals to move it. This article breaks down three potential silver mining picks from our high quality silver producers list.
The three silver miners below are just a first pass, and the full screen surfaced 7 more producers with equally compelling stories that tap into the same AI, solar and EV demand drivers. To go straight to the full Top Silver Stocks screener and start to identify, compare, and analyze the highest conviction silver producers, head into the Top Silver Stocks screener.
Fresnillo (LSE:FRES)
Fresnillo is one of the clearest pure plays on mined silver in this screen, with its flagship Fresnillo, Saucito and Juanicipio operations feeding directly into the metal that underpins AI data centers, solar panels and EV wiring demand.
Fresnillo plc runs a cluster of precious metals mines in Mexico, with revenue spread across Herradura at about US$1.4b, Juanicipio at roughly US$1.3b, Saucito at about US$1.4b, Fresnillo at around US$1.0b and several smaller sites, supporting a market value near £17.0b.
That production base already ties Fresnillo tightly to silver pricing. The real interest for this theme is how profits are being used to fund the next leg of mine development and potential cash returns.
"Record interim profitability in 1H26, with revenue, gross profit, EBITDA and operating profit all much higher year-on-year, gives Fresnillo a stronger base of retained earnings that could support a higher run rate of self funded project spend and interest income, feeding into future earnings and free cash flow."
What matters most now is how one unseen pressure on Fresnillo’s cost base shapes the gap between headline silver prices and actual long term margins.
That margin tension is exactly what the full narrative for Fresnillo unpacks, showing where costs could be decoupling from silver prices and what that might mean for future cash generation.

Silvercorp Metals (TSX:SVM)
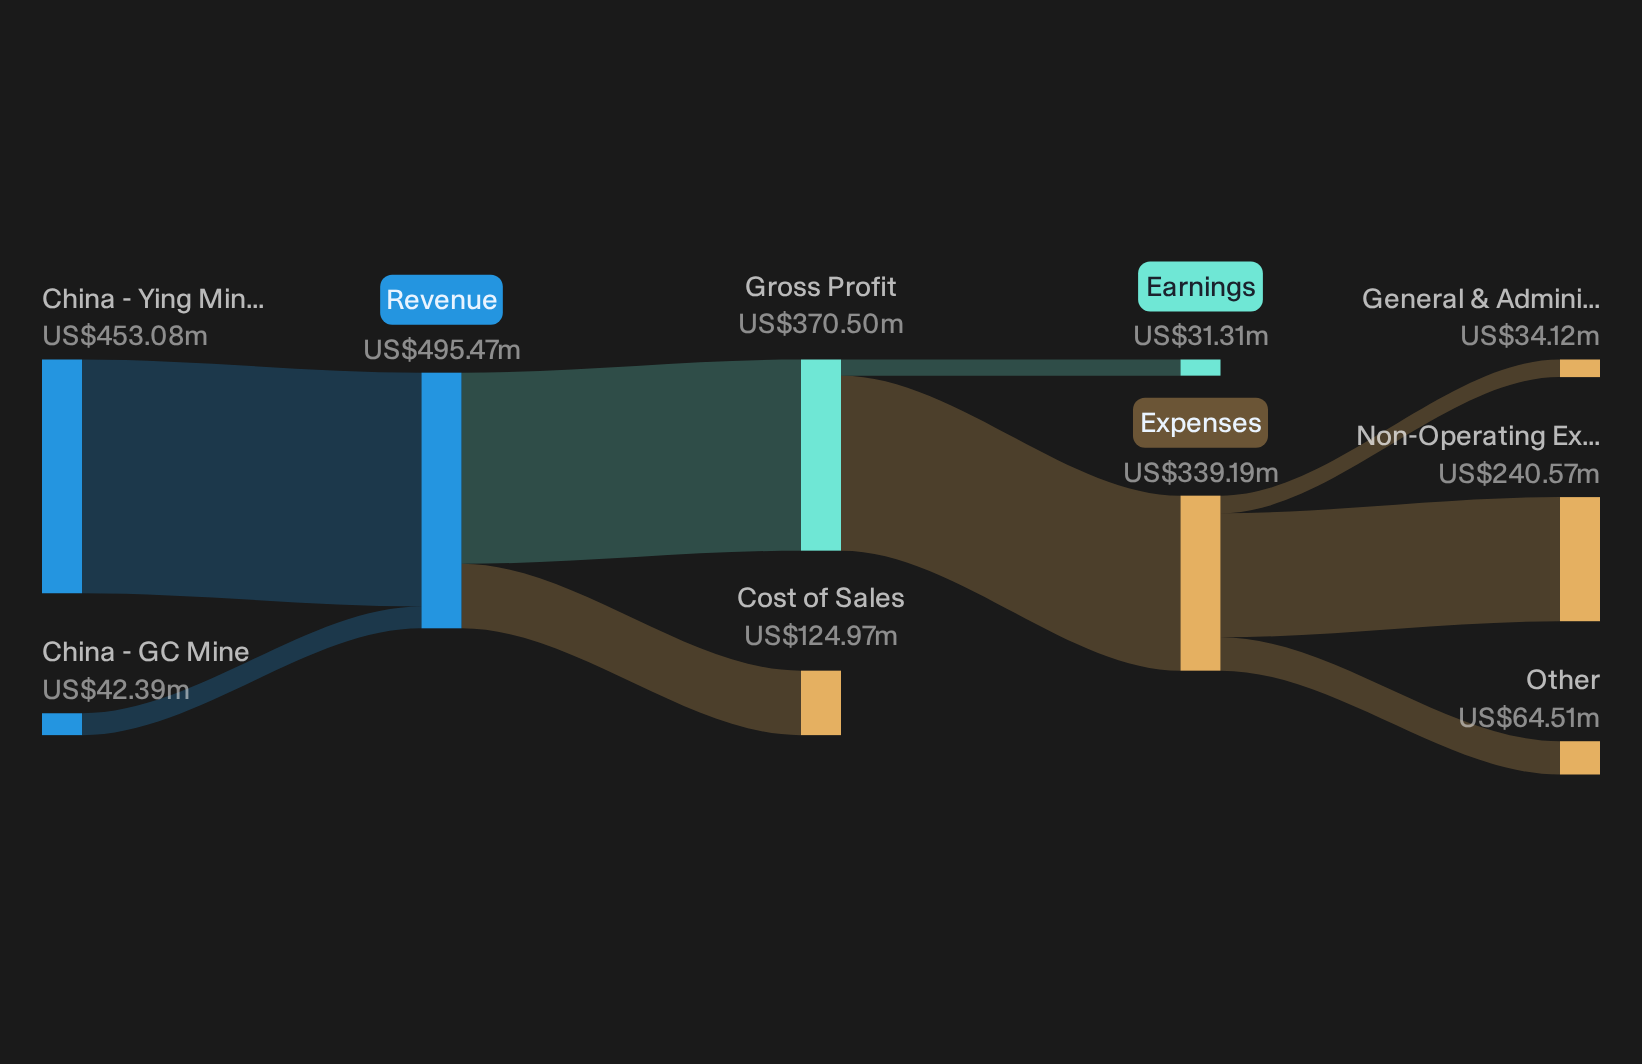
Silvercorp Metals gives you exposure to the silver theme through its Chinese mining hubs, with the Ying district at about US$453 million in revenue and the GC mine at roughly US$42 million, supporting a market value near CA$2.6 billion.
Silvercorp Metals ties its outlook closely to the same AI, solar and EV demand story, but with a different twist compared with Fresnillo. It leans on Chinese silver output while gradually spreading its asset base across new jurisdictions.
"Silvercorp is poised to benefit from sustained global growth in demand for silver driven by the ongoing transition toward renewables and electrification (notably solar, EVs, and battery storage), which should support higher realized prices and revenue growth, especially given that 66% of its Q1 revenue was generated from silver."
What ultimately counts is how one emerging pressure on Silvercorp Metals’ cost base shapes the gap between headline silver prices and lasting profitability.
That pressure point is exactly where the story gets interesting, and the full narrative for Silvercorp Metals pulls apart what might be masking Silvercorp Metals’ next phase of earnings power.
First Majestic Silver (TSX:AG)
First Majestic Silver gives you direct exposure to the silver story through a suite of producing mines in Mexico that ship primary silver into the same AI, solar and EV build out that is straining global supply.
First Majestic Silver runs high grade silver and gold operations across Mexico, led by Los Gatos at about $619 million in revenue, Santa Elena at roughly $445 million, San Dimas at around $405 million and La Encantada at about $193 million, with a smaller $52 million contribution from the US based First Mint, supporting a market value near CA$10.2b.
For investors hunting for pure access to rising silver demand, this miner links operating scale in Mexico with a focused plan to grow volumes and extend mine life.
"Robust year-over-year growth in silver production (up 76%) and record revenue (up 94%), combined with expanded exploration and accelerated mine development, position the company to capture higher sales volumes and benefit from potential increases in industrial and investment demand for silver, directly supporting future revenue growth."
What could really shift the story is how one evolving cost and spending pattern interacts with that growing production base and pricing power.
If that spending pattern is what you care about, the full narrative for First Majestic Silver shows how cost trends, growth plans and capital choices could be accelerating or masking First Majestic Silver’s potential.

Seeking Fresh Alternatives Beyond Silver?
Markets move fast and today’s quiet tickers can be tomorrow’s breakout stories. Scan fresh ideas before the crowd while the data still matters, then get in early.
- Track cash rich opportunities that the market has barely noticed by running the 5 high quality undiscovered gems before the momentum stories start flying.
- Target miners positioned for the next leg of the electrification cycle by scanning the 16 top copper producer stocks while they are still under the radar for now.
- Zero in on resilient payers that can keep income flowing even when prices swing by checking the 5 dividend fortresses and acting before yields start dropping.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com