


EN
Mitsui Fudosan Retail Fund Investment (TSE:8964) Declares Semi Annual Dividend, Is It Below Fair Value?
Mitsui Fudosan Retail Fund Investment (TSE:8964) has declared a semi-annual dividend of ¥2,220 per share, payable on March 10, 2027. The ex-dividend date is December 29, 2026, and the record date is December 31, 2026.
Against this new dividend, Mitsui Fudosan Retail Fund Investment’s unit price has softened, with a 30-day share price return of a 4.21% decline and a year-to-date share price return down 21.89%, while the 1-year total shareholder return has fallen 15.09%, pointing to fading momentum despite ongoing income distributions.
Scan income-focused opportunities beyond Mitsui Fudosan Retail Fund Investment with a curated 29 dividend fortresses that pairs meaningful yields with balance sheets built for staying power.
Mitsui Fudosan Retail Fund Investment’s units have retreated while analyst targets and intrinsic estimates sit higher, opening a clear gap. Is that discount justified by fundamentals, or has pricing moved too far?
Price-to-Earnings of 16.6x: Is it justified?
The unit price of Mitsui Fudosan Retail Fund Investment closed at ¥72,800 while it trades on a P/E of 16.6x, which screens as more expensive than the wider Asian retail REIT cohort even though it sits slightly below the peer group average used in the model.
The P/E ratio compares what investors pay today for each unit of current earnings. For a retail focused REIT such as Mitsui Fudosan Retail Fund Investment, that yardstick gives a quick feel for how the market is weighing income visibility, asset quality and earnings risk against listed rivals.
There is a tension in the signals. The SWS DCF model suggests the units change hands at a meaningful discount to an estimated future cash flow value of ¥109,898.26. In contrast, the P/E ratio is higher than the broader Asian Retail REITs industry average of 12.4x but below the peer average of 17.9x that the valuation framework uses. That split implies investors are not treating the trust as a bargain on headline earnings, even though the cash flow view and analyst targets point to a more generous valuation backdrop.
Compared with the Asian Retail REITs industry, the current 16.6x P/E sits firmly above the 12.4x industry reference point, which sends a clear message that the market is paying a richer multiple than the sector benchmark.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 16.6x (OVERVALUED).
Still, a higher P/E relative to the Asian retail REIT group, combined with a unit price that has already fallen this year, could both signal pressure if earnings disappoint.
Find out about the key risks to this Mitsui Fudosan Retail Fund Investment narrative.
Another view on Mitsui Fudosan Retail Fund Investment’s value
The P/E screen presents Mitsui Fudosan Retail Fund Investment as expensive compared with the wider Asian retail REIT group, yet our DCF model suggests a different perspective. On that cash flow basis, the units trade at a clear discount to an estimated value of ¥109,898.26. Which signal do you consider more informative when earnings and cash flows do not align neatly?
Look into how the SWS DCF model arrives at its fair value.
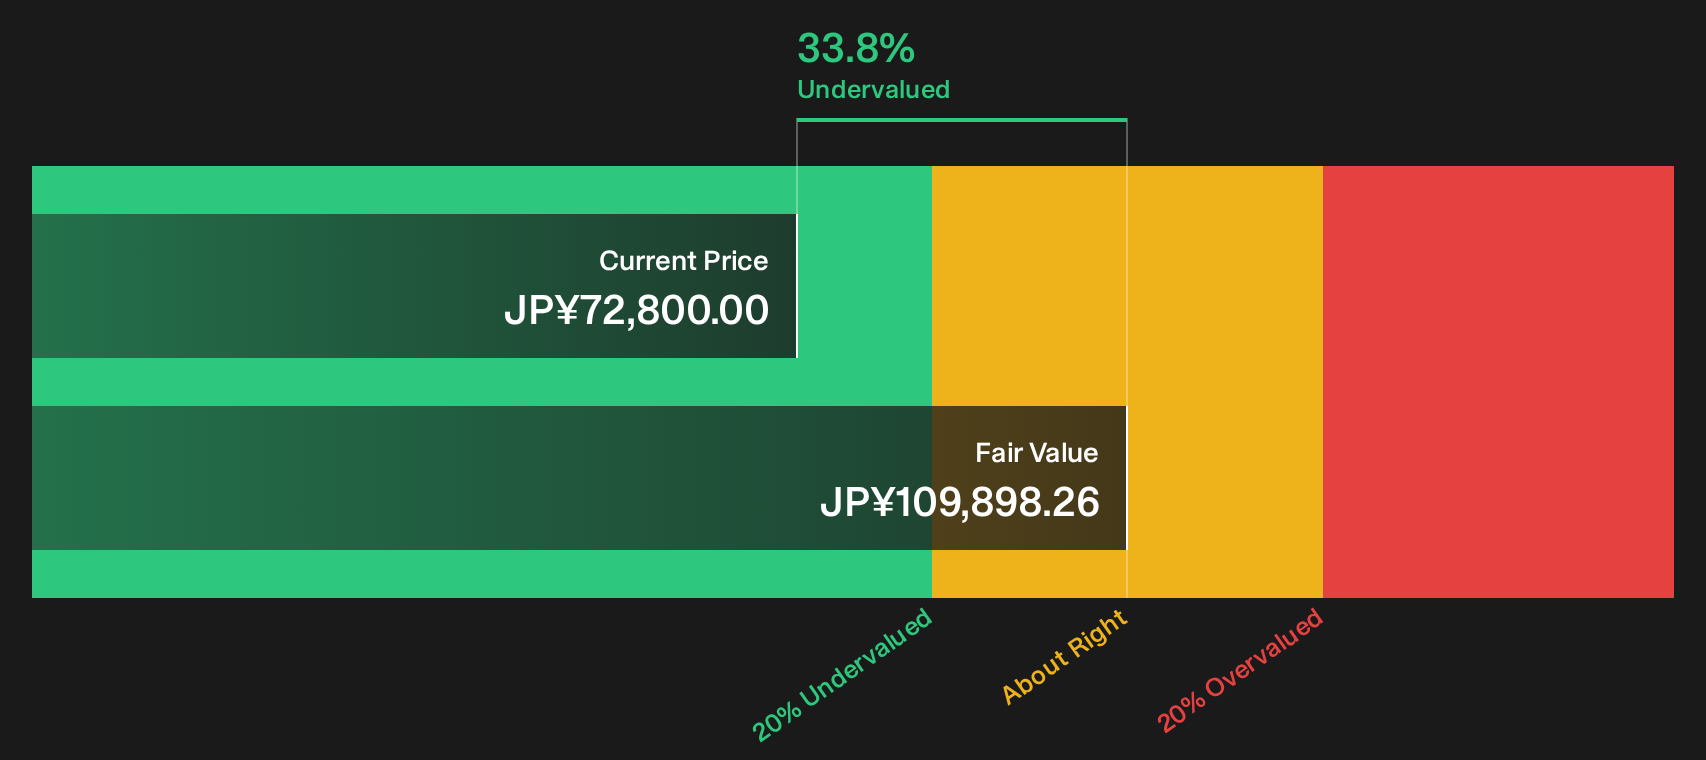
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsui Fudosan Retail Fund Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mitsui Fudosan Retail Fund Investment’s valuation and risks can feel messy, so act while the data is fresh and decide where you land. To help frame that view, take a close look at the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Mitsui Fudosan Retail Fund Investment?
If Mitsui Fudosan Retail Fund Investment leaves you undecided, broaden your watchlist with a few focused stock ideas that match your income, value, or risk preferences.
- Target steadier compounding by scanning a 22 resilient stocks with low risk scores that focuses on resilience when conditions change faster than expected.
- Zero in on potential mispricing through a curated 72 high quality undiscovered gems that filters for quality fundamentals hiding behind quieter tickers.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (23 results) that prioritizes financial strength over headline excitement.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com