


EN
Did Longer Survival Data Just Shift Jazz Pharmaceuticals' (JAZZ) Investment Narrative?
- Jazz Pharmaceuticals reported updated overall survival data from the Phase 3 HERIZON-GEA-01 trial, where Ziihera-based regimens for HER2+ gastroesophageal adenocarcinoma showed longer median survival and reduced risk of death versus trastuzumab plus chemotherapy, with safety profiles remaining consistent.
- The HERIZON-GEA-01 findings reinforce Ziihera’s recent FDA approvals and preferred status in NCCN guidelines. This could deepen its role in first-line HER2+ gastroesophageal cancer treatment and influence how investors think about Jazz Pharmaceuticals’ oncology revenue mix.
- We will look at how Jazz Pharmaceuticals’ investment narrative is affected by Ziihera’s longer median overall survival in first-line HER2+ GEA.
Jazz Pharmaceuticals Investment Narrative Recap
To own Jazz Pharmaceuticals, you need to be comfortable with a story that leans heavily on oncology execution while legacy sleep products face ongoing patent and generic pressure. The HERIZON GEA data supports Ziihera as a core growth driver and helps offset some of that concentration risk in oxybate therapies and high debt levels.
In the near term, a key catalyst remains how quickly Ziihera based regimens are adopted in HER2+ GEA following the August FDA approvals and NCCN preferred status. The biggest risk stays the same. Sleep franchise erosion or slower than expected Ziihera uptake could make the current revenue and earnings trajectory harder to sustain.
The freshest and most relevant announcement is the updated overall survival data from HERIZON GEA presented at ESMO 2026. Ziihera plus tislelizumab and chemotherapy showed 27.0 months median overall survival versus 19.6 months with trastuzumab plus chemotherapy, with a 35% reduction in risk of death and the longest reported median overall survival in a Phase 3 trial in this setting.
For Jazz Pharmaceuticals, these numbers are important to the Ziihera catalyst already flagged by analysts, including potential expansion into other HER2 driven tumors. Stronger survival data and NCCN preferred positioning can support physician confidence, payer discussions and treatment duration, while safety warnings and competing oncology agents keep execution risk firmly on the table for investors.
Jazz Pharmaceuticals' current analyst narrative points to revenues of US$5.7b and earnings of US$1.7b by 2029, based on 7.4% yearly revenue growth and an earnings increase of about US$759m from US$940.8m today.
Uncover why Jazz Pharmaceuticals' fair value indicates a 38% potential upside to its current price at a discount that could close faster than many investors expect.
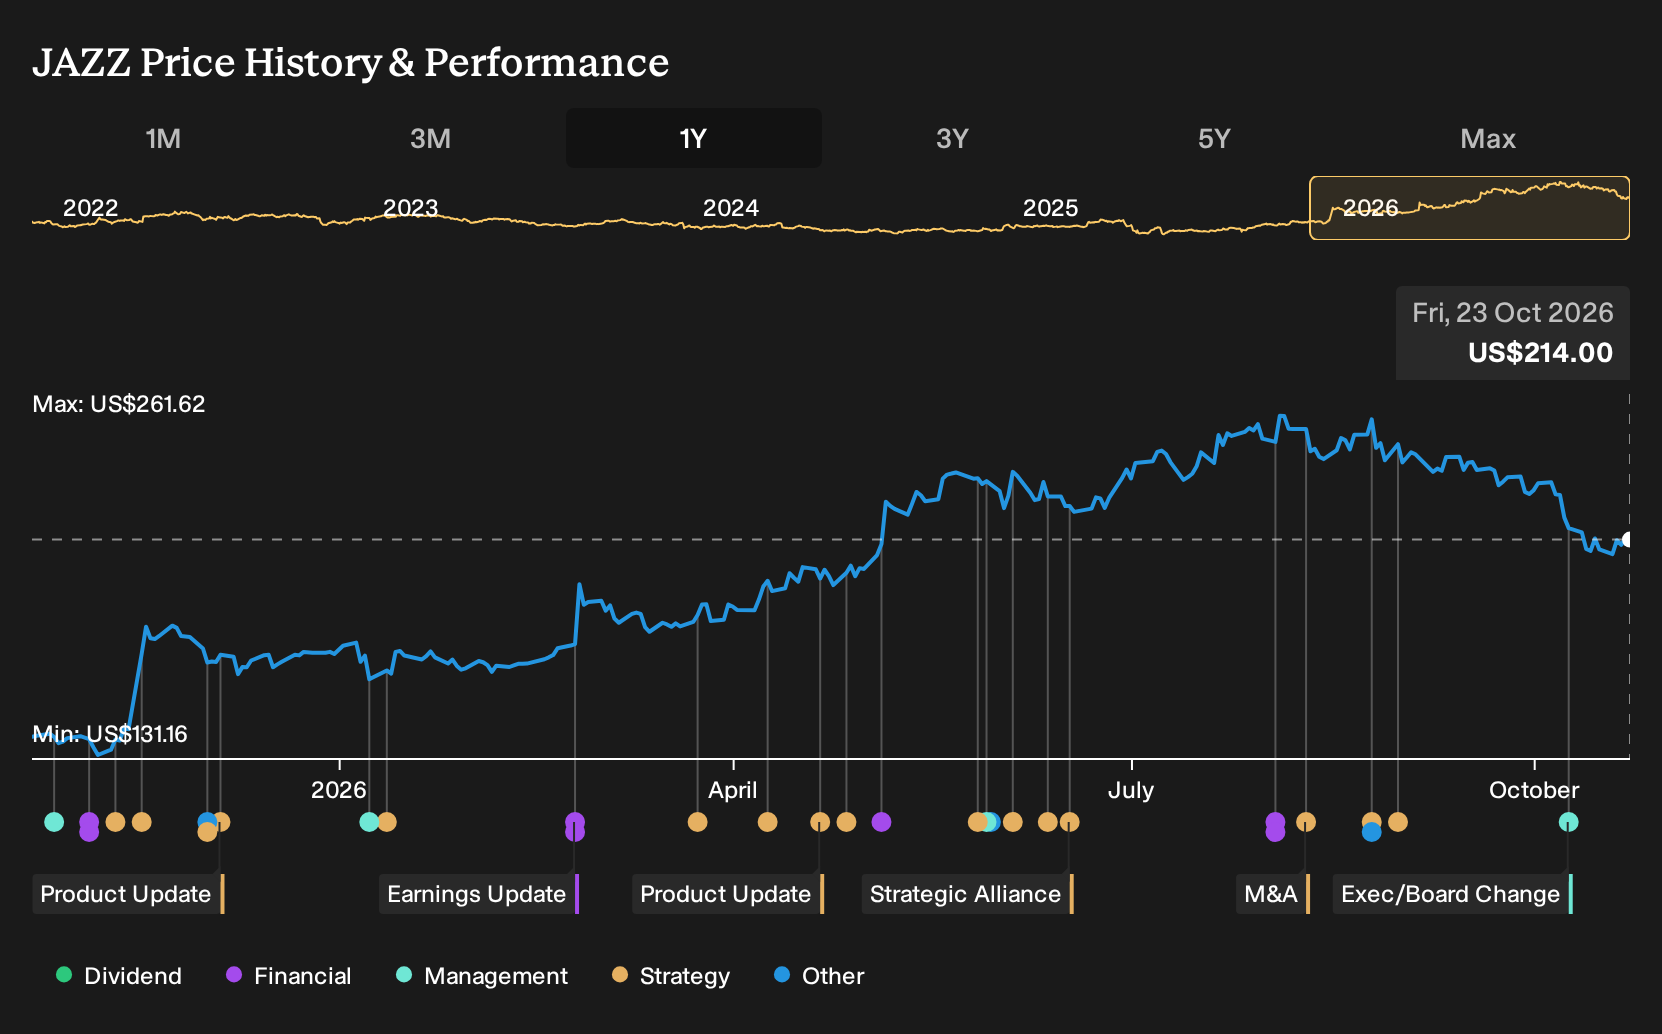
Exploring Other Perspectives
One alternate view on Jazz Pharmaceuticals focuses on oncology concentration as a risk. In that more cautious script, the lowest analysts were only penciling in about US$5.0b of revenue and US$1.3b of earnings by 2029, versus the higher consensus case. Those forecasts came before this Ziihera survival update, so opinions may move around. Use the spread in estimates as a reminder that smart people can disagree, and treat it as an invitation to compare several narratives before you commit your own capital.
Explore 3 other Jazz Pharmaceuticals fair value estimates, including one that suggests it could be worth just $237.23.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jazz Pharmaceuticals research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Jazz Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jazz Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond Jazz Pharmaceuticals?
Once you have a view on Jazz Pharmaceuticals, it can help to compare it with a wider watchlist so you are not relying on a single story. The Simply Wall St Screener gives you a structured way to look for new opportunities that fit your preferred balance of quality, valuation and risk.
- If you want potential mispricing with fundamentals in mind, scan a curated set of 29 high quality undervalued stocks that combine quality metrics with more modest expectations reflected in their prices.
- If capital preservation sits high on your checklist, focus on resilience first by filtering for 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- If you like the idea of backing under-followed stories, broaden your universe with a hand picked pool of 21 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com