


EN
What Sensata Technologies Doubters Missed
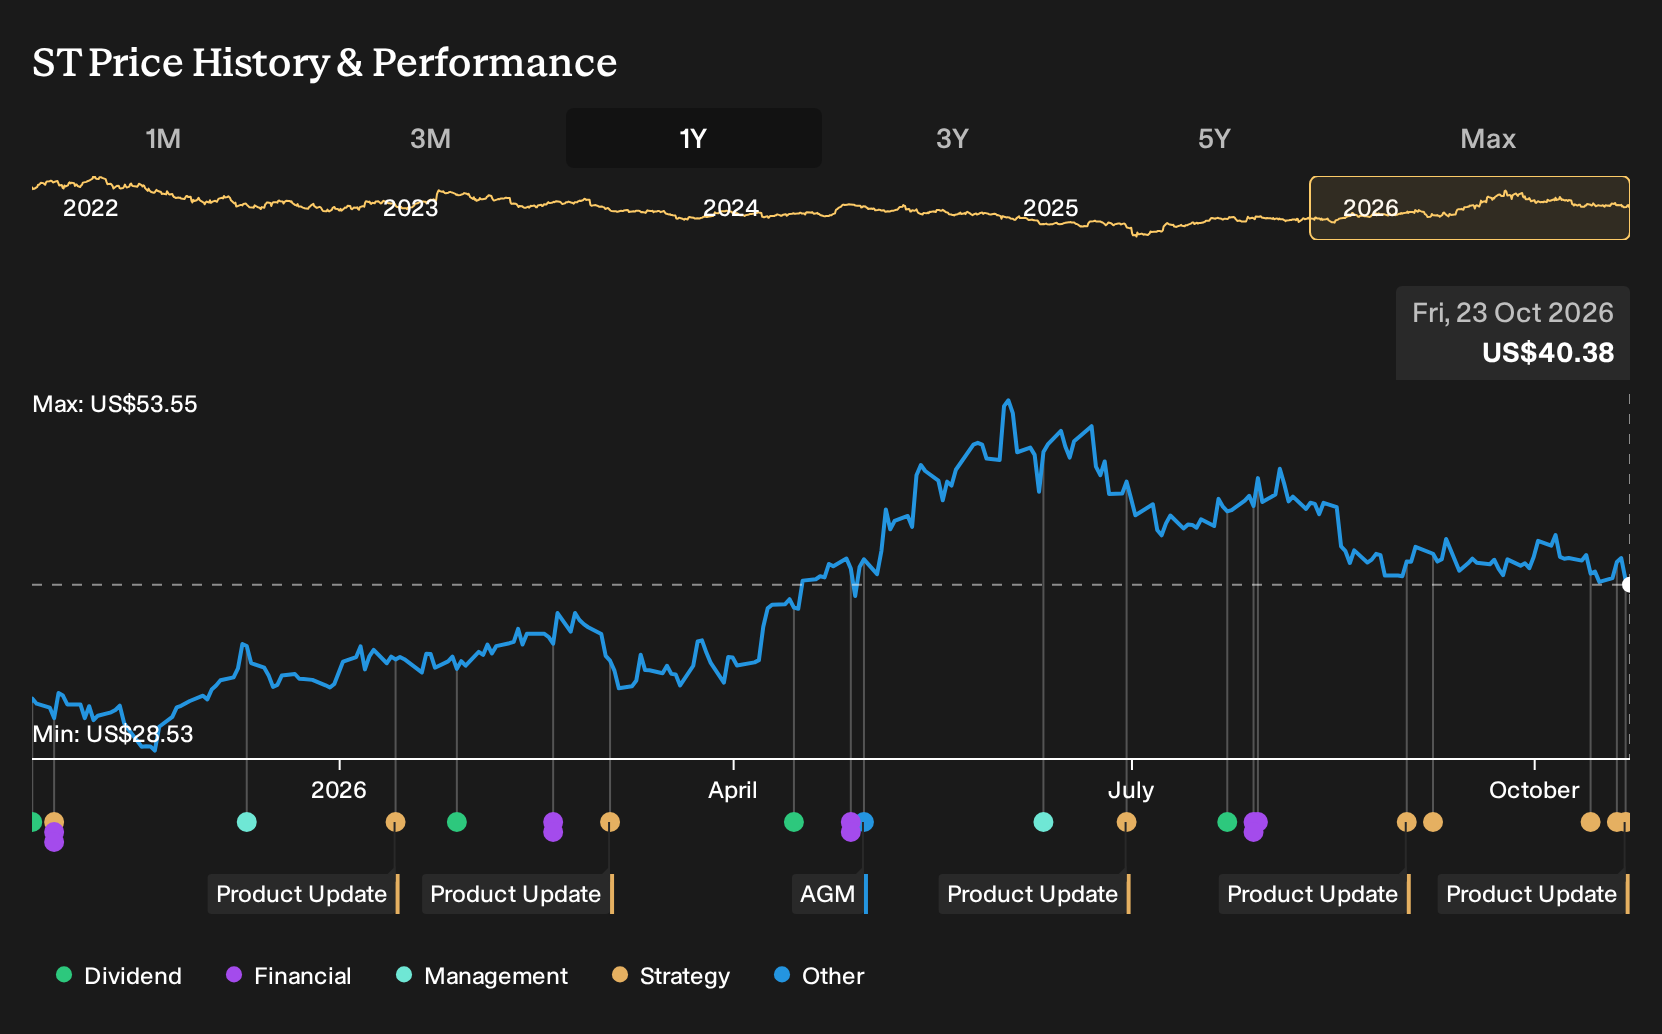
If Sensata Technologies had been sitting on your watchlist instead of in your account, the latest performance might feel like a missed shot. For Sensata Technologies shareholders, the return over the past year was 28.2%, including dividends. That outcome invites a harder question. Back on 23 October 2025, what clues already on record about China electrification wins and higher margin industrial sensing could have signalled that Sensata’s shift toward those niches might matter this much?
Sensata Technologies has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument You Would Have Been Weighing Up On Sensata Technologies
The shares cost US$32.25 at the start of the period, and investors in Sensata Technologies were essentially choosing between two very different stories about where the business might head next.
The bullish narrative saw a Fair Value of US$38.14, a price implied by assumptions that China new energy vehicle wins and higher margin specialty sensing, supported by stricter safety rules, could build richer revenue streams and improved profitability.
The bearish view focused on a Fair Value of US$30, based on concerns that rising regionalization, stronger local suppliers in China, and costly regulatory upgrades to factories could steadily erode margins even if sales still grew.
What The Results Changed For Sensata Technologies
The most telling update came from Sensata Technologies’ Q2 2026 numbers, where revenue reached US$990.6 million and net income excluding extra items was US$102.1 million. Net margin moved from 6.4% in Q2 2025 to 10.3% in Q2 2026. This leaned toward the optimistic case that higher margin sensing niches could matter, though it did not fully settle the long run China risk.
The real lesson is about which claim to test. For a story built on richer niches, focus on net margin and segment mix in each report rather than headline revenue or share price. Also check whether new products and end markets actually show up in those profitability lines.
What Sensata Technologies Buyers Are Paying For Now
At today’s share price of US$40.38, Sensata Technologies trades below the Fair Value that this Narrative outlines. That view leans on the idea that operational discipline and lower capital intensity can keep margins and free cash flow robust enough to support debt paydown and ongoing cash returns.
The distinctive swing factor is whether areas like data center content, HVAC leak detection, India auto production, and higher margin aerospace and industrial exposure can compound into a richer mix. The key question for anyone paying today’s price is whether Sensata can keep converting those shifts into durable, higher value revenue.
"The main thing that has to go right is that Sensata continues to convert the shift toward electrification, leak detection in HVAC, and data center content into growing, higher value revenue across auto, industrial, and aerospace customers."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 34% below our estimate - converts large AI infrastructure and multicloud database contracts into recurring software revenue streams.
- Company 2 - 32% below our estimate - uses a super app to integrate credit, payments and commerce across active client relationships.
- Company 3 - 49% below our estimate - works through a near record mega-project backlog while resolving complex legacy legal liabilities.
Three companies from the same screener. Open every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com