


EN
Is Carpenter Technology (CRS) Undervalued On Earnings And Fresh Guidance?
Carpenter Technology’s latest earnings jolt investor attention
Carpenter Technology (CRS) just opened its 2027 fiscal year with first quarter sales of US$798.2 million and net income of US$162.5 million, paired with fresh operating income guidance for the second quarter and full year.
The recent earnings release and fresh guidance followed a sharp reset in expectations, with Carpenter Technology’s share price down 24.5% over the past week and 50.9% over three months, even though the five-year total shareholder return is about nine times the starting point.
Scan 29 high quality undervalued stocks picked to help you compare Carpenter Technology’s sharp share price reset with other businesses that currently screen as higher quality on both fundamentals and valuation.
Carpenter Technology’s sharp slide now collides with stronger recent earnings and firm guidance. Is this really about the underlying business, or has sentiment simply swung too far and reset the valuation story?
Most Popular Narrative: 47% Undervalued
Carpenter Technology’s last close at $284.66 sits well below the most followed fair value estimate of $536.25. This frames the recent share price slide against a much richer earnings and cash flow story built into that narrative.
The brownfield capacity expansion remains on budget and on schedule for completion by the start of fiscal 2028. Management still targets roughly 9,000 additional tons of primary melt capacity and about US$150 million of incremental operating income by 2030, so the project’s contribution to higher volumes and incremental operating income from fiscal 2028 onward is now tied to explicit guidance of US$1.2b to US$1.3b operating income in fiscal 2029.
See why 26 investors see Carpenter Technology as 47% undervalued.
Result: Fair Value of $536.25 (UNDERVALUED)
Still, the whole Carpenter Technology story can change quickly if the brownfield expansion stumbles, or if aerospace and defense demand cools faster than analysts expect.
Find out about the key risks to this Carpenter Technology narrative.
Another View on Carpenter Technology’s Valuation
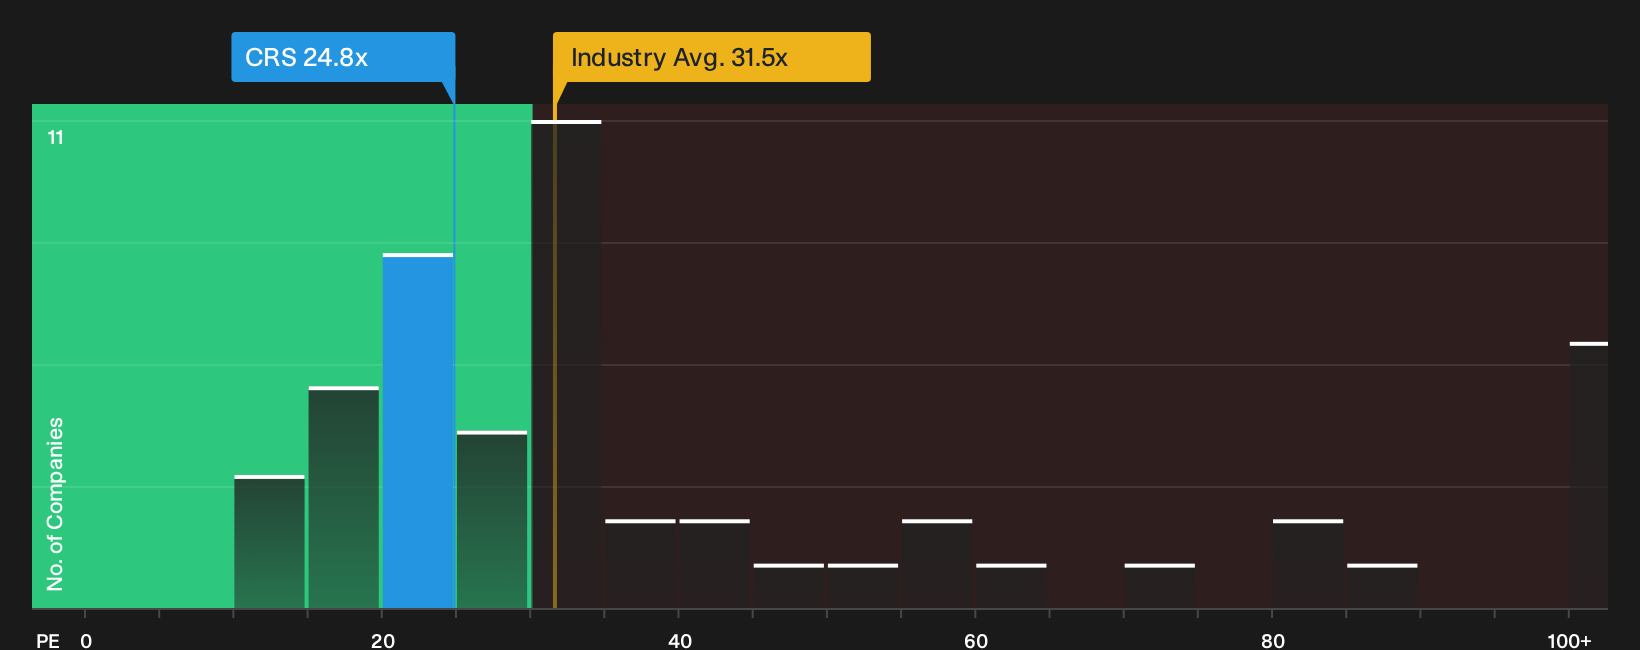
The fair value narrative around Carpenter Technology leans heavily on projected earnings and cash flows, yet its current P/E of 24.8x tells a more mixed story. That multiple is below the US Aerospace & Defense average of 31.5x, but it is above the peer group at 22.7x and just under the fair ratio of 27.5x that the market could move toward. For investors, that blend of discount to the sector and premium to peers raises a simple question: Is this pricing a cushion or a trap if expectations change?
To see how this price tag lines up against the underlying earnings profile and sector peers, including what the fair ratio suggests about future re rating risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Carpenter Technology is clearly split, with sharp price moves on one side and a detailed earnings story on the other. Act quickly, review the data for yourself, and weigh both the concerns and the upside by checking the 4 key rewards and 1 important warning sign
Hunting for more investment ideas beyond Carpenter Technology?
If you stop with Carpenter Technology, you risk missing other opportunities. Use these screeners to quickly surface fresh ideas that match the way you like to invest.
- Target reliable income potential by scanning for companies that appear to combine strong yields with staying power using the 5 dividend fortresses.
- Zero in on quality at a price by checking the 29 high quality undervalued stocks that currently look attractive on both fundamentals and valuation.
- Prioritize resilience first by focusing on a 30 resilient stocks with low risk scores that aims to highlight businesses with sturdier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com