


EN
Mapletree Logistics Trust (SGX:M44U) Faces Valuation Questions, Is It Fully Priced?
Valuation concerns resurface after prolonged unit price slide
Questions around Mapletree Logistics Trust (SGX:M44U) have sharpened as its units continue to trend lower, even while the REIT trades on a P/E ratio above the sector average.
This gap between market pricing and earnings has pushed valuation back into focus for investors, especially with capital recycling efforts and targeted asset disposals positioned as key tools to support the trust’s portfolio and unit performance.
Recent moves in Mapletree Logistics Trust show a mixed picture. The 1-day share price return of 1.87% and 7-day gain of 0.93% come after a 90-day share price decline of 8.40% and a year-to-date share price fall of 17.42%. At the same time, the 1-year total shareholder return is down 11.24%, indicating fading momentum despite the REIT’s higher P/E and ongoing asset recycling story.
Compare Mapletree Logistics Trust’s valuation pressures with other real estate plays by scanning our hand picked 194 high quality undervalued stocks, which currently trade at lower multiples with stronger support from their fundamentals.
For Mapletree Logistics Trust, a falling unit price paired with a richer P/E sets up a live decision. Do you commit at today’s level or wait for a clearer valuation reset instead?
Most Popular Narrative: 17% Undervalued
Against the last close of SGD1.09, the most followed narrative for Mapletree Logistics Trust points to a higher fair value of about SGD1.31 when all the income, risk and funding assumptions are pulled together with an 8.99% discount rate.
The current valuation implies that the market is pricing Mapletree Logistics Trust cautiously relative to its underlying operational growth, resilient occupancy and rental reversions, which this narrative views as leaving the stock undervalued and the setup bullish.
See why 47 investors see Mapletree Logistics Trust as 17% undervalued.
Result: Fair Value of SGD1.31 (UNDERVALUED)
Still, that bullish Mapletree Logistics Trust narrative can be knocked off course if China vacancies stay elevated or if funding costs drift higher and squeeze distributable income.
Find out about the key risks to this Mapletree Logistics Trust narrative.
Another View: SWS DCF Flags Overvaluation
The popular Mapletree Logistics Trust narrative leans on analyst assumptions and a fair value of about SGD1.31. The SWS DCF model tells a very different story. On that framework, future cash flows point to a value of roughly SGD0.44 per unit, which frames today’s SGD1.09 price as rich rather than cheap. Which valuation anchor do you trust more when the two are this far apart?
To understand how this cash flow based view is built, including the key assumptions that pull fair value down, Look into how the SWS DCF model arrives at its fair value.
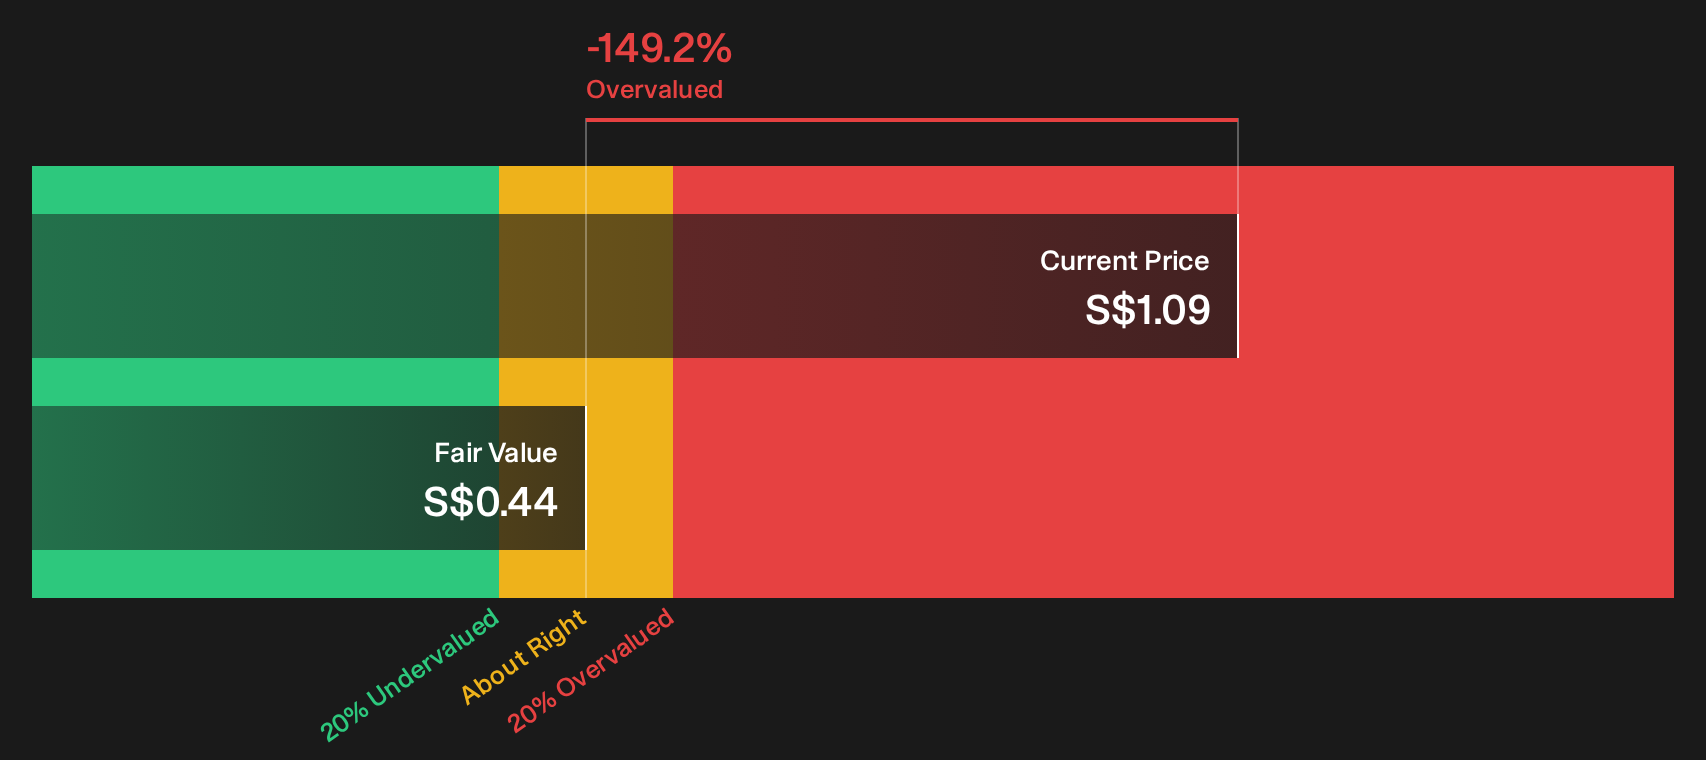
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mapletree Logistics Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split views on Mapletree Logistics Trust feel conflicted, that is the point. Move quickly, carefully review the numbers and see the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Mapletree Logistics Trust?
Do not stop your research with Mapletree Logistics Trust alone. Use these focused stock lists to hunt for better fits for your goals before the market moves on.
- Target stronger balance sheets by checking companies in the list of solid balance sheet and fundamentals (207 results) that pair healthier finances with more resilient fundamentals.
- Hunt for potential mispricing across markets using the 194 high quality undervalued stocks that highlights businesses trading on lower valuations with support from their numbers.
- Build a steadier income stream by reviewing the 229 dividend fortresses and focusing on companies offering higher yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com