


EN
Healthpeak Properties (DOC) Looks Undervalued On Paper, Is The Upside Already Priced In?
Healthpeak Properties (DOC) has drawn investor attention after its recent share performance, with the stock closing at US$19.25 and showing mixed returns over the past year across multiple time frames.
Recent trading paints a mixed picture for Healthpeak Properties, with the share price slipping around 5% over the past month and about 15% over the last quarter. This comes even though the year-to-date share price return is almost 19% and the 3-year total shareholder return is above 40%.
Scan how Healthpeak Properties compares with other real estate players showing mixed momentum and value signals by reviewing the hand picked 29 high quality undervalued stocks in the same space.
Healthpeak Properties has already put up a near 19% gain this year, yet the shares now sit well below some value estimates. Has most of the easy upside gone, or is the market still underpricing this REIT’s portfolio and cash flows?
Most Popular Narrative: 15% Undervalued
Healthpeak Properties is framed as undervalued in the most followed narrative, with an estimated fair value of about $22.61 against the recent $19.25 close. This puts the spotlight on how its real estate mix and capital recycling might support that gap.
The accelerating shift of surgical and specialty care from inpatient hospital settings to outpatient centers, supported by Healthpeak Properties reporting roughly 5% cash re leasing spreads for 10 consecutive quarters with about 3% annual rent escalators and low tenant improvements, continues to support stronger same store outpatient NOI and cash flow.
See why 35 investors see Healthpeak Properties as 15% undervalued.
Result: Fair Value of $22.61 (UNDERVALUED)
Still, the Healthpeak Properties story depends on a lab portfolio where same store NOI has declined and on capital recycling deals that may not repeat on similar terms.
Find out about the key risks to this Healthpeak Properties narrative.
Another View: Healthpeak Properties Through Earnings Multiples
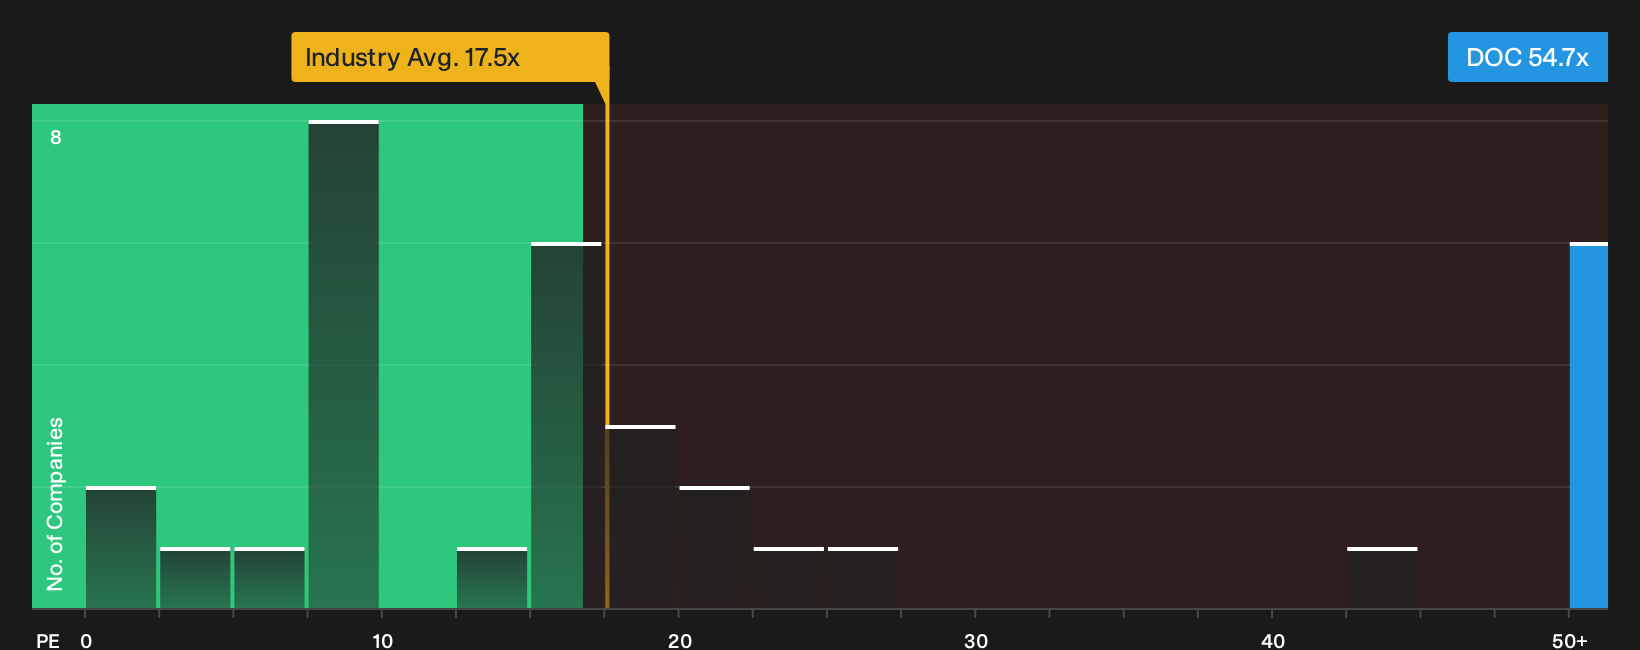
On the flip side of that fair value of $22.61, Healthpeak Properties trades on a P/E of 54.7x. That is far above the Health Care REITs industry at 17.5x and the fair ratio of 21.4x. Such a gap can signal valuation risk if earnings expectations do not hold up. Which signal do you trust more?
Investors weighing this richer P/E against peers and the fair ratio may want to stress test their own assumptions about future cash generation and multiple risk before acting, then review the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Healthpeak Properties so far. If you want to move quickly and base your call on the full picture of risks and upsides, start by weighing the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond Healthpeak Properties?
If Healthpeak Properties has sharpened your thinking, do not stop here. The next opportunity you miss is usually the one you never went looking for.
- Target resilient income and reduce guesswork by scanning companies built to pay, then keep paying, through the 5 dividend fortresses.
- Hunt for strong balance sheets that can handle shocks by running a focused search with the list of solid balance sheet and fundamentals (24 results).
- Spot potential future leaders before the crowd by working through a curated 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com