


EN
Is BIPROGY (TSE:8056) Fully Priced After Its Recent Rebound?
Recent price action and business snapshot
BIPROGY (TSE:8056) has drawn investor attention after its latest closing price of ¥5,124, with recent returns over the past month and past 3 months contrasting with a weaker 1-year performance.
Recent trading suggests momentum in BIPROGY is rebuilding, with a 30-day share price return of 6.91% and a 90-day gain of 10.86%, while the year to date share price performance is weaker and trails the 1-year total shareholder return decline of 13.62%.
Scan BIPROGY alongside other potential rebound stories by reviewing a curated set of 14 high quality undervalued stocks that pair recent weakness with solid fundamentals.
For BIPROGY, a 3 month rebound sitting against a weaker 1 year return raises a simple tension. Are investors re-rating the business, or simply shifting sentiment on a previously out-of-favor stock before any clear valuation anchor emerges?
Preferred P/E multiple of 16.6x: Is it justified?
On valuation, BIPROGY trades on a P/E of 16.6x, which sits slightly above the JP IT industry average of 16.4x and below both its peer group and an estimated fair P/E level.
The P/E ratio links the current share price to earnings per share and helps show how much investors are paying for each unit of profit. For a software and services group like BIPROGY, this metric tends to matter because earnings quality, contract visibility, and the mix between services and outsourcing can influence what investors are willing to pay.
Here, the picture is mixed. The stock is described as expensive relative to the broader JP IT industry at 16.6x versus 16.4x. At the same time, that same P/E is presented as better value when set against a peer average of 25.6x and a fair P/E estimate of 21.9x that the market could move towards if sentiment or results change. These points indicate investors are not assigning a premium price for BIPROGY despite the description of its earnings as high quality and the reference to a track record of earnings growth over the past five years.
Explore the SWS fair ratio for BIPROGY.
Result: Price-to-Earnings of 16.6x (ABOUT RIGHT)
Still, BIPROGY faces pressure if earnings momentum stalls or if demand for its cloud and outsourcing offerings softens. This could undermine the current P/E story.
Find out about the key risks to this BIPROGY narrative.
Another view on BIPROGY’s value
The earlier P/E check on BIPROGY suggests the share price looks roughly fair, yet a different lens tells a slightly stronger story. Our DCF model estimates fair value at ¥5,411.1 per share, which is about 5.3% above the recent price of ¥5,124 and points to mild undervaluation.
For investors, that gap is not huge, but it does raise a question: Is the market underappreciating BIPROGY’s future cash generation, or is the discount a simple cushion against slower growth forecasts?
Look into how the SWS DCF model arrives at its fair value.
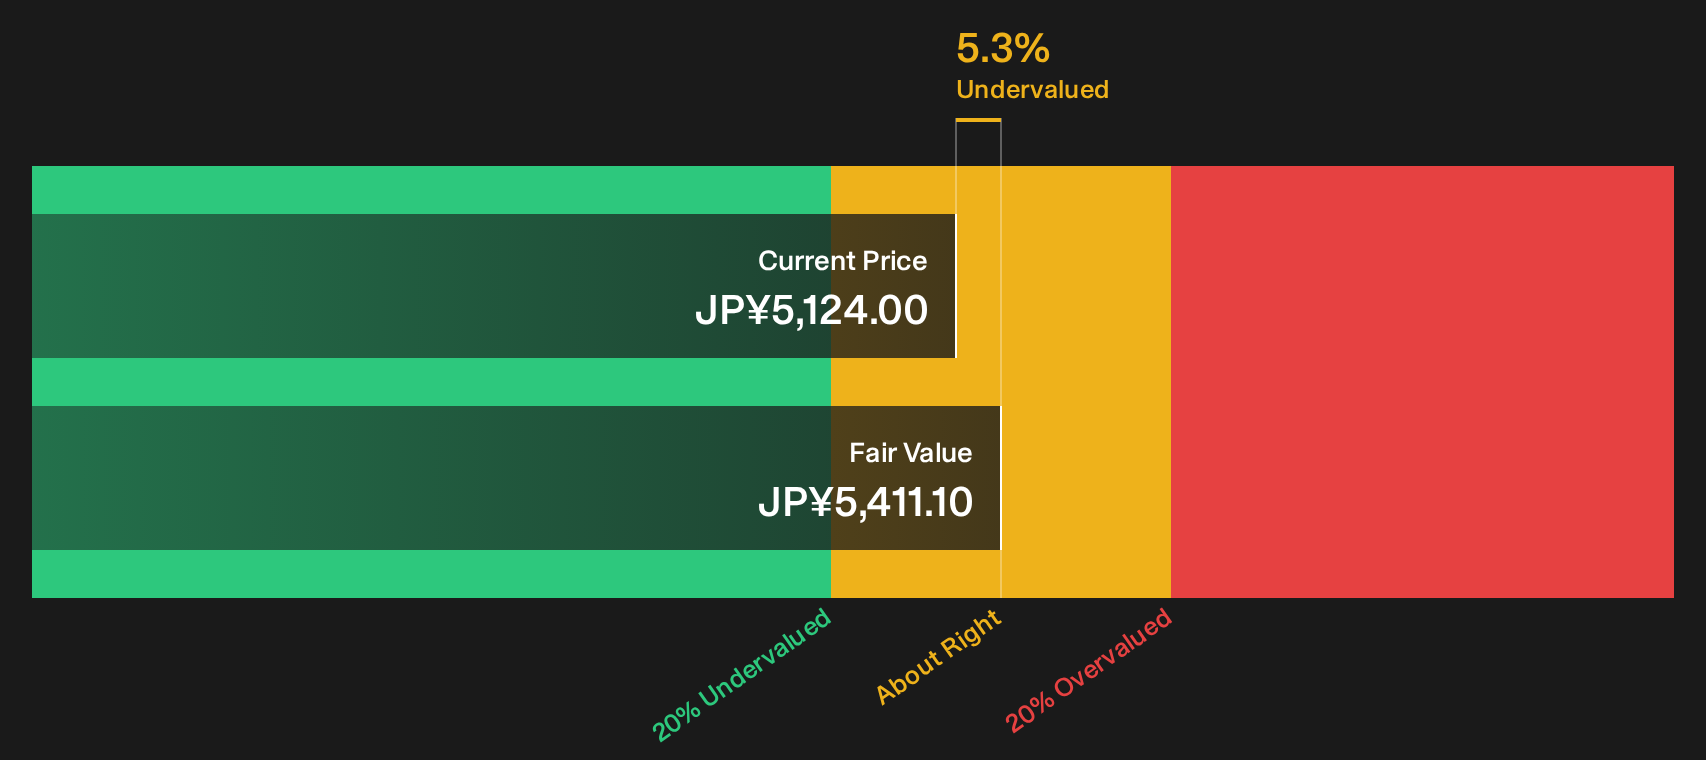
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BIPROGY for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around BIPROGY’s valuation and recent share price move only matter if they shift your own conviction. Review the full picture quickly and weigh both the potential upside and the issues flagged in our 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BIPROGY?
Do not stop with a single opportunity. Use the Simply Wall Street Screener to quickly compare different businesses, spot patterns, and build a watchlist that truly fits your style.
- Target potential upside by scanning a curated 72 high quality undiscovered gems that combine quality fundamentals with limited current market attention.
- Prioritise resilience first by reviewing a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio through different market conditions.
- Dial down portfolio stress by shortlisting a 22 resilient stocks with low risk scores focused on businesses with more robust risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com