


EN
How Investors May Respond To SiteOne (SITE) DCF Value And Digital Sales Growth
- SiteOne Landscape Supply is back in focus as fresh discounted cash flow work suggests its projected cash generation implies an intrinsic value above the current stock price.
- The push into digital tools and e-commerce, with management expecting online sales to exceed US$600 million in 2026, is becoming central to how investors frame SiteOne’s operating potential.
- We will look at how SiteOne Landscape Supply's investment narrative is shaped by renewed focus on intrinsic value and digital sales progress.
Compare SiteOne Landscape Supply's setup with a curated list of other potential value candidates available in our 29 high quality undervalued stocks to see how its cash flow story stacks up.
SiteOne Landscape Supply Investment Narrative Recap
To own SiteOne Landscape Supply, you need to believe the wholesale distributor can convert its digital push, private label mix and acquisition program into steadier cash generation despite choppy construction and renovation markets. The fresh discounted cash flow work reinforces that debate but does not change the near term reality that volumes and pricing need to hold up.
The near term catalyst is clearer progress on margins and digital adoption, especially with volumes having softened in key Sunbelt regions recently. The biggest risk remains end market cyclicality combined with already modest organic growth, which could keep returns and sentiment subdued if execution on mix, costs and deal integration underwhelms.
Recent commentary around SiteOne Landscape Supply’s digital channel is the most relevant development for this story. Management expects online sales to exceed US$600m in 2026 compared with about US$420m on siteone.com in 2025. For you, that frames a concrete, measurable pillar of the intrinsic value narrative rather than an abstract technology promise.
Stronger e-commerce penetration can influence several of the key catalysts investors are tracking, including customer retention, salesforce productivity and gross margin mix. The same update also sharpens the risk lens. If digital growth slows or fails to translate into better profitability, the argument that current cash flow forecasts justify an intrinsic value above today’s share price becomes much harder to sustain.
SiteOne Landscape Supply's narrative projects US$5.4b revenue and US$261.2m earnings by 2029. This is based on an assumption of 4.2% yearly revenue growth and an earnings increase of about US$98.4m from US$162.8m today.
Uncover why SiteOne Landscape Supply's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
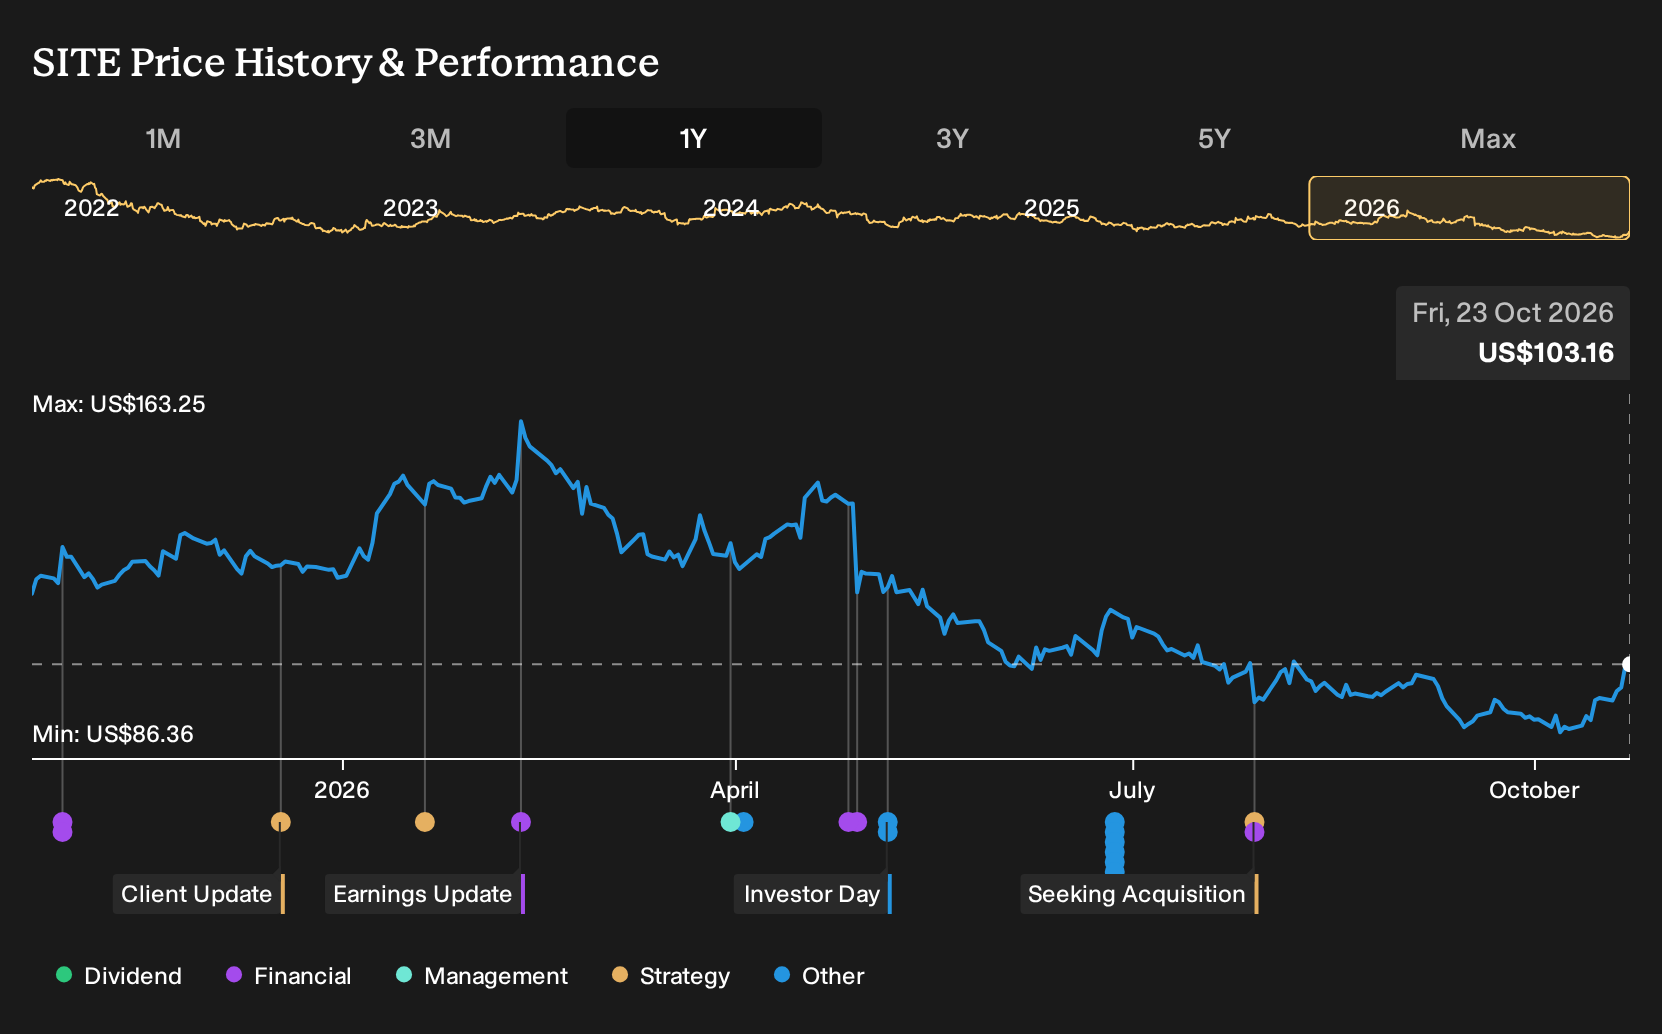
Exploring Other Perspectives
One alternate angle on SiteOne Landscape Supply leans heavily on the self help story. Some analysts focused on branch efficiency and mix shifts were estimating revenue of about US$5.8b and earnings of roughly US$319.3m by 2029, compared with the baseline US$5.4b and US$261.2m. Those projections were set before this latest DCF driven valuation discussion, so opinions may change as the new information is absorbed and a range of scenarios is explored rather than relying on a single forecast path.
Explore 3 other SiteOne Landscape Supply fair value estimates, including one that suggests as much as 55% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Instead, dig into the data and build a conviction that is truly your own.
- A great starting point for your SiteOne Landscape Supply research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for SiteOne Landscape Supply. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SiteOne Landscape Supply's overall financial health at a glance.
Looking For More Investment Ideas Beyond SiteOne Landscape Supply?
Once you have a view on SiteOne Landscape Supply, it helps to set that against a wider watchlist of opportunities that fit different risk and return profiles. The Simply Wall St Screener can filter the market down to a focused set of companies that match the type of portfolio you want to build.
- If you want to focus on income and staying power, start with resilient payers by scanning through 5 dividend fortresses that combine high yields with durability.
- If capital preservation sits higher on your list, cut out some of the drama by screening for 30 resilient stocks with low risk scores that score well on stability and downside protection.
- If balance sheet strength matters most to you, build a watchlist around the list of solid balance sheet and fundamentals (24 results) and filter for businesses with cleaner debt profiles and solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com