


EN
Earnings Beat Change The Bull Case For Getinge Stock
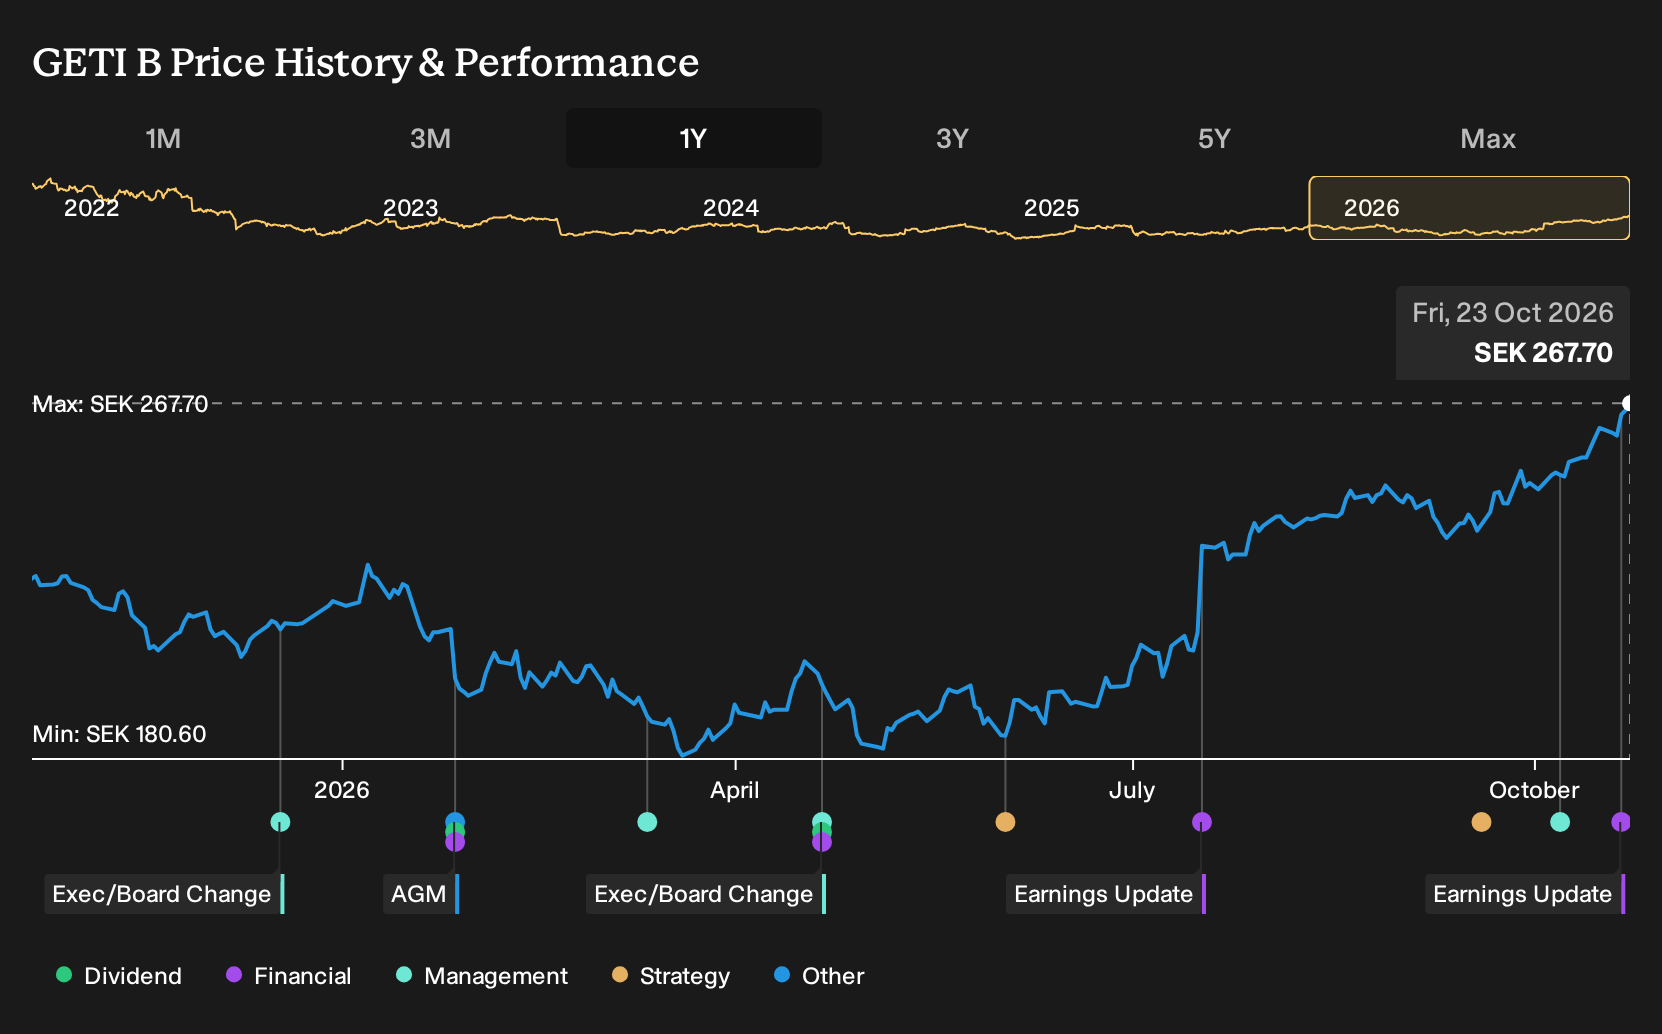
- Getinge reported third quarter 2026 sales of SEK 8,446 million, net income of SEK 719 million and basic EPS from continuing operations of SEK 2.64, all higher than the same period a year earlier.
- Across the first nine months of 2026, net income and basic EPS from continuing operations increased compared with 2025 despite slightly lower sales, which highlights a focus on profitability and cost control.
- We will now look at how Getinge's higher third quarter net income might influence the longer term investment narrative investors are watching.
Scan how Getinge's earnings shift compares with peers by reviewing the hand picked list of solid balance sheet and fundamentals (207 results) that are also focused on profitability and financial discipline.
Getinge Investment Narrative Recap
To own Getinge, you need to believe the higher share of recurring, higher margin revenue can support more consistent earnings while quality remediation costs gradually ease. The latest quarter fits that story, with net income and EPS rising faster than sales. The near term swing factor remains how quickly extraordinary quality related expenses come down.
The biggest operational risk is that rising tariffs and sticky cost inflation in labor and logistics eat into that margin progress, especially with more fixed price contracts and China described as challenging. The Q3 figures do not remove those pressures, but they show the business currently absorbing them reasonably well.
Among recent developments, the most relevant backdrop for this Q3 report is the ongoing effort to reduce roughly SEK 800m of extraordinary quality related costs tied to cardiopulmonary and cardiac assist remediation and remaining 510(k) submissions. Earnings holding up while those costs are still in the system suggests meaningful operating leverage if they taper as planned.
That same clean up program sits alongside growth initiatives in Life Science and Surgical Workflows, including a higher mix of infection control, consumables and digital solutions as well as investments like Paragonix. For you as a shareholder, the key question is whether Getinge can execute on those projects while managing tariff exposure and a tougher China market without eroding the margin gains visible in the latest numbers.
What The Getinge Forecasts Assume
Getinge's narrative projects SEK 40.2b revenue and SEK 4.0b earnings by 2029. This implies 5.5% yearly revenue growth and an earnings increase of about SEK 1.3b from SEK 2.7b today.
Uncover how Getinge's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the lowest analysts frame tariffs as the real swing factor for Getinge. They were pencilling in SEK 40.1b of revenue and about SEK 4.0b of earnings by 2029, yet still argued that tariff and regulatory costs could keep profitability tight. The latest Q3 beat might push those views to evolve.
Explore 4 other Getinge fair value estimates, including one that suggests as much as 28% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgement.
- A great starting point for your Getinge research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Getinge. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Getinge's overall financial health at a glance.
Looking for more investment ideas beyond Getinge?
If the Getinge story has sharpened your thinking about quality, balance sheets and earnings power, use that same lens to scout for other candidates in the Simply Wall St Screener.
- For investors who want potential upside without paying up for it, start with companies that screen as attractively priced on quality metrics through the 194 high quality undervalued stocks.
- If capital protection and steady compounding matter most to you, focus on resilient businesses with healthier risk profiles using the 221 resilient stocks with low risk scores.
- When you want strong financial footing to be non negotiable, filter for companies with robust balance sheets and fundamentals by running the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com