


EN
Wharf (Holdings) (SEHK:4) Shifts Toward Commercial Assets, Is 29% Undervalued Enough?
Why Wharf (Holdings) Is Back In Focus
Wharf (Holdings) (SEHK:4) has moved the spotlight back to its mainland China portfolio after management indicated a shift away from new residential projects toward commercial and hospitality assets.
Recent trading has picked up, with Wharf (Holdings) posting a 2.7% 1 day share price return and a 2.3% 3 month share price return, even though the year to date share price return is down 11.3%. Total shareholder return tells a softer story, with a 1 year decline of 1.5% but a 3 year gain of 4.3%, which suggests that longer holding periods have been less affected by recent volatility.
Scan list of solid balance sheet and fundamentals (207 results) to find other Hong Kong and China focused property players where recurring income and balance sheet strength are already front and center.
Wharf (Holdings) has just moved, yet analyst targets and intrinsic value estimates still point in different directions. Where does a fair price really sit in that spread between HK$19.81 and the valuation ranges on offer?
Most Popular Narrative: 29% Undervalued
Wharf (Holdings) closed at HK$19.81 while the most followed narrative pegs fair value at HK$27.82, using an 8.86% discount rate to weigh future cash flows back to today.
The move into a net cash position of HK$4.5 billion by end 2025 and HK$8.6 billion by mid 2026, funded through HK$12.9 billion of listed equity disposals, gives Wharf (Holdings) capacity to redeploy capital into new income producing assets that could support future revenue and net interest savings.
See why 1 investors see Wharf (Holdings) as 29% undervalued.
Result: Fair Value of HK$27.82 (UNDERVALUED)
Still, the sharp 91% fall in interim profit and recurring Mainland impairments show how easily Wharf (Holdings) earnings assumptions could be knocked off course.
Find out about the key risks to this Wharf (Holdings) narrative.
Another View: Wharf (Holdings) Looks Expensive On Sales
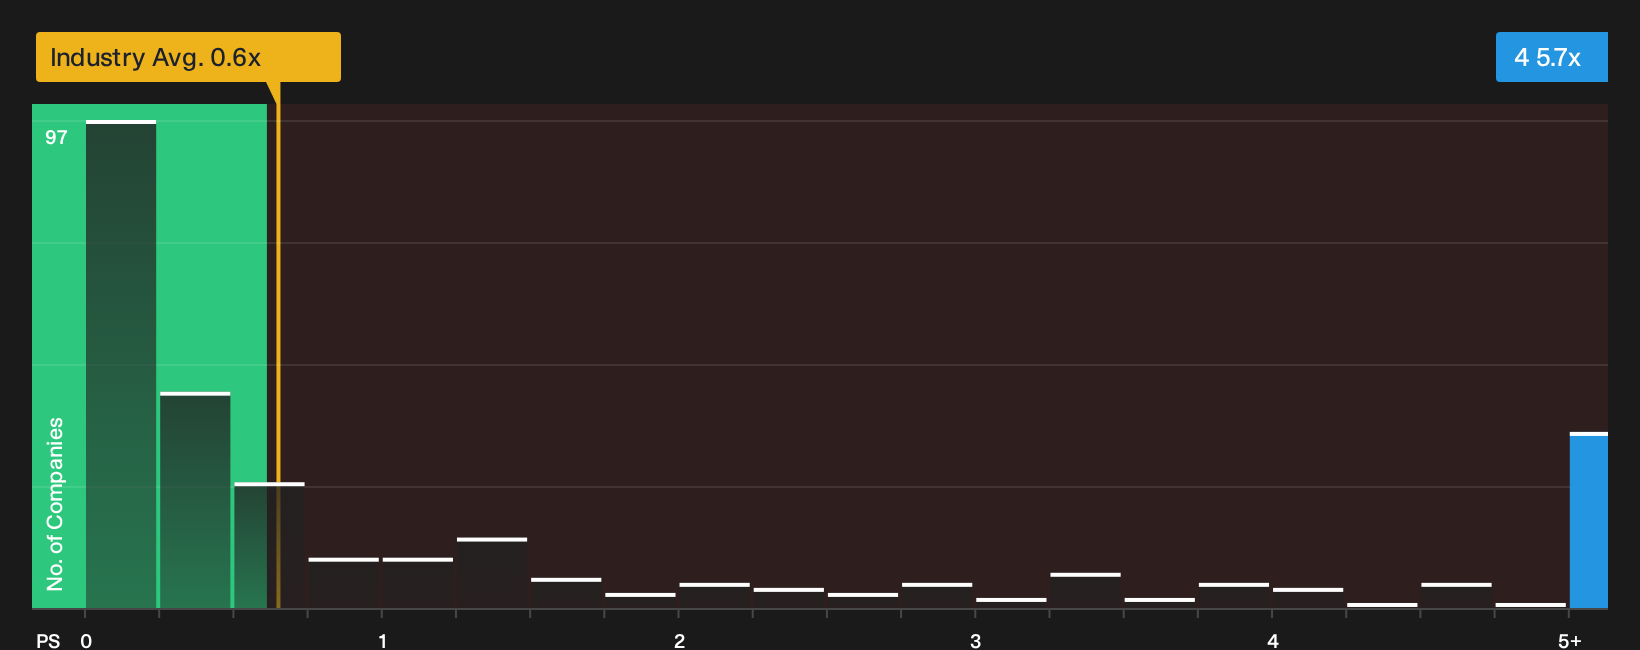
The bullish fair value of HK$27.82 leans heavily on future earnings power. On a simple sales yardstick, Wharf (Holdings) trades on a P/S of 5.7x, while peers around Hong Kong average 3.2x and the fair ratio sits at 3.7x. That gap points to richer expectations rather than a clear discount. Which story do you trust more right now?
Our valuation work based on this sales multiple goes deeper into how that premium stacks up against both the broader Hong Kong real estate group and closer peers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Wharf (Holdings) leave you on the fence, treat that as your cue to move fast and test the numbers yourself. To see what optimism is built into those positives, start with the 1 key reward.
Looking for more Wharf (Holdings) investment ideas?
If Wharf (Holdings) leaves you undecided, you could broaden your watchlist with a few focused stock ideas built from clear balance sheet, yield, and valuation filters.
- Target resilient balance sheets and dependable fundamentals by scanning the list of solid balance sheet and fundamentals (207 results) to find financially grounded businesses.
- Look for potential mispricing by reviewing the 194 high quality undervalued stocks that highlights companies trading below their assessed worth on key fundamentals.
- Build an income focused watchlist by checking the 229 dividend fortresses featuring higher yielding businesses with a focus on distribution strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com