


EN
How Investors May Respond To SpaceX (SPCX) Wireless Carrier Push
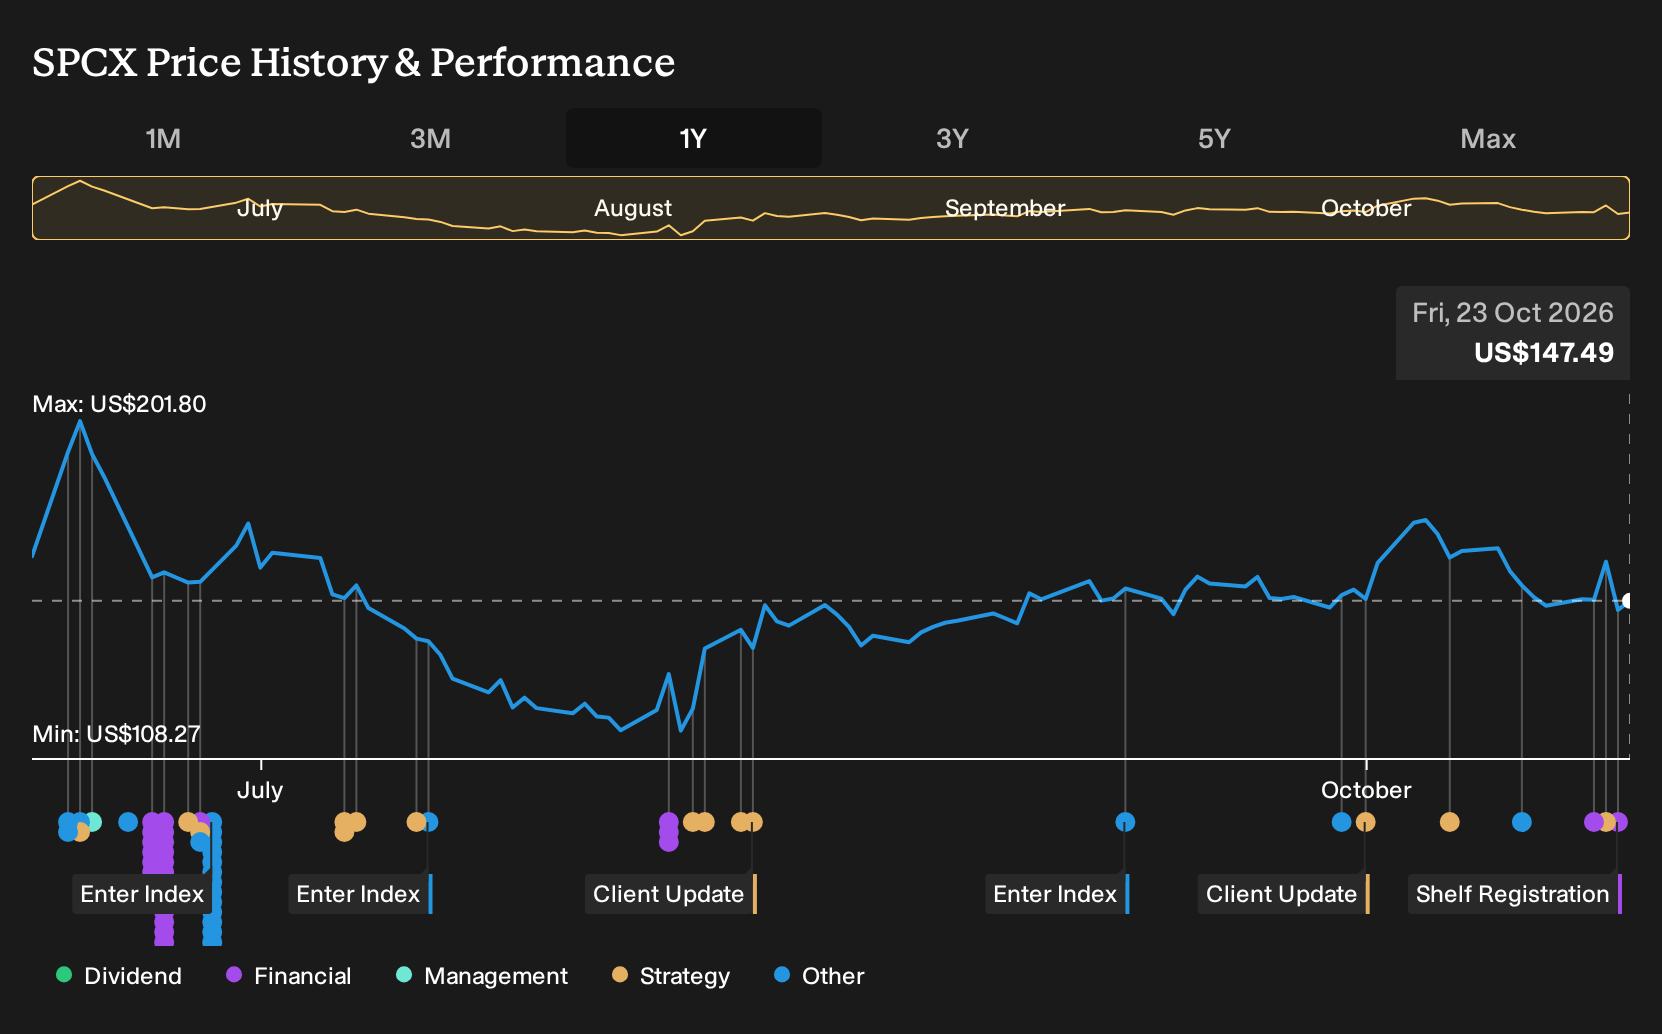
- Space Exploration Technologies filed a US$3.42b shelf registration for 23,637,224 Class A shares and reported Q3 2026 sales of US$14.58b with US$4.40b in net income, while advancing plans to secure about 80,000 U.S. cell sites for Starlink Mobile and broader wireless coverage.
- The combination of first time quarterly profitability, heavy planned capital spending on AI compute and connectivity, and an ambitious push to become a fourth nationwide carrier signals that SpaceX is stretching its balance sheet and execution capacity across launch, broadband and mobile telecom at the same time.
- Attention now turns to how SpaceX's push into 80,000 U.S. cell sites could reshape the existing investment narrative around Starlink and AI.
Space Exploration Technologies Investment Narrative Recap
To own Space Exploration Technologies stock, you need to believe this business can scale three heavy projects at once: launch, Starlink connectivity and Super Intelligence AI all need to move from capital hungry build out to self funding engines. Q3’s US$14.58b in sales and US$4.40b net income show that, at least for now, the model can throw off cash.
The short term swing factor is whether Starlink and AI utilization stay high enough to support planned spending on compute, rockets and satellites. The biggest risk is that capex and debt accelerate faster than demand, especially as SpaceX seeks to add around 80,000 cell sites for a new wireless carrier push.
The fresh US$3.42b shelf registration for 23,637,224 Class A shares matters most in that context. Space Exploration Technologies is signaling it wants more financial flexibility while committing to AI infrastructure, Starship scale up and a Starlink Mobile rollout that requires ground leases, spectrum and additional satellites.
If this equity capacity is tapped, existing holders could face dilution, while the firm would also reduce its reliance on higher risk borrowing at a time when it has less than one year of cash runway. For investors tracking catalysts, the key question is whether new capital translates into usable Starlink and AI capacity faster than it erodes per share economics.
Space Exploration Technologies is framed around revenues of US$251.8b and earnings of US$80.1b by 2029, which sits on analyst assumptions of about 121.9% yearly revenue expansion and a shift from an earnings loss of US$8.9b today to that future earnings figure. This represents an increase of roughly US$89b over the period.
Uncover how Space Exploration Technologies' fair value indicates a 51% potential difference from its current price before the market closes that gap.
Exploring Other Perspectives
Some of the most optimistic analysts lean on the Tesla and SpaceX merger story instead of funding risk. Before this shelf registration, the bullish camp was modeling revenue of about US$409.6b and earnings of roughly US$142.8b by 2029, with a US$337.83 target price. You can treat that as one extreme and compare it with your own expectations as this equity move and the merger talks evolve.
Explore 22 other Space Exploration Technologies fair value estimates, including one that suggests up to 256% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own informed view.
- A great starting point for your Space Exploration Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Space Exploration Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Space Exploration Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Space Exploration Technologies?
If the Space Exploration Technologies story has you thinking more broadly about where to put fresh capital, it can help to widen the lens and compare it with other businesses that match your preferred style, whether that is balance sheet strength, income potential, or overlooked opportunities.
- If capital preservation matters most, start with a curated group of companies that our filters score as more resilient by checking out 30 resilient stocks with low risk scores.
- For investors focused on quality at a reasonable entry point, review a hand picked set of stocks trading below internal fair value estimates through 29 high quality undervalued stocks.
- If you prefer to hunt for under the radar opportunities before the crowd catches on, scan a focused 21 high quality undiscovered gems and see which businesses fit your checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com