


EN
Is Pulse Biosciences (PLSE) Fully Priced As Clayman Partnership Builds Commercial And Clinical Traction?
Why the Clayman Thyroid Center partnership matters for Pulse Biosciences
Pulse Biosciences (PLSE) is drawing attention after partnering with the Clayman Thyroid Center in Tampa, a deal that combines commercial use of its Vybrance System with fresh clinical data generation.
The Clayman Thyroid Center is now offering nPulse Vybrance treatment for symptomatic benign thyroid nodules as part of Pulse Biosciences’ controlled market development plan. Both parties are collecting real world outcomes and running formal studies on nsPFA energy.
Recent trading reflects that interest. At a share price of $53.02, Pulse Biosciences has a 7 day share price return of 19.33% and a 90 day share price return of 61.70%, while the 1 year total shareholder return of 193.33% and 3 year total shareholder return above 10x hint at strong momentum backing news such as the Clayman Thyroid Center partnership.
Scan 34 healthcare AI stocks that, like Pulse Biosciences, are tying real patient use to fresh clinical data and turning medical technology headlines into tradable stories.
Pulse Biosciences now has a promising thyroid franchise, a headline partnership and a share price near US$53. The harder question is whether that recent surge already bakes in the opportunity or still leaves room in the valuation.
Most Popular Narrative: 15% Undervalued
Analysts tracking Pulse Biosciences peg fair value around $62.33 per share, compared with the recent $53.02 close. This puts the current Clayman driven excitement in the context of a still sizable gap to that narrative estimate.
Early commercial traction of the nPulse Vybrance system in benign thyroid nodule ablation, supported by growing procedure volumes and positive physician feedback, positions the company to convert existing thyroidectomy volume and unlock a large base of watchful waiting patients, which should accelerate revenue growth and increase recurring disposable sales.
See why 2 investors see Pulse Biosciences as 15% undervalued.
That storyline leans on a model where revenue growth assumptions are very large. A net loss of $80.06 million today is expected to flip to $4.8 million of earnings by around 2029, and a discount rate of 7.51% is used to pull those future figures back into today’s dollars.
Analysts backing this fair value also accept an implied P/E multiple on those future earnings that runs into four digits, far above the 24.7x referenced for the broader US Medical Equipment industry in the narrative. This signals how much success needs to be reflected in the numbers over time to support that outcome.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, Pulse Biosciences carries real execution risk, from very high operating losses against minimal revenue to pivotal trial outcomes that could reset analyst expectations overnight.
Find out about the key risks to this Pulse Biosciences narrative.
Another View: What Pulse Biosciences’ multiples are signalling
The first narrative leans on a story of future earnings catching up with Pulse Biosciences’ share price. A simple check on today’s pricing tells a very different story.
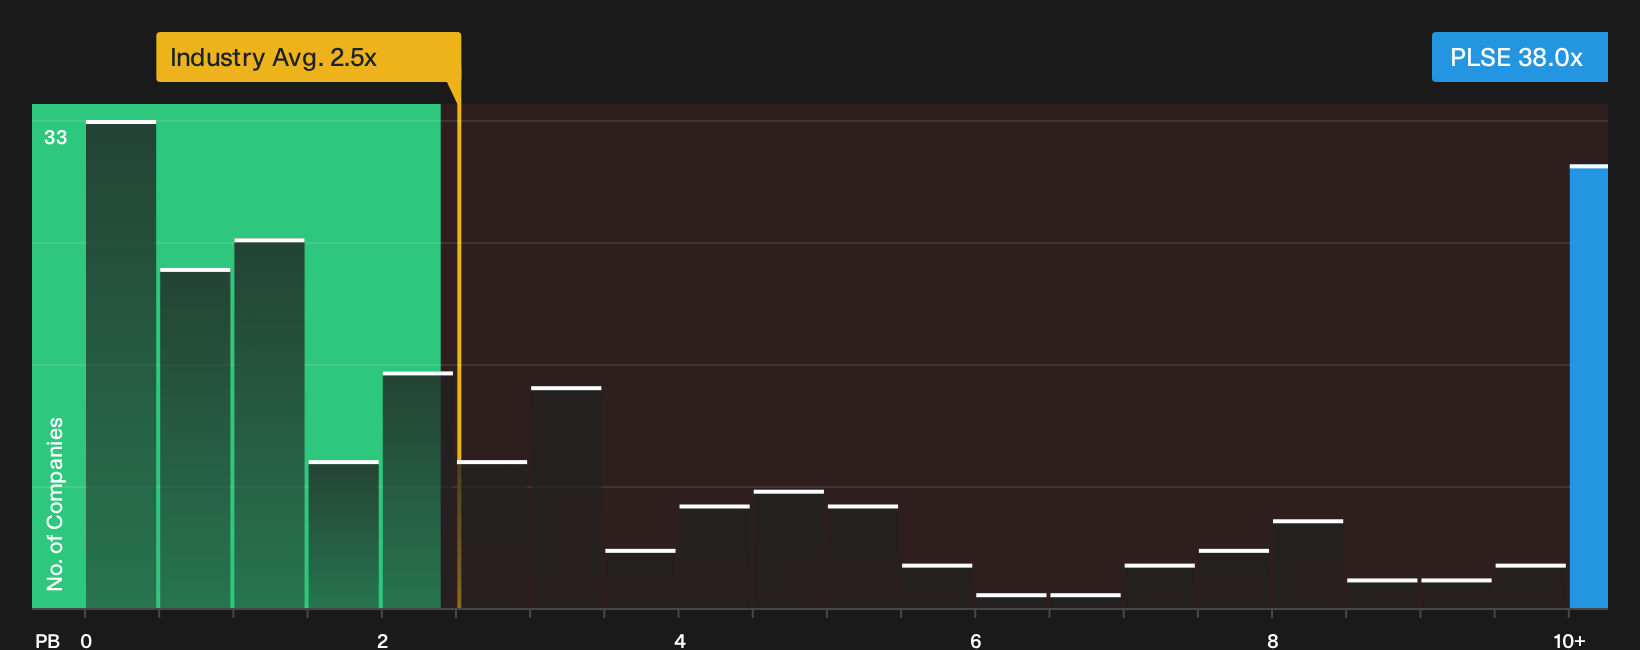
On book value, the stock trades at a P/B of 38x. The wider US Medical Equipment group sits closer to 2.5x and Pulse Biosciences’ direct peer set averages about 8.3x. That gap suggests investors are already paying a steep premium for future success, which raises a practical question for you as a shareholder or potential buyer: How comfortable are you paying many times the sector and peer valuation while the business still has only $1.2m of revenue and is loss making?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between the upbeat Clayman story and the hefty valuation signals around Pulse Biosciences is reasonable, so move quickly, review the underlying data, and weigh both the upside and the execution questions through 1 key reward and 2 important warning signs.
Looking for more Pulse Biosciences style investment ideas?
If Pulse Biosciences has your attention, do not stop here. Use curated screeners to quickly spot fresh candidates before they move away from attractive territory.
- Target steadier opportunities first by reviewing a 30 resilient stocks with low risk scores that aims to keep potential downside in sharper focus.
- Hunt for mispriced quality by scanning a 29 high quality undervalued stocks built to surface strong fundamentals at comparatively modest valuations.
- Broaden your watchlist with a 21 high quality undiscovered gems that highlights lesser known businesses with solid financial traits before they attract wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com