


EN
Is Element Solutions (ESI) Undervalued After Record Q3 Results And Higher EBITDA Guidance?
Element Solutions (ESI) grabbed investor attention after reporting third quarter 2026 earnings, with sales of US$995.3 million and net income of US$65.7 million. The company also raised its full year EBITDA guidance and reported improved margins.
Element Solutions shares trade at US$33.21, with the stock giving up ground over the past month and quarter even after record Q3 results and raised EBITDA guidance. The 1-year total shareholder return of 28.1% and 3-year total shareholder return of 91.2% signal that longer term momentum remains intact, while the recent 7-day and 30-day share price declines suggest investors are reassessing growth durability and spending risks in light of questions around AI demand and ongoing capital projects.
Scan how Element Solutions compares to other materials and electronics plays by reviewing a curated group of 29 high quality undervalued stocks with solid cash generation and balance sheets.
So are recent losses in Element Solutions simply sentiment cooling after an AI driven rush, or a real signal that earnings power and cash returns are being overestimated as the current share price is weighed against fundamentals?
Most Popular Narrative: 28.5% Undervalued
The most followed narrative pegs Element Solutions at a fair value of $46.45, well above the recent $33.21 close, so the current disconnect turns on whether its higher value electronics tilt holds up.
The shift in Element Solutions' portfolio toward electronics end markets, with more than 70% of revenue now from electronics and roughly 75% of that sold into B2B and enterprise customers, reduces reliance on mobile devices at about 5% of total revenue and can support more stable, higher value revenue and margin mix over time.
See why 3 investors see Element Solutions as 29% undervalued.
Result: Fair Value of $46.45 (UNDERVALUED)
Still, two pressure points could crack the bullish Element Solutions story: sustained cost inflation that outpaces pricing, and any sharp cooling in AI and data center spending.
Find out about the key risks to this Element Solutions narrative.
Another View: Element Solutions Looks Expensive On Earnings
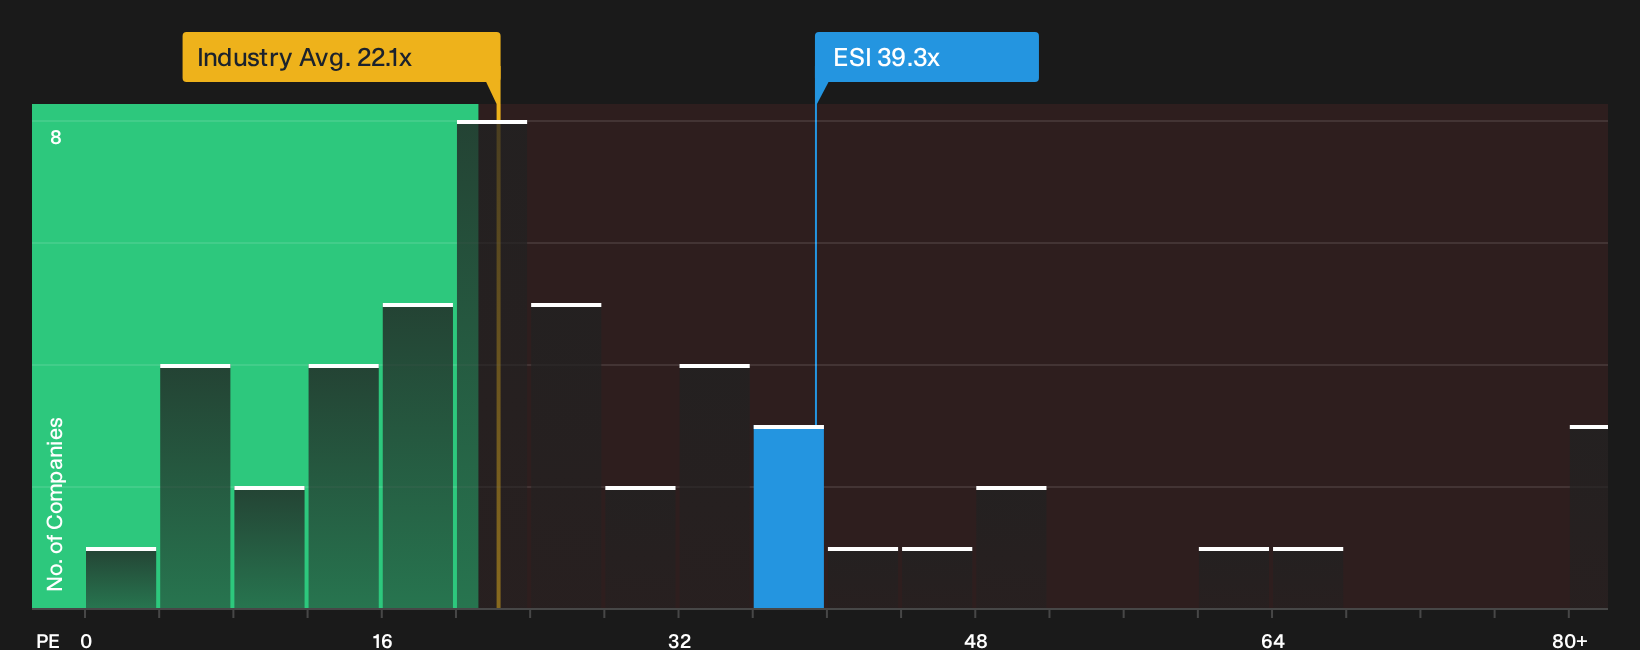
On a simple earnings lens, Element Solutions does not look cheap. The stock trades on a P/E of 39.3x, compared with 22.1x for the US Chemicals group, 25.3x for peer companies, and a fair ratio of 30.6x that the market could eventually lean toward. That gap points to real rerating risk if sentiment cools.
To see what the numbers say about this price in more depth, take a look at our valuation breakdown, which compares Element Solutions against that fair ratio and its sector peers: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed mood around Element Solutions reflects temporary noise or something deeper in the fundamentals? Move quickly, walk through the data, and weigh both sides with the help of 3 key rewards and 2 important warning signs.
Looking for more Element Solutions style ideas?
If you only stop at Element Solutions, you risk missing other stocks with strong balance sheets, resilient cash flows, and different risk profiles that could complement your portfolio.
- Target stronger downside protection by scanning a 30 resilient stocks with low risk scores that focuses on businesses with more resilient profiles and lower overall risk scores.
- Hunt for quality at a discount by reviewing a 21 high quality undiscovered gems that highlights fundamentally solid companies the broader market may be overlooking today.
- Rebuild your watchlist around financial strength by using a list of solid balance sheet and fundamentals (24 results) that filters for healthier leverage, liquidity, and core fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com