


EN
Yakult HonshaLtd (TSE:2267) Rebounds This Year, Is It Still A Bargain?
Yakult Honsha Ltd (TSE:2267) has drawn fresh attention after recent share price moves, with the stock around ¥2,826 and returns mixed over the past week, month, and past 3 months.
Set against its longer record, Yakult HonshaLtd’s modest 1-day share price gain of 0.28% and recent softness over the past week contrast with a stronger year-to-date share price return of 15.21%, while the 3-year total shareholder return is down 14.75%. This hints that recent momentum is rebuilding after a weaker medium-term stretch.
Scan how Yakult HonshaLtd compares with other consumer names showing rebuilding momentum and solid fundamentals using the hand picked 72 high quality undiscovered gems.
Yakult HonshaLtd has rebounded this year after a tougher three year stretch, which leaves you weighing a fresh entry at around ¥2,826 against the option of waiting for a cheaper pullback. So what does the current valuation actually say?
Most Popular Narrative: 16.9% Undervalued
Yakult HonshaLtd’s most followed narrative puts fair value at ¥3,400, compared with the latest close around ¥2,826. This frames the recent rebound as still leaving a valuation gap if those assumptions hold.
The shutdown of the Shanghai and Guangzhou facility, which contributed about JPY 1.8b of operating profit improvement in Asia and Oceania in the year to March 31, 2026, opens room for Yakult HonshaLtd to replicate similar footprint rationalisation in other markets and potentially build a multi year uplift in operating margins.
See why 0 investors see Yakult HonshaLtd as 17% undervalued.
Result: Fair Value of ¥3,400 (UNDERVALUED)
Still, two things could quickly challenge that 16.9% undervalued story for Yakult HonshaLtd: weaker Japan dairy volumes and further cost inflation squeezing profitability.
Find out about the key risks to this Yakult HonshaLtd narrative.
Another Look At Yakult HonshaLtd’s Valuation
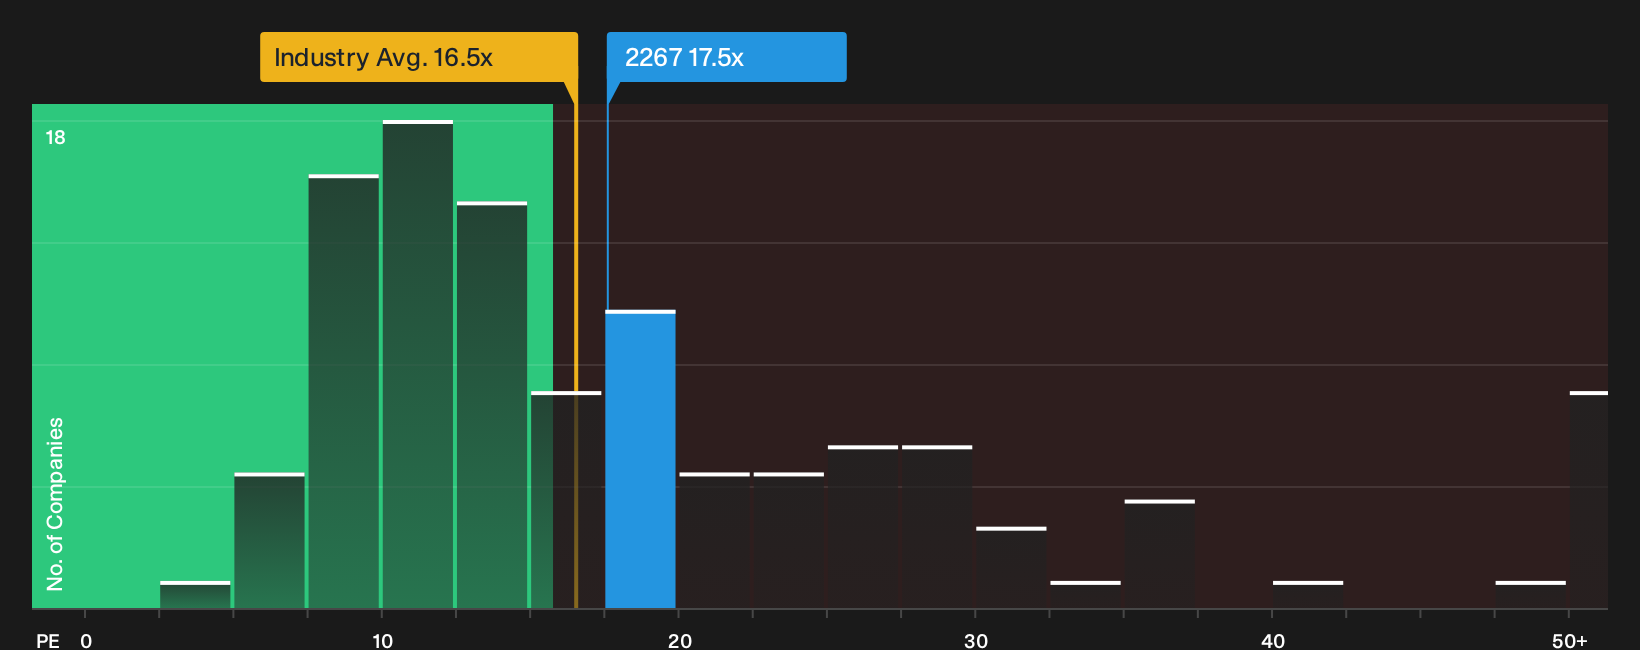
The bullish fair value of ¥3,400 paints Yakult HonshaLtd as 16.9% undervalued. The fair ratio view tells a different story. At a P/E of 17.5x versus a fair ratio of 16.2x and a JP Food sector level of 16.5x, the stock screens a bit expensive. Which signal do you trust more?
To see how that P/E gap could close in practice, and what it might imply for future pricing power and downside risk, it helps to walk through the full valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Yakult HonshaLtd’s story so far. Consider the situation while sentiment is still split and pressure test the upside and downside yourself with 1 key reward and 3 important warning signs.
Looking for more Yakult HonshaLtd style investment ideas?
Do not stop with Yakult HonshaLtd. Broaden your watchlist now and give yourself more options by scanning other stocks filtered for quality, value, and resilience.
- Target resilient balance sheets and steady fundamentals using a curated list of solid balance sheet and fundamentals (23 results) that keeps weaker financials off your radar.
- Zero in on mispriced opportunities by running a focused search through the 14 high quality undervalued stocks before prices move away from you.
- Aim for steadier rides in rough markets with a filter built around 22 resilient stocks with low risk scores so you are not scrambling after the fact.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com