


EN
Asian Value Stocks Priced Below Intrinsic Estimates October 2026
As of October 2026, Asian markets have been navigating through a landscape marked by rising oil prices and concerns over AI investment, contributing to volatility across various sectors. In this environment, investors are increasingly looking for value opportunities in stocks that are priced below their intrinsic estimates. Identifying such undervalued stocks requires a focus on solid fundamentals and potential for growth amid current market conditions.
Top 10 Undervalued Stocks Based On Cash Flows In Asia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Wus Printed Circuit (Kunshan) (SZSE:002463) | CN¥107.06 | CN¥210.84 | 49.2% |
| Thai Credit Bank (SET:CREDIT) | THB22.90 | THB45.74 | 49.9% |
| Smartsens Technology (Shanghai) (SHSE:688213) | CN¥110.16 | CN¥216.15 | 49% |
| P.S.P. Specialties (SET:PSP) | THB7.40 | THB14.65 | 49.5% |
| P&H Tech (KOSDAQ:A239890) | ₩3135.00 | ₩6206.43 | 49.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1483.00 | ¥2915.30 | 49.1% |
| Nissei ASB Machine (TSE:6284) | ¥8030.00 | ¥15788.69 | 49.1% |
| Morinaga Milk Industry (TSE:2264) | ¥1083.00 | ¥2134.38 | 49.3% |
| KB Financial Group (KOSE:A105560) | ₩153000.00 | ₩304946.07 | 49.8% |
| Ichikoh Industries (TSE:7244) | ¥532.00 | ¥1057.60 | 49.7% |
Let's take a closer look at a couple of our picks from the screened companies.
Samsung E&A (KOSE:A028050)
Overview: Samsung E&A Co., Ltd. offers engineering services for plant and construction projects globally, with a market cap of ₩11.72 trillion.
Operations: Samsung E&A Co., Ltd. generates revenue through its engineering services for plant and construction projects across various regions, including South Korea, the United States, Asia, and the Middle East.
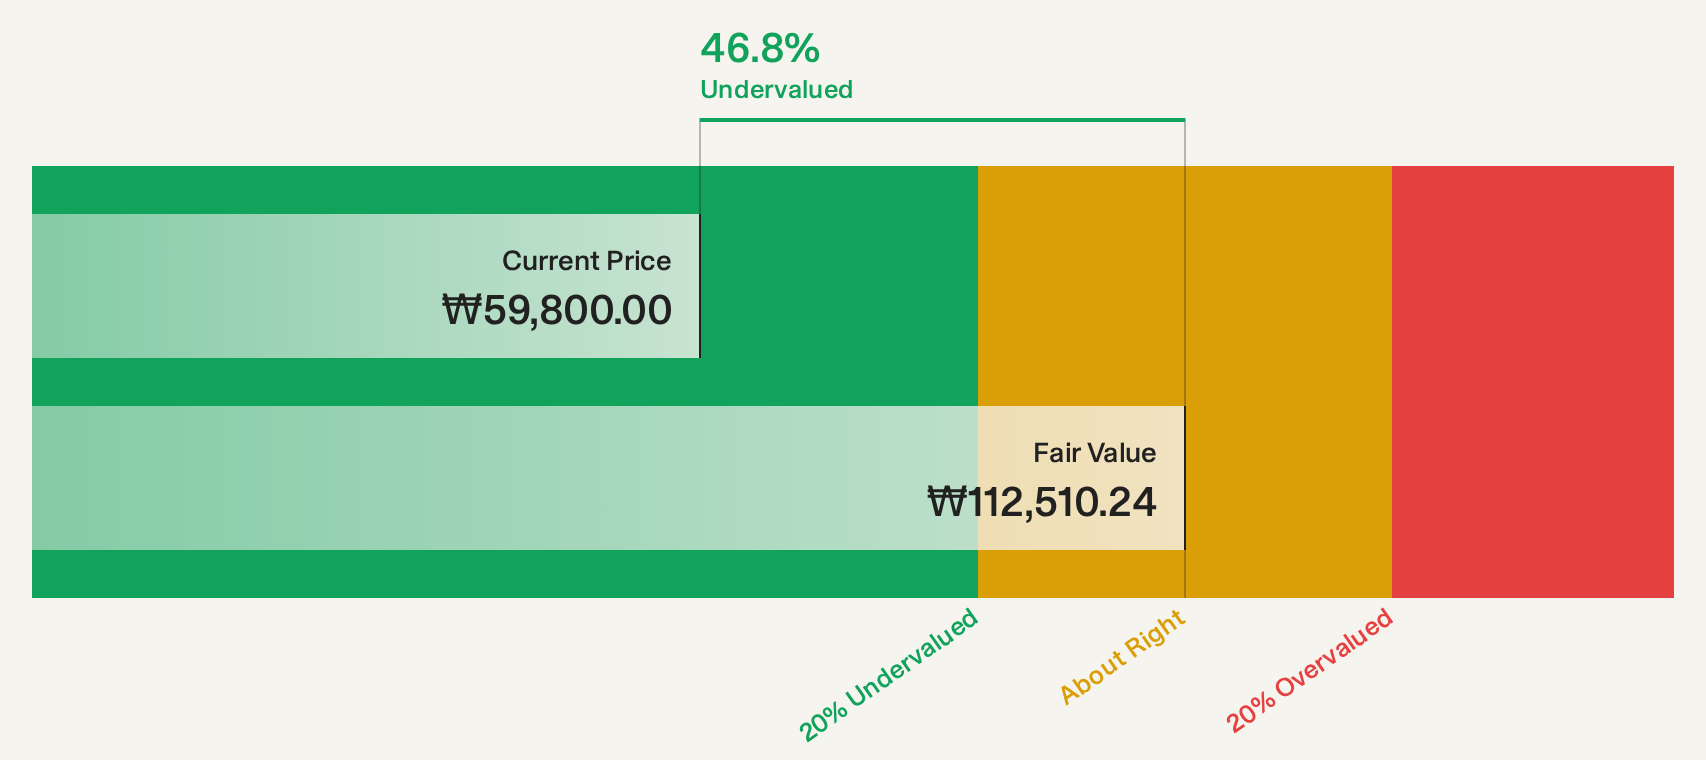
Estimated Discount To Fair Value: 46.9%
Samsung E&A is trading at a significant discount, 46.9% below its estimated fair value, and is undervalued based on discounted cash flow analysis with a share price of ₩59,800 against a future cash flow value estimate of ₩112,513.29. Despite slower expected revenue growth (18.3% annually) compared to market earnings growth (28.1%), the company's recent buyback announcement aims to enhance shareholder value amidst consistent profit growth and strong project acquisitions like the US$3.47 billion EPC contract with SABIC Agri-Nutrients Company.
- In light of our recent growth report, it seems possible that Samsung E&A's financial performance will exceed current levels.
- Take a closer look at Samsung E&A's balance sheet health here in our report.
Shenzhen Kedali Industry (SZSE:002850)
Overview: Shenzhen Kedali Industry Co., Ltd. specializes in the research, development, manufacture, and sale of precision battery and automotive structural components both in China and internationally, with a market cap of CN¥44.56 billion.
Operations: The company generates revenue through the production and sale of precision battery structural components and automotive structural component parts, serving both domestic and international markets.
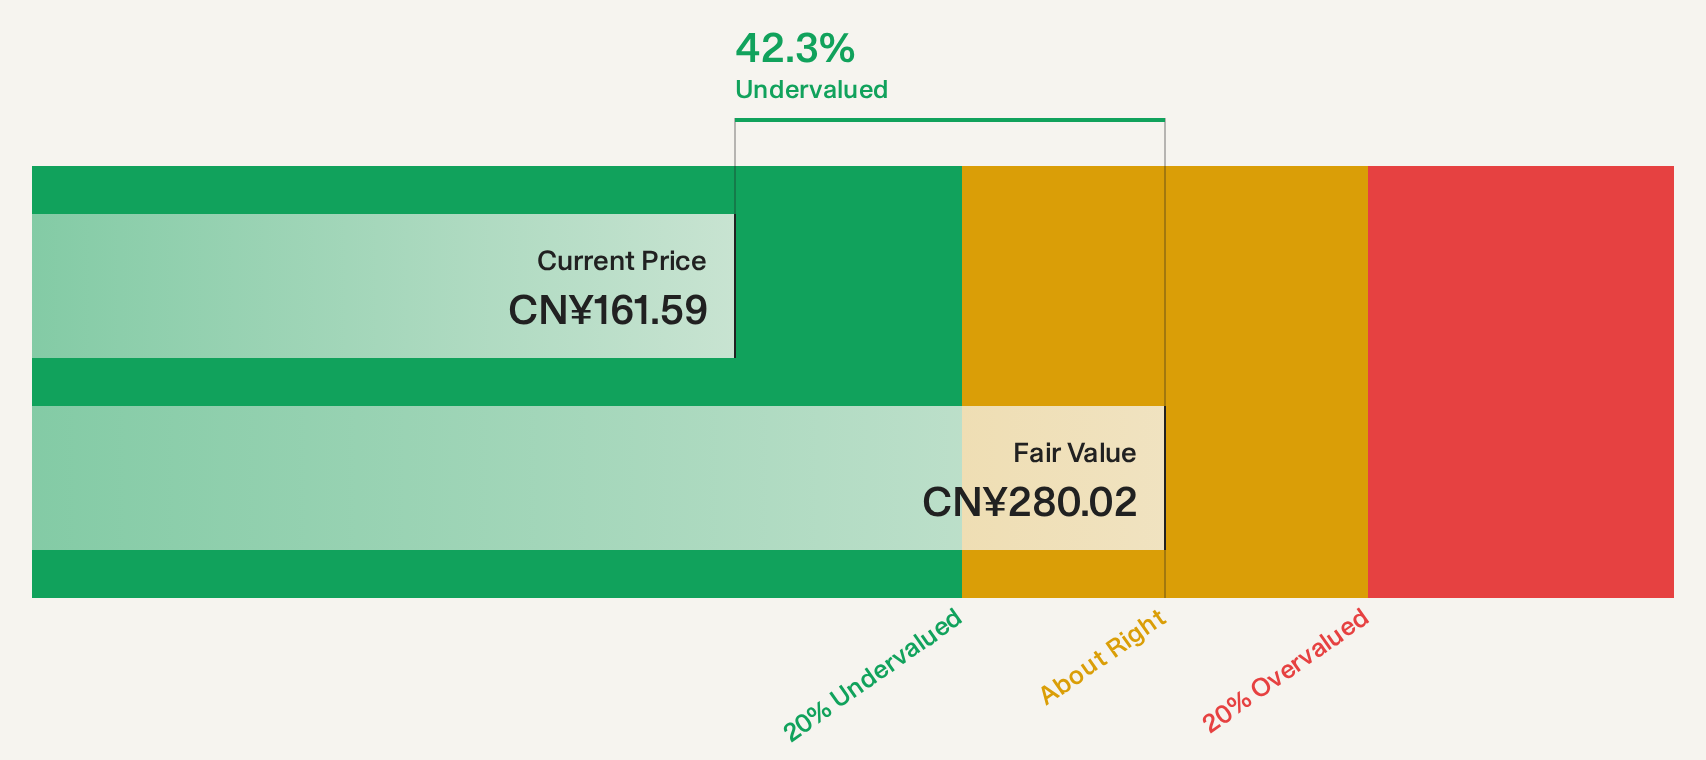
Estimated Discount To Fair Value: 44.8%
Shenzhen Kedali Industry is trading at a substantial discount, 44.8% below its estimated fair value, with a current share price of CN¥155.59 against a future cash flow value estimate of CN¥282. Despite its dividend coverage concerns, the company shows robust revenue growth (21.6% annually), outpacing the Chinese market's average. Recent earnings reports highlight increased sales and net income year-over-year, while ongoing share buybacks aim to enhance shareholder value amidst significant profit growth forecasts.
- According our earnings growth report, there's an indication that Shenzhen Kedali Industry might be ready to expand.
- Navigate through the intricacies of Shenzhen Kedali Industry with our comprehensive financial health report here.
Anker Innovations Technology (SZSE:300866)
Overview: Anker Innovations Technology Co., Ltd. designs, manufactures, and sells consumer electronics with a market cap of CN¥66.27 billion.
Operations: The company's revenue segments include Smart Innovation Products at CN¥9.21 billion, Rechargeable Energy Storage at CN¥17.52 billion, and Smart Audio and Video Products at CN¥7.52 billion.
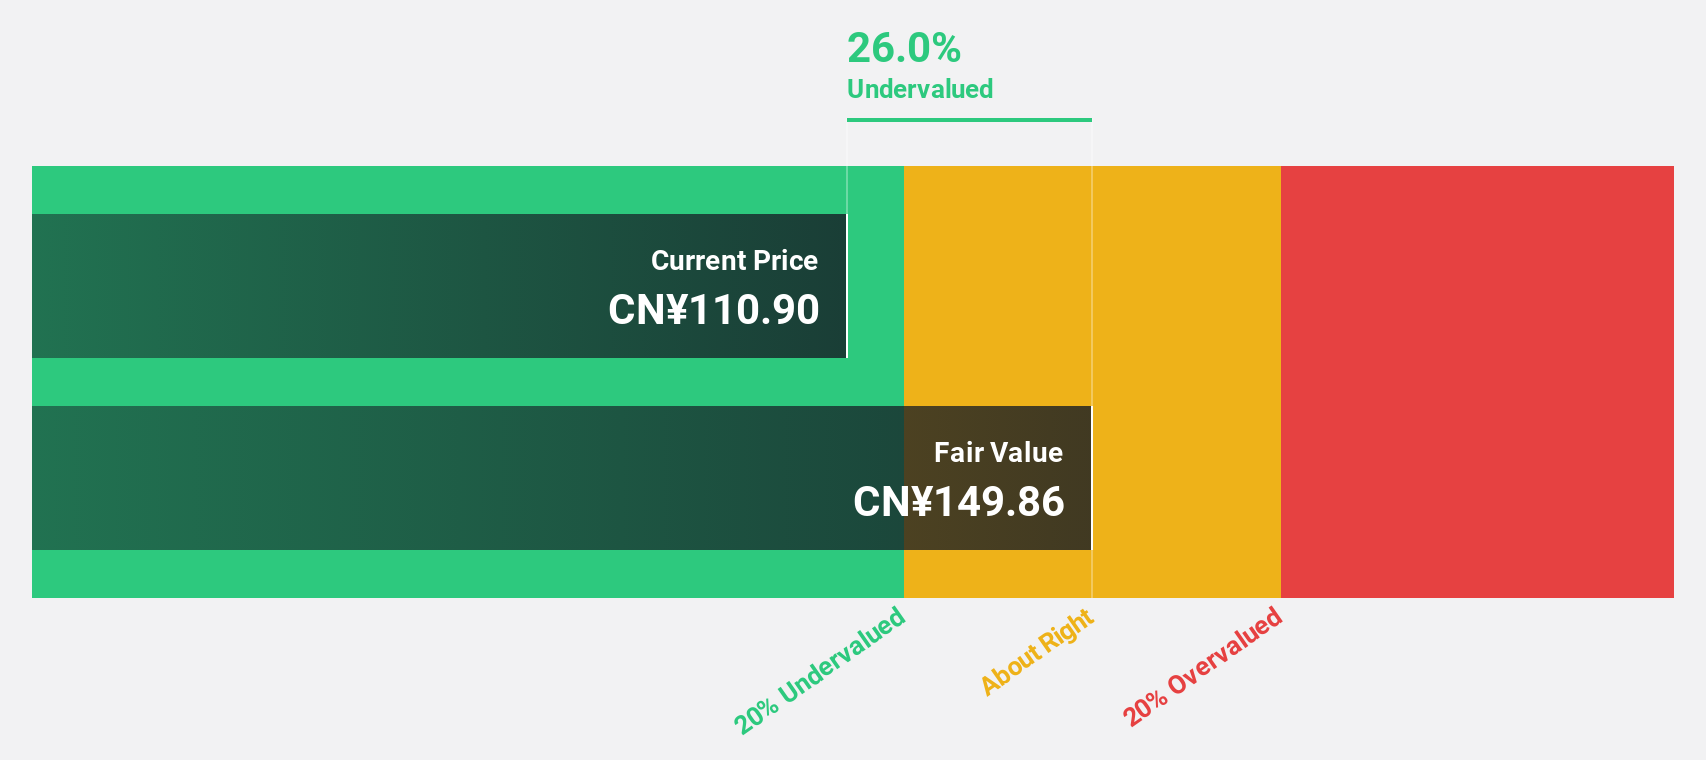
Estimated Discount To Fair Value: 43.4%
Anker Innovations Technology is trading at a significant discount, 43.4% below its estimated fair value, with a current share price of CN¥114.63 against a future cash flow value estimate of CN¥202.42. Despite an unstable dividend track record, its earnings grew by 27.9% over the past year and are forecast to grow annually by 19.88%. Recent business expansions and product launches aim to bolster revenue growth above the market average in China.
- Our earnings growth report unveils the potential for significant increases in Anker Innovations Technology's future results.
- Click here to discover the nuances of Anker Innovations Technology with our detailed financial health report.
Taking Advantage
- Take a closer look at our Undervalued Asian Stocks Based On Cash Flows list of 183 companies by clicking here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com