


EN
Australian Stock Market Today: ASX Futures Ease On Sticky US Inflation Expectations
The Morning Bull - Australian Market Morning Update Sunday, 25 Oct 2026
Australian shares are poised to open softer, with SPI 200 futures down, as one factor dominates the mood. Fresh US inflation expectations are steering global rate thinking and setting the tone for risk assets locally.
Year-ahead US inflation expectations sit at 4.7%, with the five-year outlook at 3.5% on the latest Michigan survey. Those readings keep the focus on sticky price pressure and feed the idea that global policy rates may need to stay restrictive.
When investors price in firmer inflation expectations, funding costs tend to stay higher for longer. That pressures interest-sensitive areas through more expensive borrowing and can weigh on valuation multiples where earnings are further out in the future.
The key question now is straightforward: Do resilient US activity readings, with services PMI at 57.9 and composite at 57.6, justify these inflation expectations or force a rethink once the next round of global central bank commentary arrives?
Stocks to Watch Before the Opening Bell
Yancoal Australia (YAL)
Yancoal Australia has renewed key related party coal sales framework agreements with Yankuang Energy and YIT for the period from 1 January 2027 to 31 December 2029. Annual caps are set at US$300 million for Yankuang Energy and US$900 million for YIT, with pricing tied to the McCloskey API 5 index and coal quality.
The group is also seeking shareholder approval for financial assistance linked to the Kestrel Coal Group acquisition. This involves backing A$1.5 billion and US$1.4 billion facilities with guarantees and security from the target companies. An Extraordinary General Meeting will also vote on the election of Non executive Director Ping Nie and on independent expert conclusions regarding fairness and reasonableness.
Top Movers
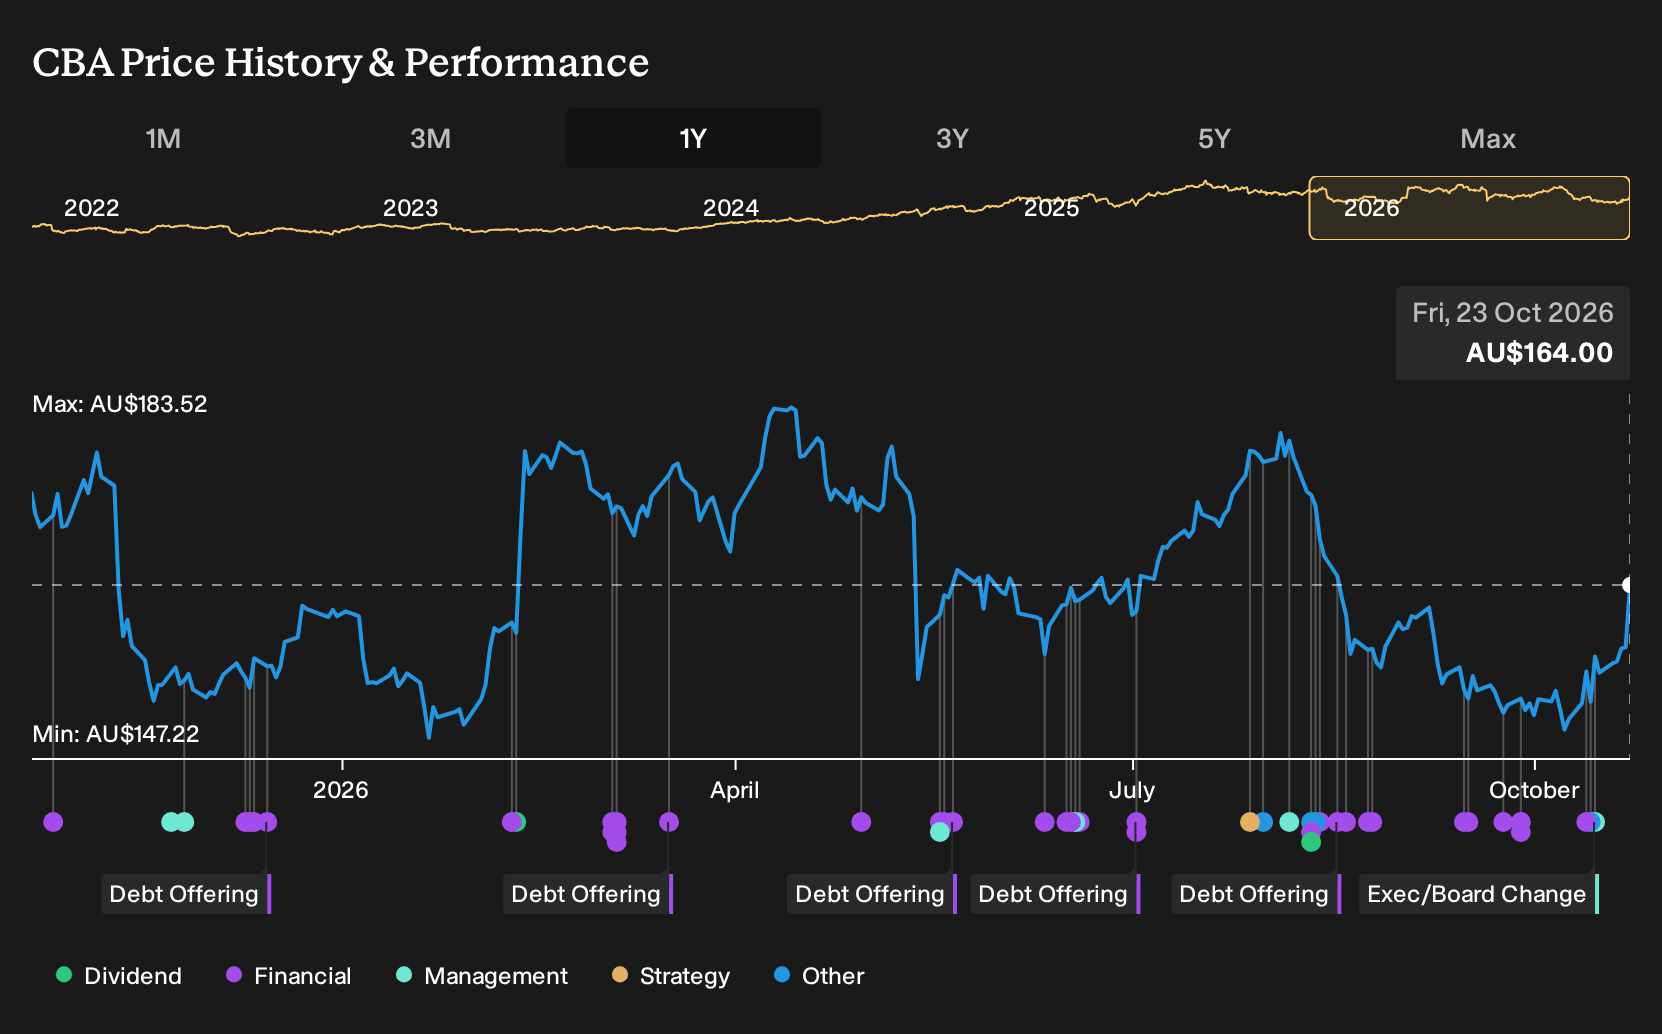
- Commonwealth Bank of Australia (ASX:CBA) jumped 4.35% after interest rate commentary kept attention on bank earnings and deposit margins.
- Objective (ASX:OCL) gained 4.29% as investors focused on the upcoming Annual General Meeting flagged for late November.
- Wesfarmers (ASX:WES) climbed 3.76% with consumer discretionary stocks firming even as materials names struggled during the session.
Top Losers
- Zip Co (ASX:ZIP) fell 29.47% after disclosing a US fraud incident that affected first quarter growth and bad debts.
- Ora Banda Mining (ASX:OBM) declined 16.54% following an update on Davyhurst development progress, production and an increase to its revolving credit facility.
- Brightstar Resources (ASX:BTR) declined 15.67%.

On The Radar
Australian inflation data and a busy run of local quarterly updates collide with major global central bank decisions to frame the next leg for rates, the A$, and rate sensitive stocks.
- RBA Jones Speech, Sun 25 Oct. Any fresh comments on how the bank views sticky price pressures and the global rate backdrop would shape expectations for how restrictive local policy needs to remain and how the A$ trades into month end.
- Australia CPI and Trimmed Mean CPI, Wed 28 Oct. Headline inflation with consensus at 0.7% MoM and 4.2% YoY, plus trimmed mean at 0.3% MoM and 3.6% YoY, will steer views on future RBA moves and pricing for rate exposed sectors.
- RBA Senate Appearance, Wed 28 Oct. The questioning of policymakers around inflation at 4.0% YoY previously, and the new CPI print, gives investors a clearer line of sight on how long current borrowing costs may stay in place.
- Fed Interest Rate Decision, Wed 28 Oct. A steady 4.0% funds rate in line with consensus would keep focus on the wording around 4.7% US year ahead inflation expectations and what that implies for the US dollar and A$ sensitive resource stocks.
- Origin Energy, Fri 30 Oct. Q1 2027 results will put the spotlight on revenue and any commentary on domestic energy demand and pricing, which can influence how investors think about cash generation across the Australian utilities complex.
Sector & Industry Watch
Financials and Banks: Rate debate keeps lenders centre stage
Financials have pushed higher over the past week, with Banks rising even more over 7 and 30 days while the 1 year picture is still softer. Higher for longer rate expectations keep lending margins in focus, at the same time as investors watch for signs of stress in home loans and small business customers.
If you hold the major lenders, the key local catalyst is Wednesday’s Australia CPI and trimmed mean CPI release. Those numbers feed directly into RBA expectations and can influence how investors think about future earnings and dividend capacity for the big four.
Consumer Staples: Defensives helping smooth portfolio swings
Consumer Staples have posted gains over the past week and month and are also higher year to date and over 1 year while the broader AU Market remains weaker on those longer timeframes. Supermarkets and liquor groups are still seeing relatively steady demand as households prioritise groceries and basic items even with higher housing and energy bills.
If your portfolio leans on this sector for stability, focus on how Australia’s CPI print breaks down by food and household services. Sticky price growth in essentials can support revenue in dollar terms although it also tests how far shoppers can keep absorbing higher tickets before cutting volumes or trading down.
Real Estate: Listed property edging away from the lows
Real Estate is modestly higher over the past week and 30 days, yet remains clearly down on a year to date and 1 year view. The recent stabilisation suggests some investors see value emerging, although higher borrowing costs still squeeze highly geared landlords and keep pressure on distribution outlooks.
For A REIT holders, Australia’s CPI and core CPI data on Wednesday are the key reference points. A stronger inflation pulse would keep talk of restrictive rates alive, which matters for refinancing costs and the prices investors are prepared to pay for property trusts.
Materials and Metals and Mining: Miners under pressure after sharp pullback
Materials and the related Metals and Mining group have both fallen over the past week and month, even though 1 year returns remain slightly positive. Softer recent sector performance lines up with questions around global growth and funding costs, which feed into how investors think about demand and project economics for iron ore, coal and base metals producers.
If you own resource stocks, the main domestic driver to watch is Australia’s quarterly CPI and trimmed mean CPI. A hotter read would keep rate expectations firm and can influence discount rates and appetite for capital intensive mining projects.
Tech and Semiconductors: Growth sectors still in the firing line
Tech and Semiconductors are among the weakest parts of the AU Market, with returns down heavily over the past year and further declines over 7 and 30 days. These groups tend to be very sensitive to interest rate expectations because a large share of their value is tied to profits that sit many years into the future.
If your holdings skew toward higher growth technology exposure, the upcoming Fed Interest Rate Decision on 28 October is the main external cue. Any change in how the Fed talks about inflation and policy can affect long dated bond yields, which flows quickly into how investors price future earnings for Australian Tech and chip related stocks.
Identify The Next Market Leaders
With Tech and Semiconductors still under pressure as higher rate expectations bite, it may help to balance your portfolio using this list of 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com