


EN
Trelleborg (OM:TREL B) Posts Record Q3 Margins, Does The Valuation Still Look Fair?
Trelleborg (OM:TREL B) has just paired record third quarter sales and EBITA margin with a completed share buyback. This gives investors fresh numbers on profitability, cash use, and exposure to aerospace and semiconductor demand.
Trelleborg’s share price has eased in the short term, with a 7 day share price return of down 4.13% and a 30 day return of down 3.14%. This comes even though the 90 day share price return of 6.73% and 1 year total shareholder return of 15.96% point to momentum that has built gradually over several years, highlighted by a 5 year total shareholder return of 156.16% at a latest share price of SEK450.4.
Spot similar momentum and cash generative profiles by scanning our hand-picked list of solid balance sheet and fundamentals (205 results) as a potential complement or comparison to Trelleborg.Trelleborg now combines record Q3 profitability with a briefly softer share price. Is this the moment to lean into that pullback, or does patience for a cheaper entry make more sense once valuation is unpacked next?
Most Popular Narrative: 4% Undervalued
Trelleborg’s most followed narrative values the shares at SEK467.64, slightly above the latest close of SEK450.4. This points to a modest gap between price and estimated worth using a 6.74% discount rate.
A sustained mix shift toward higher margin engineered solutions and solution selling in Sealing Solutions, with EBITA margins already around 22.5% and a stated ambition of 23% over the cycle, can underpin structurally higher group net margins and earnings.
See why 10 investors see Trelleborg as 4% undervalued.
Result: Fair Value of SEK467.64 (UNDERVALUED)
Still, the heavy exposure to weaker automotive demand and the margin drag from ongoing acquisition integration could both challenge this narrative that Trelleborg is 4% undervalued.
Find out about the key risks to this Trelleborg narrative.
Another View: Trelleborg Through The P/E Lens
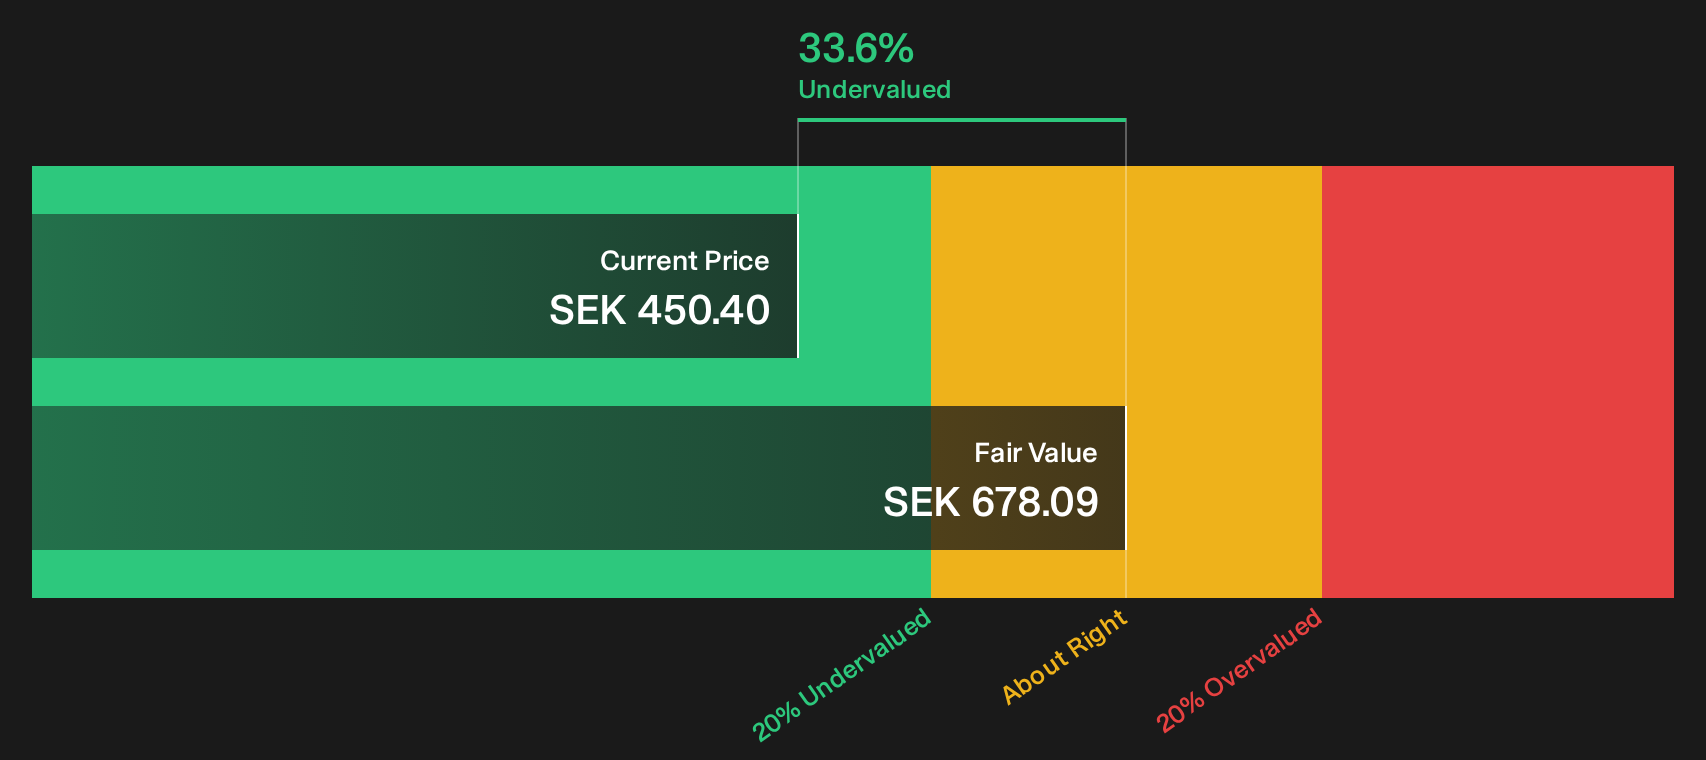
The SWS DCF model flags Trelleborg as good value, with the shares trading about 33.6% below an estimated future cash flow value of SEK678.09. The market is not forced to agree with that spreadsheet. The real question is how comfortable you are with those cash flow assumptions.
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Trelleborg’s valuation and recent share pullback can pull you in either direction. Move quickly, review the full picture, and weigh both the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Trelleborg?
If Trelleborg has sharpened your focus on quality, do not stop here. Use the Simply Wall Street Screener to line up your next set of candidates.
- Target dependable compounding by scanning companies with strong fundamentals and defensive balance sheets through the 221 resilient stocks with low risk scores.
- Hunt for mispriced quality by filtering for attractively valued businesses with good fundamentals using the 194 high quality undervalued stocks.
- Spot potential future leaders early by focusing on strong fundamentals and healthy finances with the 613 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com