


EN
NextEra Energy (NEE) On Strong Q3 And Dividend News Is The Stock Fully Valued
NextEra Energy (NEE) just paired a strong third quarter 2026 earnings update with a fresh quarterly dividend declaration, putting income and growth expectations in the spotlight for current and prospective shareholders.
The earnings beat and dividend announcement arrived after a mixed year for the NextEra Energy share price, with a 30 day share price return of 7.9% but a 90 day share price return that is still down 7.6%.
At around $82.10 per share, the recent uptick in momentum sits against a relatively flat 1 year total shareholder return of 0.1%. However, investors who stayed invested over three years have seen a 59.6% total shareholder return, suggesting the longer term story has been more rewarding than the recent quarter to quarter swings.
Spot 42 power grid technology and infrastructure stocks that, like NextEra Energy, are tied into the build out of large-scale power infrastructure supporting renewables, data centers, and long-term electricity demand trends.The recent jump in NextEra Energy puts fresh optimism on one side and the risk that most of the easy gains are already captured on the other. Which story does the current valuation support?
Most Popular Narrative: 12% Undervalued
NextEra Energy last closed at $82.10, while the most followed narrative on the stock anchors fair value closer to $93.71, so the gap between price and thesis is still meaningful for long term investors watching the merger story.
The proposed NextEra Energy and Dominion Energy merger should not be viewed as a traditional utility consolidation alone. In my opinion, the strategic value is much larger because Dominion gives NextEra direct exposure to one of the most important electricity-demand markets in the world: Northern Virginia’s data-center corridor.
See why 52 investors see NextEra Energy as 12% undervalued.
Result: Fair Value of $93.71 (UNDERVALUED)
Still, the merger story around NextEra Energy could be knocked off course if regulators push back harder than expected or if data center power demand slows materially.
Find out about the key risks to this NextEra Energy narrative.
Another View: Cash Flow Model Flips the Script
On price versus earnings, NextEra Energy looks inexpensive, with a P/E of 14.8x against an estimated fair ratio of 21.1x and higher peer and industry averages. Yet our DCF model points to a future cash flow value of $77.10, below the current $82.10 share price. This raises the question of whether investors are paying up for an earnings story that the cash flows do not fully support.
For anyone weighing those two signals side by side, the next step is understanding exactly how our cash flow assumptions compare to the earnings multiples that look appealing on the surface. Look into how the SWS DCF model arrives at its fair value.
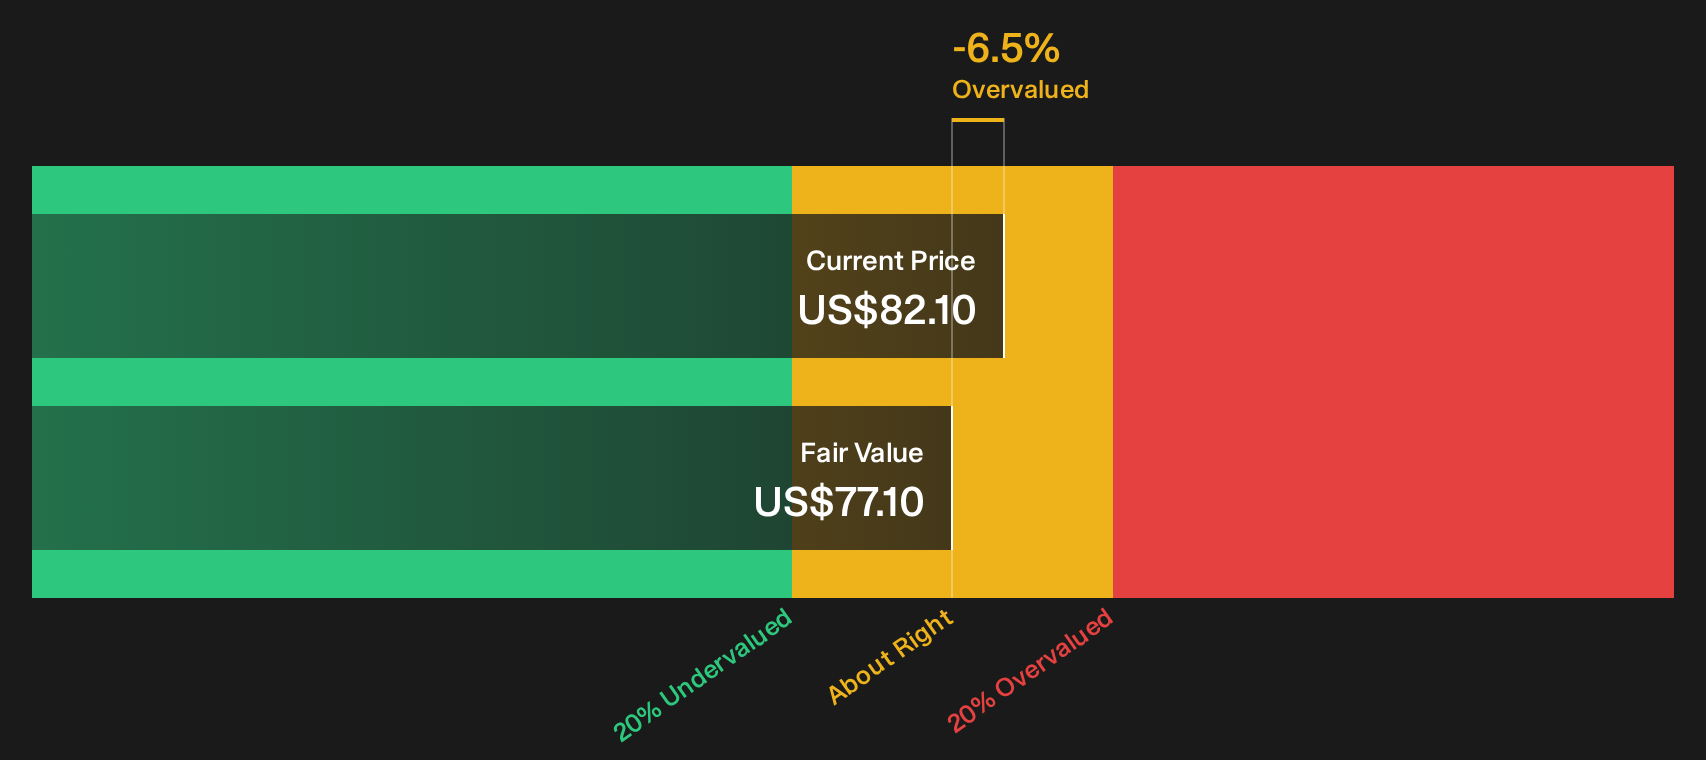
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NextEra Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on NextEra Energy after this update are completely reasonable. Move quickly, review the full picture, and weigh the potential upside against the concerns using 3 key rewards and 2 important warning signs.
Ready to act on the NextEra Energy story?
If you stop with just NextEra Energy, you risk missing other opportunities that fit your goals, risk tolerance, and income needs just as well.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (24 results). This can help anchor your portfolio when sentiment swings.
- Hunt for potential mispricings with a focused 29 high quality undervalued stocks that highlights companies where fundamentals and share prices are out of sync.
- Strengthen your income stream by reviewing a curated 5 dividend fortresses that aims to combine higher yields with robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com