


EN
Starbucks (SBUX) Has Investors Asking A Bigger Question
Starbucks (SBUX) just laid out a fresh store plan with 600 to 650 net new coffeehouses, about 1% of North American locations set to close, and updated guidance plus a higher dividend.
Recent announcements on store openings, closures and a higher dividend come after a mixed stretch for Starbucks, with the share price up 20.0% year to date, slightly down over the past three months and a 1-year total shareholder return of 20.1%.
Scan how Starbucks compares with other consumer names featuring accelerating storylines by reviewing our curated list of 21 high quality undiscovered gems, along with this latest store and dividend reset.
Starbucks now trades close to its average intrinsic value estimates, yet still sits below the consensus analyst target. That gap is narrow, not huge. Does it point to limited upside or to mispriced resilience in the new plan?
Most Popular Narrative: 10.2% Undervalued
Starbucks closed at $100.80 against a widely followed fair value estimate of $112.23. As a result, the current plan is being judged against an implied upside that is not extreme but still meaningful.
The Back to Starbucks plan, including Green Apron Service, standardized store scorecards, and a $2b cost-savings program through fiscal 2028, is still in progress and is expected to continue affecting operating margins and earnings as more of the targeted savings and process changes flow through the P&L.
See why 230 investors see Starbucks as 10% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, the Starbucks narrative could be knocked off course if unionisation pressures keep labor costs high or if global operating margins remain below prior levels.
Find out about the key risks to this Starbucks narrative.
Another View: Starbucks On Rich Multiples
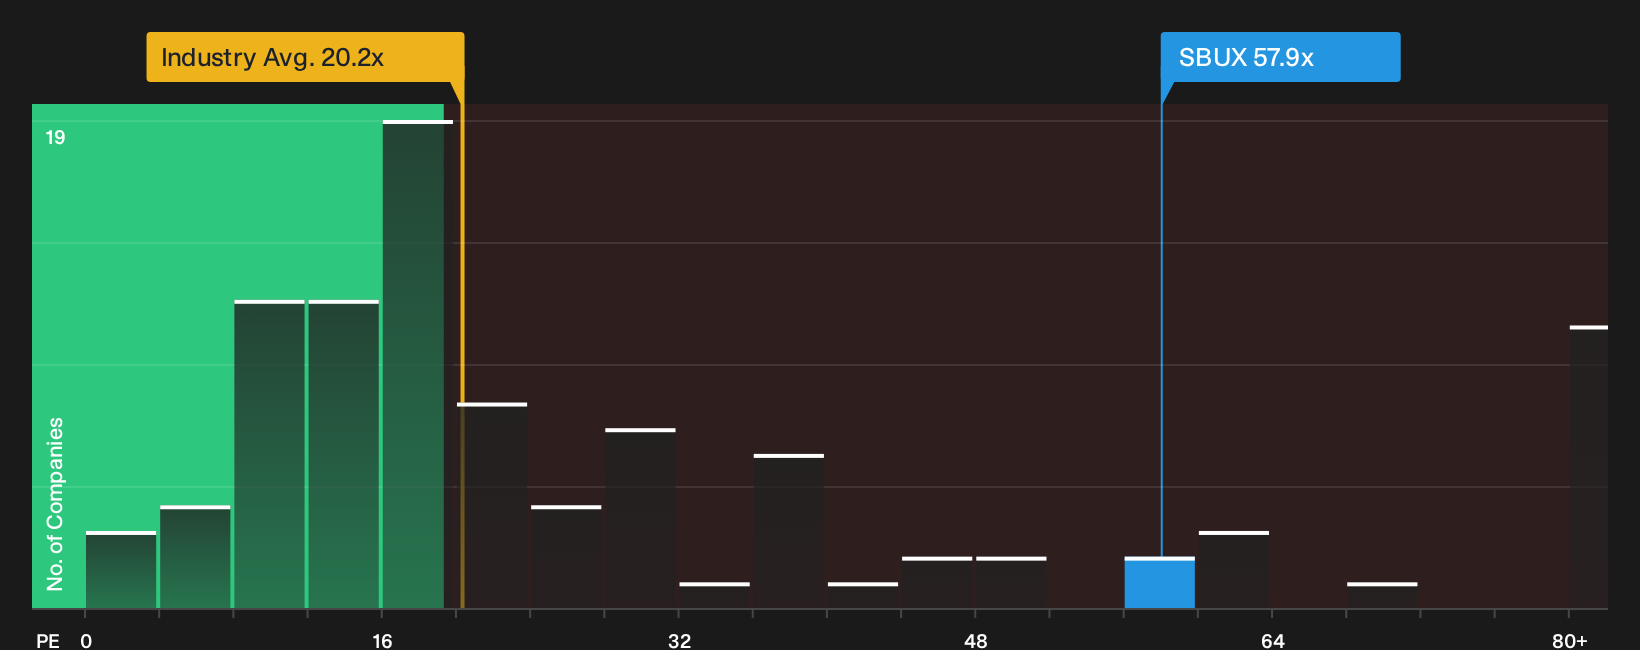
On the story and fair value work, Starbucks screens around 10% undervalued. On simple P/E math it looks far less generous, trading on 57.9x earnings compared with a fair ratio of 32.7x, a peer average of 38.8x and a US Hospitality sector level of 20.2x. Is that a margin of safety or a valuation stretch waiting to reset?
For a closer read on how this P/E gap could matter for future returns, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Starbucks leaves you on the fence, move quickly to test the numbers yourself and pressure check the story against your own expectations using our breakdown of 1 key reward and 3 important warning signs
Looking for more investment ideas beyond Starbucks?
If Starbucks leaves you thinking about what else might be hiding in plain sight, use the Simply Wall St screener to line up your next watchlist candidates.
- Spot potential mispricing early and review a focused set of 29 high quality undervalued stocks before sentiment catches up to the fundamentals.
- Strengthen portfolio resilience by filtering for a list of solid balance sheet and fundamentals (24 results) that can better handle tougher conditions.
- Dial down portfolio stress by concentrating on 30 resilient stocks with low risk scores that keep volatility in check while still offering room for returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com