


EN
Tsakos Energy Navigation (TEN) Faces Green Fuel Caution On A Fair Value Debate
Regulatory Signals And Fleet Decisions For Tsakos Energy Navigation
Tsakos Energy Navigation (NYSE:TEN) just received pointed advice from a Washington connected maritime policy guest, who urged caution on early green fuel commitments given uncertainty around the International Maritime Organization’s Net Zero Framework timeline.
Recent moves in Tsakos Energy Navigation’s share price suggest that investors are still reassessing the story. A 1-month share price return of 15.68% and a 90-day gain of 36.53% contribute to a very strong year-to-date share price return of 144.31% and a 5-year total shareholder return above 6x. This indicates that the latest regulatory commentary is being weighed against a much longer period of strong performance, rather than resetting the whole thesis overnight.
Spot similar regulatory and fleet transition stories by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may better withstand shifting green fuel timelines.Tsakos Energy Navigation now carries a long record of strong shareholder returns and a recent surge in the share price. The harder part is judging whether that strength is already fully reflected in the current valuation.
Most Popular Narrative: 14% Undervalued
On the most followed narrative, Tsakos Energy Navigation’s fair value of $62.50 sits above the last close at $53.48, which frames the current rally as investors weighing tanker cycle strength against a heavier capital program and softer earnings forecasts.
Tsakos Energy Navigation is committing around $3.1–3.2b to a 20–26 vessel newbuilding pipeline, while also adding modern secondhand ships. This increases future capital employed and can lift revenue and earnings expectations well beyond what current contracted cash flows support.
See why 12 investors see Tsakos Energy Navigation as 14% undervalued.
Result: Fair Value of $62.50 (UNDERVALUED)
Still, Tsakos Energy Navigation faces two obvious pressure points: a projected revenue decline and thinner future margins, that could easily unseat the 14% undervaluation story.
Find out about the key risks to this Tsakos Energy Navigation narrative.
Another View: What The DCF Says About Tsakos Energy Navigation
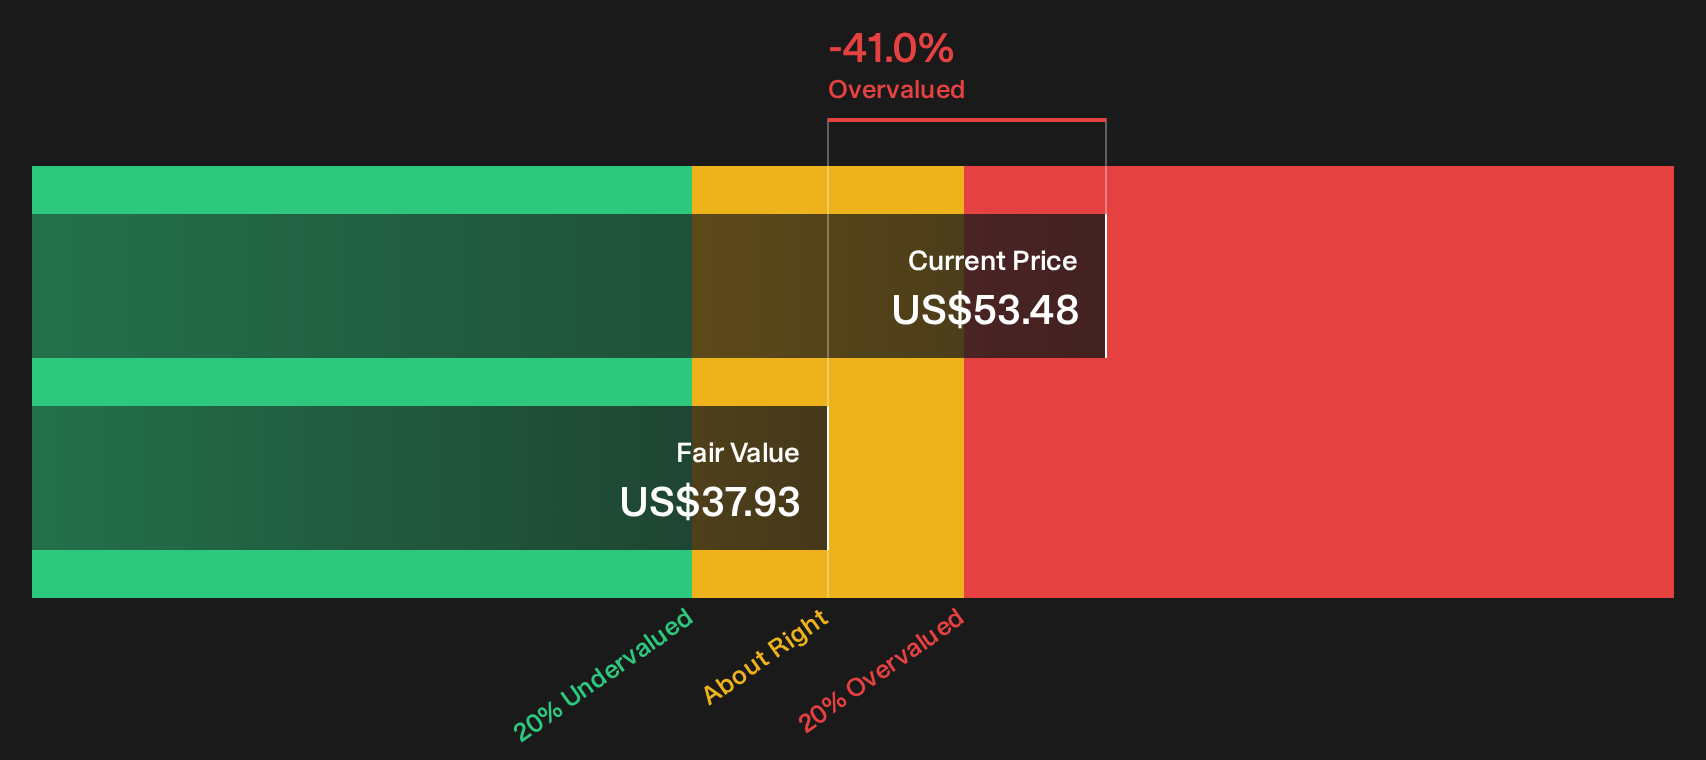
There is a very different message coming from the SWS DCF model. On that framework, Tsakos Energy Navigation at $53.48 sits above an estimated future cash flow value of $37.93. This points to the stock screening as overvalued rather than 14% undervalued. That gap raises a simple question for investors: Which story do you trust more, earnings multiples or long term cash flows?
For readers who want to see how sensitive this conclusion is to the inputs used, it is worth going through the full set of assumptions in the SWS DCF model, including the discount rate and cash flow path, before leaning on any single price target as a compass for action. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Tsakos Energy Navigation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Tsakos Energy Navigation, yet? If this mix of upside potential and flagged issues feels urgent, take a closer look at the underlying data and weigh both 3 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond Tsakos Energy Navigation?
Tsakos Energy Navigation raises big questions about value and risk, so widen the opportunity set and pressure test your thinking across other sectors and market caps.
- Target reliable compounding potential by focusing on businesses that screen as quality at a reasonable price through the 29 high quality undervalued stocks.
- Prioritise capital protection and smoother returns by scanning companies with sturdier balance sheets and fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Hunt for future standouts early by reviewing the 21 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com