


EN
LaSalle LOGIPORT REIT (TSE:3466) Cuts Payout Guidance As Valuation Questions Come Back Into Focus
LaSalle LOGIPORT REIT (TSE:3466) cut its distribution guidance for the fiscal period ending February 2027, trimming expected DPU to ¥4,000 and removing payouts in excess of retained earnings to smooth asset sale gains.
LaSalle LOGIPORT REIT’s latest move on distributions comes after a soft patch in the units, with the 30 day share price return down 4.58% and the year to date share price return down 12.04%. The 3 year total shareholder return is up 7.96%, even after a 2.06% total shareholder return decline over the past year.
Compare LaSalle LOGIPORT REIT’s revised payout profile with other income-focused opportunities by scanning our 29 dividend fortresses that aim to balance yield with resilience.
LaSalle LOGIPORT REIT is now offering a lower, smoother payout, while the unit price has already declined this year. Does that reset leave more upside than downside for new buyers, or does it provide not enough compensation for the cut?
Price-to-Earnings of 19.4x: Is it justified?
LaSalle LOGIPORT REIT changes hands at a P/E of 19.4x, a level that looks rich compared to both its regional peers and an internal fair ratio, even after the recent unit price weakness.
The P/E ratio compares what you pay today with the trust’s annual earnings per unit. For a REIT like LaSalle LOGIPORT REIT, it reflects how much unitholders are willing to pay for its current profit stream, given its portfolio, balance sheet, and distribution profile.
Here the market is pricing LaSalle LOGIPORT REIT above several reference points. The units trade on a P/E of 19.4x, which is higher than the Asian industrial REIT peer average of 15.9x and also above the estimated fair P/E of 17.6x that the fair ratio suggests the market could move toward over time.
Explore the SWS fair ratio for LaSalle LOGIPORT REIT.
Result: Price-to-Earnings of 19.4x (OVERVALUED)
Still, the reset could face pressure if LaSalle LOGIPORT REIT’s annual revenue and net income, both currently in decline, keep slipping, or if unit price weakness accelerates.
Find out about the key risks to this LaSalle LOGIPORT REIT narrative.
Another view on LaSalle LOGIPORT REIT’s value
The P/E screen presents LaSalle LOGIPORT REIT as expensive, yet the SWS DCF model tells a very different story. On that approach, the units trade at roughly a 77.4% discount to an estimated future cash flow value of about ¥616,939 per unit, which frames today’s price near ¥139,600 as potentially cheap instead of stretched. Which signal do you treat as the anchor?
Look into how the SWS DCF model arrives at its fair value.
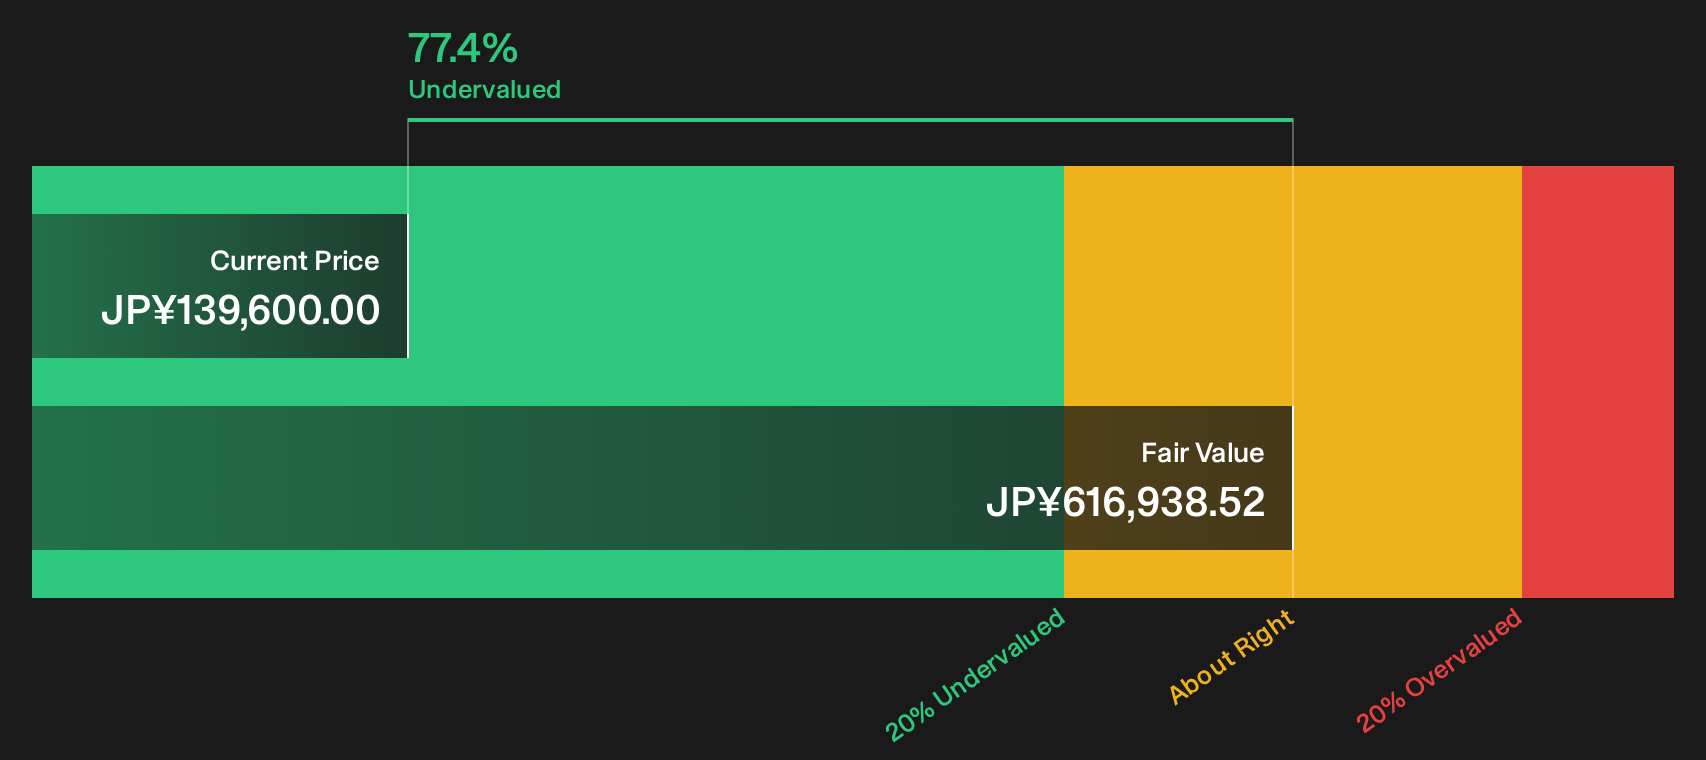
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LaSalle LOGIPORT REIT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around LaSalle LOGIPORT REIT is mixed, which is exactly when doing your own homework matters most. Move quickly, weigh both sides, and check the 3 key rewards and 3 important warning signs
Looking for more LaSalle LOGIPORT REIT investment ideas?
If LaSalle LOGIPORT REIT has sharpened your focus on value and income, do not stop here. Broaden your watchlist now and avoid missing other compelling setups.
- Target potential mispricing early by scanning a curated 14 high quality undervalued stocks that highlights companies with quality fundamentals at compressed valuations.
- Prioritise durability by reviewing a list of solid balance sheet and fundamentals (23 results) that spotlights businesses combining healthier leverage profiles with fundamental strength.
- Hunt for under-the-radar potential through a 72 high quality undiscovered gems built around financially sound opportunities that attract less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com