


EN
Unitil (UTL) Could Be 9% Below Fair Value As DCF Counters Overvalued View
Fresh attention on Unitil (UTL) has been driven by recent analysis suggesting its Dividend Discount Model value is broadly in line with the current share price, raising timely questions for income focused investors.
For context, Unitil’s share price has moved up 8.18% over the past month and 12.57% year to date, while long term holders have seen a 55.54% five year total shareholder return, indicating that momentum has been building rather than fading.
Spot 5 dividend fortresses that, like Unitil, aim to pair income potential with disciplined balance sheets for investors who care about the staying power of their payouts.For Unitil, that recent climb could be a clean read on a sturdier utility franchise or simply investors crowding back into dividend payers. The next step is to see what the cash flow math supports.
Most Popular Narrative: 2% Overvalued
Unitil’s most followed narrative pegs fair value at $54, slightly below the last close at $55.15. This lines up with a utility that screens as relatively steady rather than deeply mispriced.
The main thing that has to go right is that regulators continue to support decoupling and multi year rate mechanisms so Unitil can recover its roughly US$1.2b planned capital spend and integrate the new gas and water utilities as earnings accretive assets.
Constructive regulatory decisions in New Hampshire that approve higher base rates, maintain decoupling and increase allowed returns, alongside pending multi year rate proposals, create a framework that can support recovery of rising investment and contribute to steadier net margins and earnings.
See why 0 investors see Unitil as 2% overvalued.
Result: Fair Value of $54 (OVERVALUED)
Still, the narrative around Unitil could be knocked off course if regulators tighten allowed returns further or if future earnings fall short of analyst assumptions.
Find out about the key risks to this Unitil narrative.
Another View: Unitil Through The Cash Flow Lens
While the prevailing narrative tags Unitil as roughly 2% overvalued on a $54 fair value, the SWS DCF model presents a different picture. On that approach, the stock at $55.15 sits below an estimated future cash flow value of $59.93, which points to a modest undervaluation instead. Which signal appears more informative, the price target or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
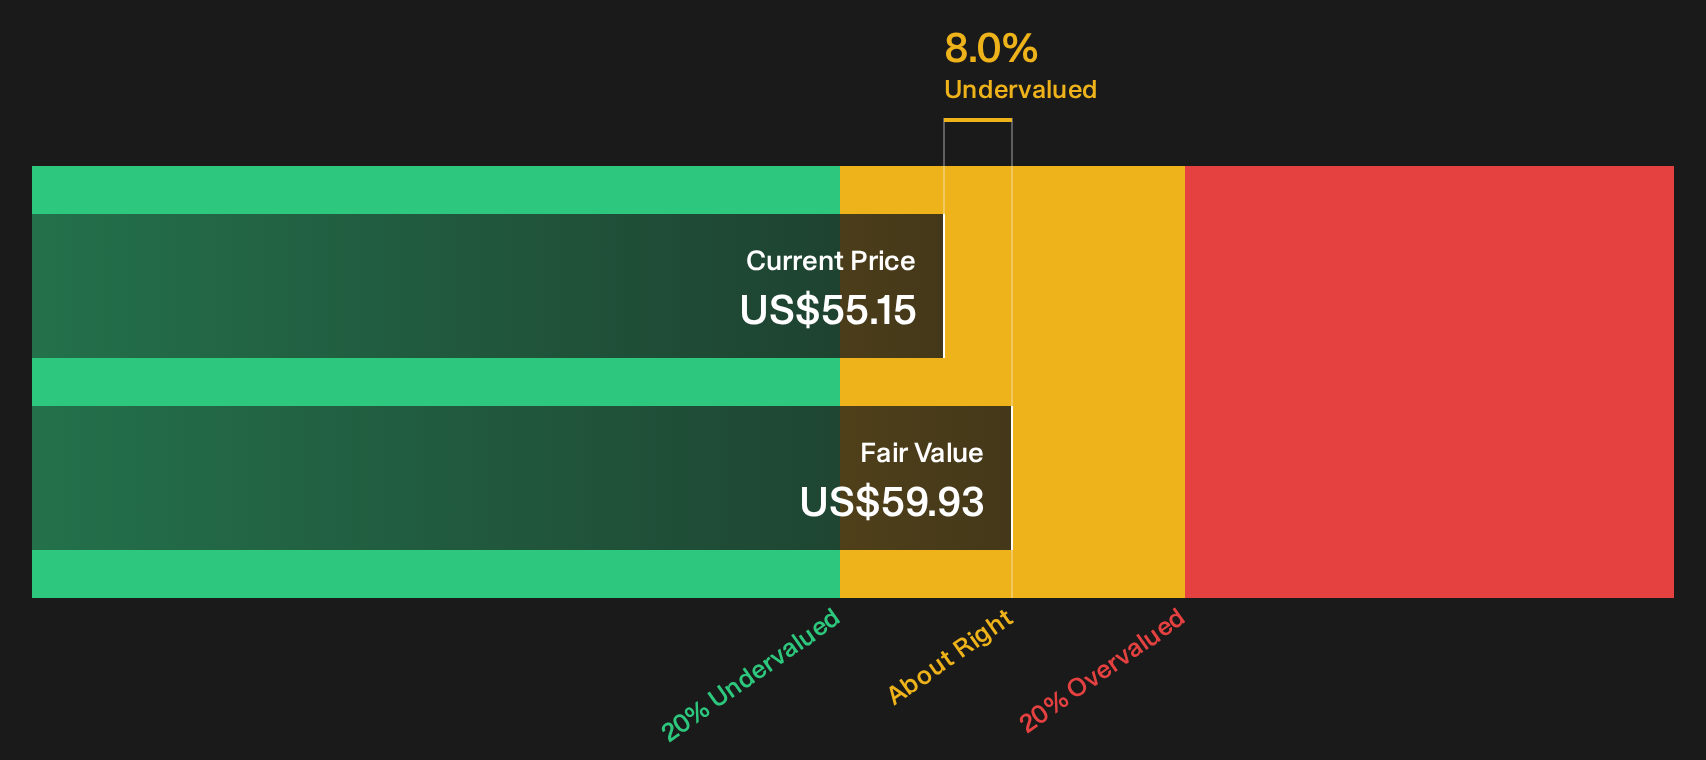
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Unitil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across Unitil’s valuation, income appeal and regulatory backdrop make this a moment to move fast on your own homework and pressure test the story against both the 1 or more risks and the 1 or more potential rewards that other investors are focused on, starting with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Unitil?
If Unitil has sharpened your focus on valuation, income and risk, do not stop here. Broaden your watchlist with a few targeted idea sets.
- Target dependable compounding by scanning a curated set of 29 high quality undervalued stocks that combine quality fundamentals with pricing that still looks restrained.
- Strengthen portfolio resilience by building around a list of solid balance sheet and fundamentals (24 results) that can better handle funding needs and economic shocks.
- Get ahead of the crowd by combing through 21 high quality undiscovered gems before attention and liquidity fully catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com