


EN
Murphy USA (MUSA) Stock Could Be 10% Overvalued After Dividend Hike
Murphy USA has delivered a powerful run over the past few years, which puts the spotlight squarely on what investors are paying for its underlying cash flows. With the share price recently closing at US$534.63 and a richer dividend stream now in play, the key issue is whether that cash generation can support where the stock trades today.
- Murphy USA has returned 236.4% over 5 years, which raises the question of how fully its existing and expected cash flows are already reflected in the share price.
- The 11% increase in the quarterly dividend to US$0.72 per share points to management confidence in Murphy USA's ability to keep producing enough cash to fund both payouts and ongoing investment.
- If you'd rather focus on earnings, this one's for you. See what Murphy USA's 15.9x P/E says about the price.
The issue now is whether Murphy USA's current market value lines up with what the Discounted Cash Flow (DCF) view of its cash flows implies.
If you want to test the same cash flow question beyond Murphy USA, compare it with other companies using the 29 high quality undervalued stocks.
Is Murphy USA Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) model values Murphy USA by projecting the cash it could return to shareholders and then discounting those amounts back to today. Over the last twelve months, the retailer generated about $535.4 million of free cash flow, and analysts are expecting future annual figures in a similar ballpark rather than a dramatic reset in either direction.
Those projections assume Murphy USA keeps producing steady, gradually growing cash flows into the next decade, which is consistent with a mature fuel and convenience store operator rather than a high growth story. The DCF outcome sits modestly below the current share price of US$534.63, which suggests investors are already paying a premium for that reliability. The 11% dividend increase to $0.72 per share fits with that picture because a richer payout can reinforce the appeal of a stable cash generator that the market is willing to value slightly above what the DCF implies. Find out what Murphy USA could be worth using our Discounted Cash Flow (DCF) estimate.
The Murphy USA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Murphy USA pick up where the DCF puzzle leaves off. They spell out which paths for Murphy USA's growth, margins and earnings would need to play out for the stock to be worth materially more or materially less than today's price on the market. Each narrative ties a specific valuation to a clear storyline about Murphy USA's possible catalysts and risks, so you can track over time which version of events is actually unfolding.
One of the top community narratives on Murphy USA: 13% undervalued
"Rapid expansion of the Murphy Drive Rewards program, adding more than 600,000 members per month in early and mid 2026 and successfully driving pump to store conversion through targeted offers..."
Discover why this Narrative puts Murphy USA at 13% undervalued.
One more Murphy USA check that belongs beside the cash flow math
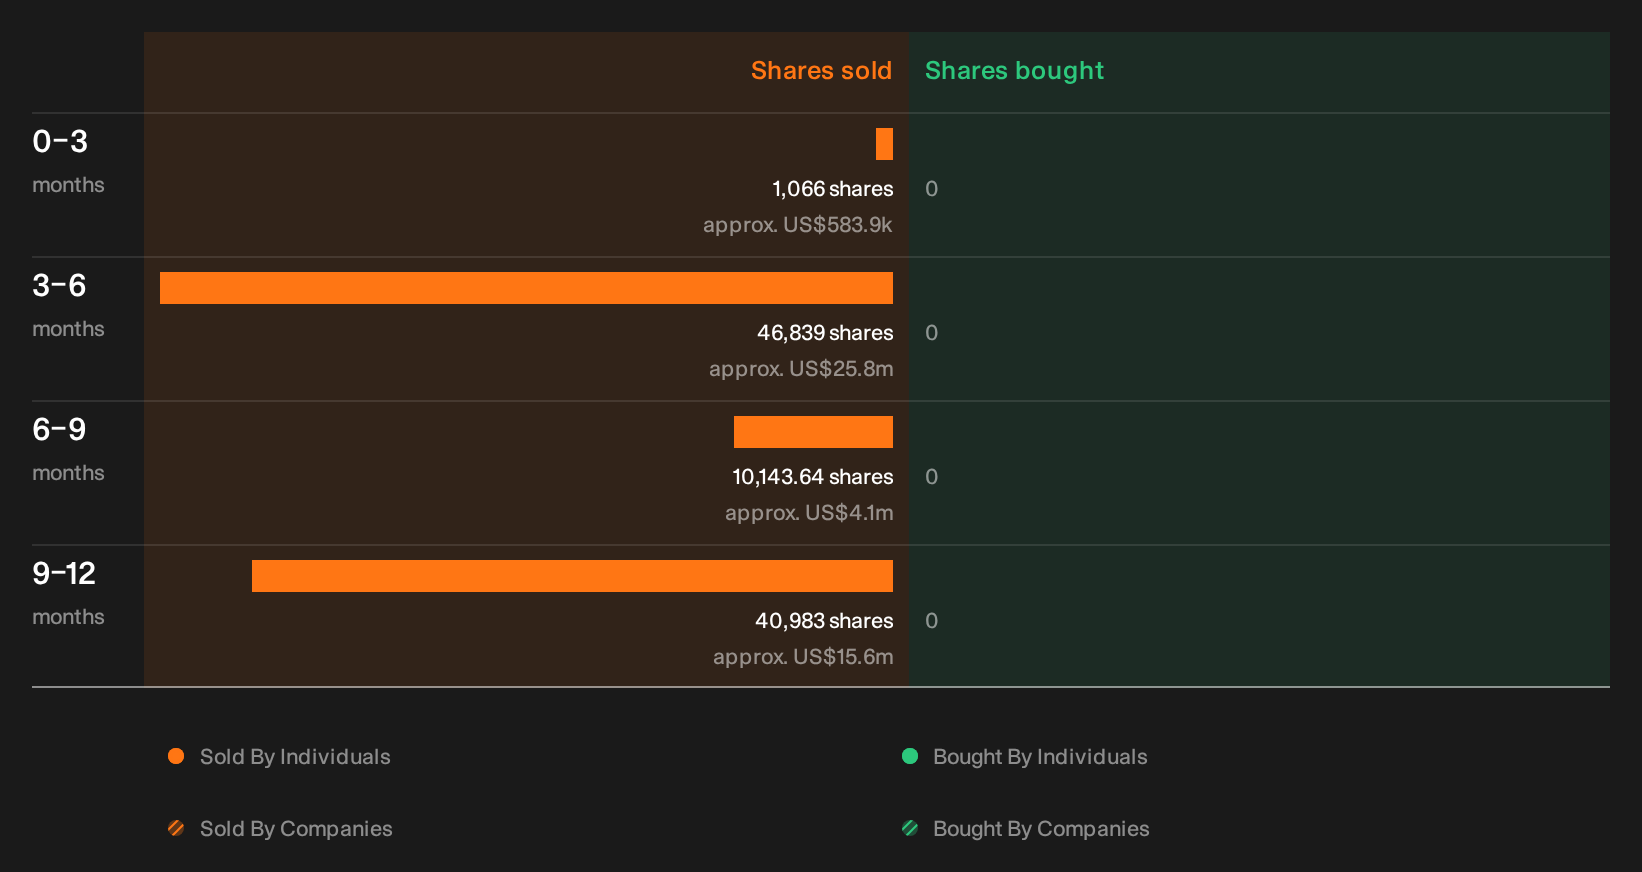
Price, cash generation and dividends tell only part of the Murphy USA story. Recent transactions by people inside the business have been flagged by our checks, and the individuals, sizes and possible readthroughs are all there for you to review. See the recent insider selling flagged for Murphy USA.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com