


EN
Cheniere Energy (LNG) Locks In LNG Demand With QatarEnergy But Is It Fully Valued
Cheniere Energy (LNG) is back in focus after signing multi decade liquefied natural gas supply agreements with QatarEnergy that lock in demand through 2054 and support expansion plans at Sabine Pass.
Recent trading suggests investors are rewarding this visibility, with Cheniere Energy’s 1-month share price return of 11.22% and 90-day gain of 16.72% adding to a 51.00% year to date rise, while a 5-year total shareholder return of 203.61% points to momentum that has built over several years.
Capitalize on how Cheniere Energy is locking in decades of LNG demand by scanning a curated list of peers with similar long-term potential using the 16 nuclear energy infrastructure stocks.For Cheniere Energy, the recent jump can be interpreted in two ways. Is the market finally recognizing the contracted LNG cash flows? Or has sentiment simply moved ahead of what the current valuation supports?
Most Popular Narrative: 3.6% Undervalued
Cheniere Energy’s most followed narrative pins fair value at $309.95, just above the latest close of $298.67. This frames today’s rally against a modest implied discount built on contracted LNG capacity and reliability upgrades rather than blue sky demand stories.
The highly contracted nature of Cheniere Energy’s LNG platform through 2030 and into 2035, combined with an investment grade credit profile and a capital return program that targets dividend growth and share repurchases, is set to keep a large portion of future EBITDA and distributable cash flow tied to recurring, contracted revenue.
Actions to apply normal purchases and normal sales accounting to a majority of IPM gas supply volumes are intended to reduce the volatility of reported net income that comes from LNG linked derivatives, which can help future earnings more closely reflect the underlying cash generating capacity of the business.
See why 68 investors see Cheniere Energy as 4% undervalued.
Result: Fair Value of $309.95 (UNDERVALUED)
Still, Cheniere Energy’s narrative can be knocked off course if LNG linked derivatives keep swinging reported earnings or if the US$370m tax credit probe tightens cash flexibility.
Find out about the key risks to this Cheniere Energy narrative.
Another View: Cheniere Energy Through The P/E Lens
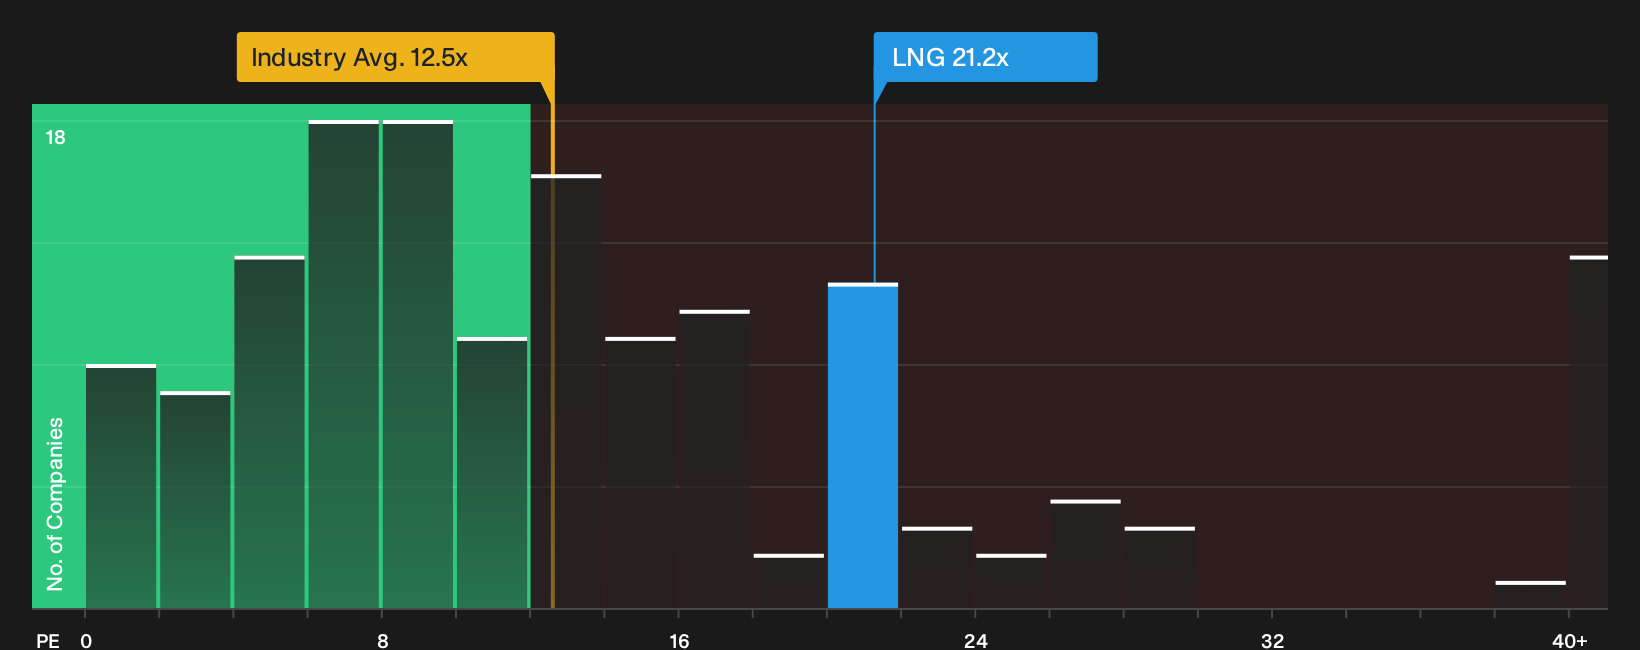
The community narrative sees Cheniere Energy as 3.6% undervalued at $309.95 fair value, yet the P/E math points the other way. At 21.2x earnings, the stock trades richer than US Oil and Gas at 12.5x, peers at 17.1x, and even its own fair ratio of 20x. This raises the question of whether investors are already paying upfront for much of that contracted LNG story.
That kind of premium can signal confidence in the LNG platform, or it can simply compress future return potential if expectations cool. It is therefore worth stress testing whether your thesis really supports paying more than the sector and that fair ratio for Cheniere Energy today, while you weigh the valuation risk this implies in your own process.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Cheniere Energy story has shown mixed signals so far. Consider taking action while sentiment remains active and evaluate both the potential risks and rewards with the 1 key reward and 2 important warning signs.
Looking for more Cheniere Energy style ideas?
If Cheniere Energy has sharpened your focus on quality and timing, do not stop here. Broaden your opportunity set with targeted stock ideas built from the ground up by the Simply Wall Street Screener.
- Target durable value by scanning a curated pool of companies that combine quality fundamentals with potential mispricing through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that offer resilient yields and aim for reliability with the 5 dividend fortresses.
- Raise your quality bar by focusing on companies supported by robust finances and strong balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com