


EN
Learn Why The Bull Case For Yancoal Australia Stock Could Change Following Higher Coal Output
- Yancoal Australia reported September quarter sales volumes of 9.0 Mt, with nine month attributable sales of 28.8 Mt and higher production across most coal metrics compared with the prior year period.
- The combination of increased year to date output, exposure to higher priced coking coal through the Kestrel acquisition, and a long dated Hunter Valley mine extension indicates a materially larger production platform that could support future cash generation potential.
- We will now look at how Yancoal Australia’s stronger nine month coal production profile could reshape the broader investment narrative.
Scan the coal space beyond Yancoal Australia by comparing its production profile and price exposure with our curated list of 33 best rare earth metal stocks to see how resources-focused plays stack up.
What Is Yancoal Australia's Investment Narrative?
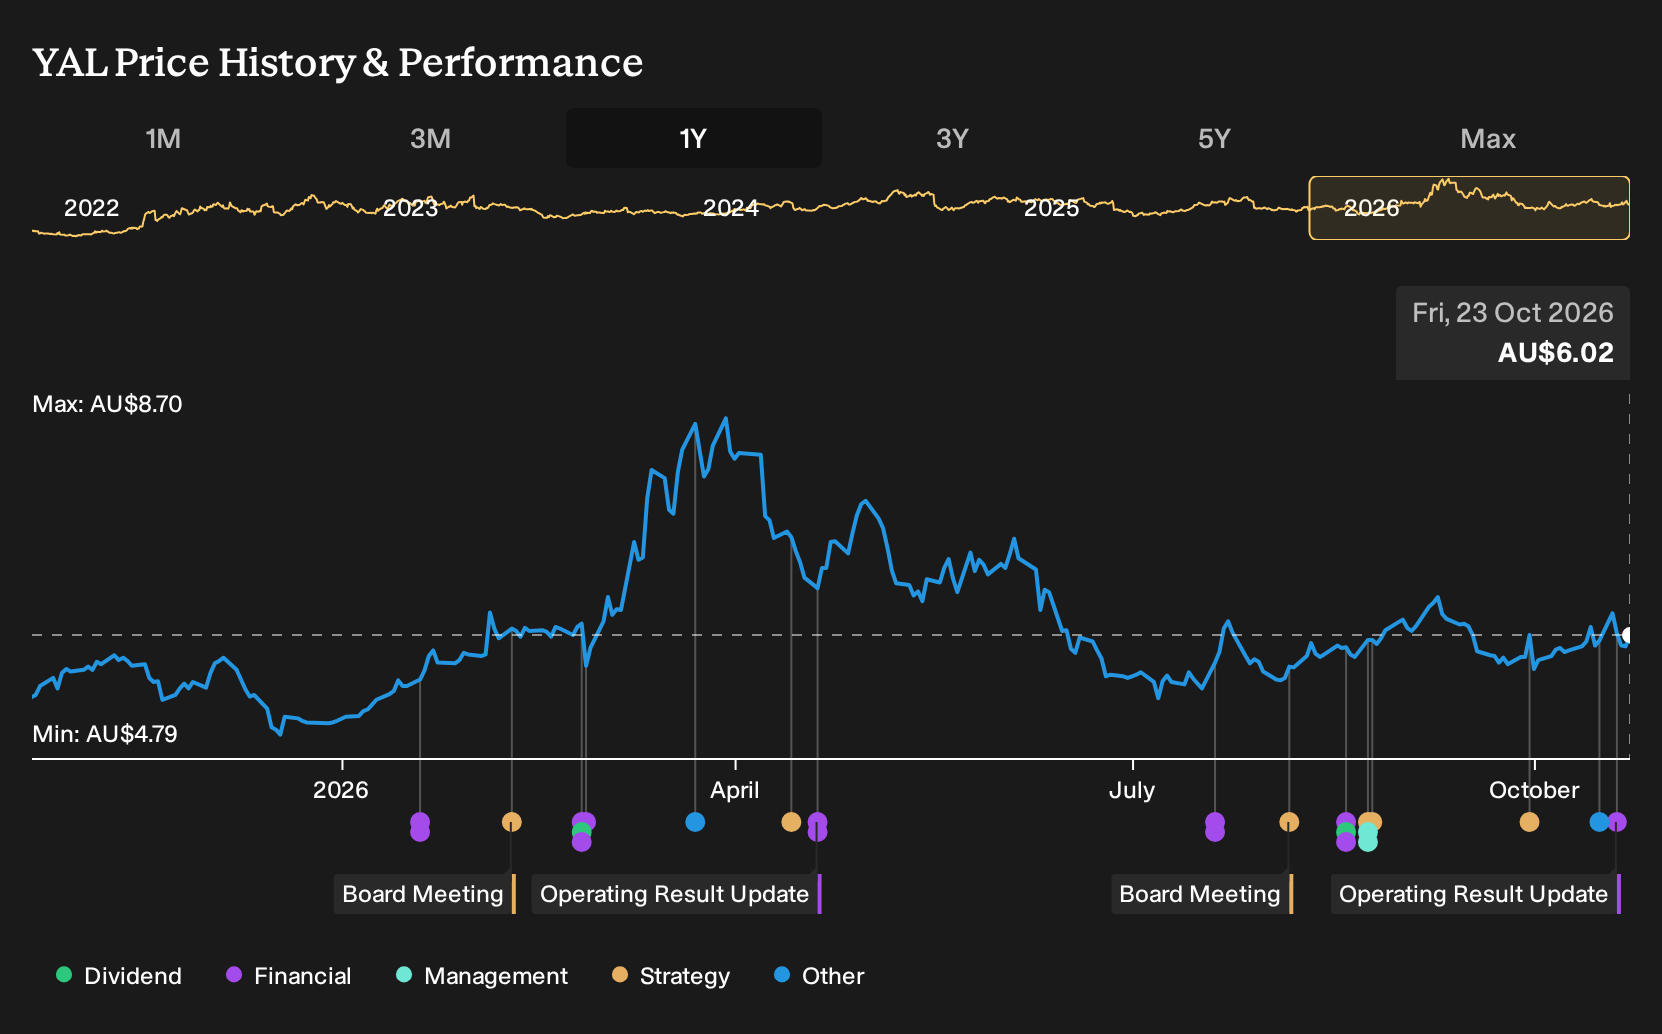
To own Yancoal Australia, you need to be comfortable with a coal producer that is leaning hard into volume, mine life and product mix. The latest quarter showed slightly softer attributable sales volumes at 9.0 Mt compared with 10.7 Mt a year earlier, yet the nine month tally moved to 28.8 Mt from 27.3 Mt as production metrics edged higher. The Kestrel acquisition adds coking coal exposure, while the 19 year Hunter Valley extension points to a long running, capital intensive asset base that still depends on coal pricing and cost discipline to translate tonnes into meaningful earnings.
The recent update does not rewrite the near term story, but it sharpens the focus. The business is still highly sensitive to seaborne coal demand and pricing, and net profit margins already compressed to 4.7% from 15%. This puts execution around Kestrel integration, sustaining capex and unit costs under the microscope. Earnings are forecast to grow faster than the broader Australian market according to current estimates, yet Yancoal Australia also trades on a higher P/E multiple than industry and peer averages, so any stumble on volumes, grades or realized prices would matter quickly.
Yet there is a quieter tension in the Yancoal Australia setup that only really becomes obvious when you look at how it funds itself and ...
There's only one way to know the right time to buy, sell or hold Yancoal Australia. Head to Simply Wall St's company report for the latest analysis of Yancoal Australia's Fair Value.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Yancoal Australia research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Yancoal Australia. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Yancoal Australia's overall financial health at a glance.
Looking For More Investment Ideas Beyond Yancoal Australia?
Once you have formed a view on Yancoal Australia, it can help to widen the lens and compare it with other businesses that fit different risk, income and value profiles using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, scan our curated set of 2 high quality undervalued stocks that may offer a mix of cash generation and balance sheet strength.
- For investors who care most about income resilience, focus on companies in our collection of 6 dividend fortresses that aim to pair higher yields with sturdier business models.
- If capital preservation sits at the top of your checklist, concentrate on the 6 resilient stocks with low risk scores which highlight businesses assessed to have more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com