


EN
Medifast (MED) Q3 earnings report preview: what to look for
Wellness company Medifast (NYSE:MED) will be announcing earnings results this Monday before market hours. Here’s what to look for.
Medifast beat analysts’ revenue expectations last quarter, reporting revenues of $76.38 million, down 27.6% year on year. It was a stunning quarter for the company, with EPS guidance for next quarter exceeding analysts’ expectations and a beat of analysts’ EPS estimates.
Is Medifast a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Medifast’s revenue to decline 20.3% year on year, improving from the 36.2% decrease it recorded in the same quarter last year.
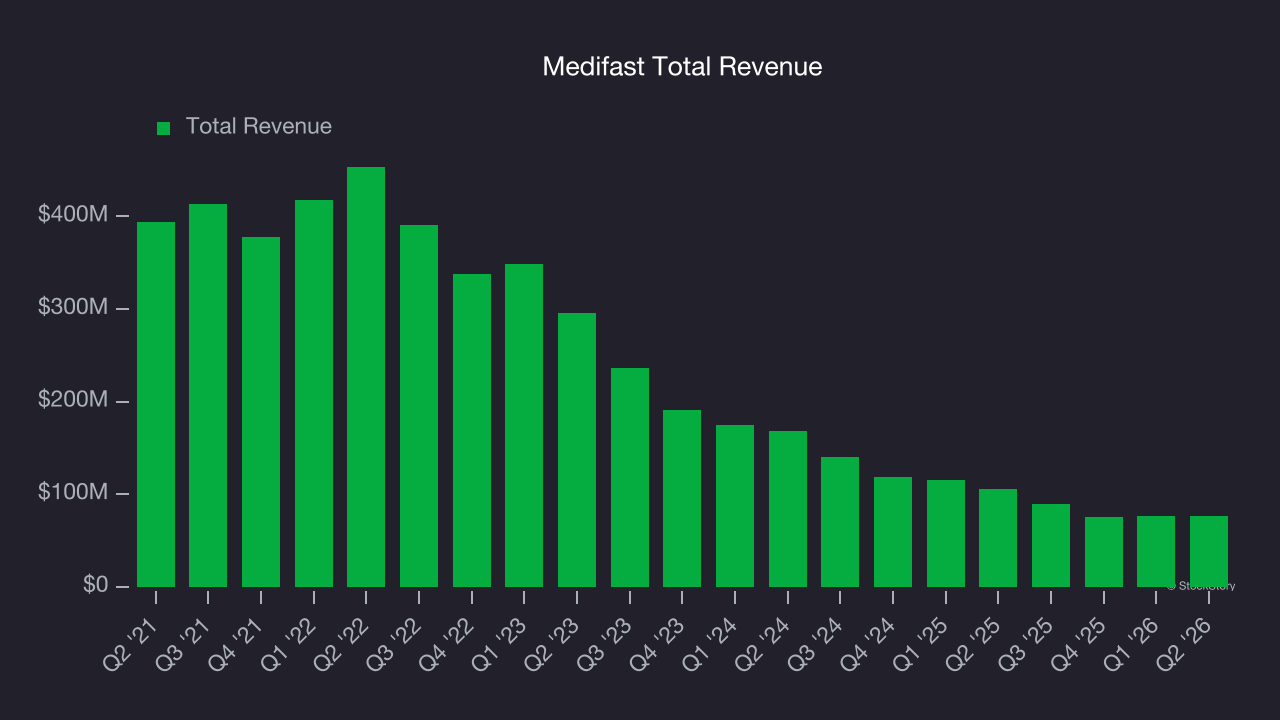
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Medifast has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Medifast’s peers in the consumer staples segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Vita Coco delivered year-on-year revenue growth of 33.7%, beating analysts’ expectations by 6.1%, and Conagra reported a revenue decline of 1.4%, in line with consensus estimates. Vita Coco traded down 11% following the results while Conagra was also down 6.6%.
Read our full analysis of Vita Coco’s results here and Conagra’s results here.
There has been positive sentiment among investors in the consumer staples segment, with share prices up 3.8% on average over the last month. Medifast is down 2.6% during the same time and is heading into earnings with an average analyst price target of $12 (compared to the current share price of $11.85).
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.