


EN
Is Ulta Beauty (ULTA) Fully Valued As Strong Revenue Trends Keep Drawing Attention?
Ulta Beauty (ULTA) is back in focus after recent attention on its pattern of positive revenue trends and a history of topping earnings forecasts, even as analyst ratings remain broadly neutral.
Recent trading backs up that attention. Ulta Beauty’s share price has climbed 29.96% over the past 90 days and 14.54% over the last month, while the 1-year total shareholder return of 20.63% points to building momentum rather than a short-lived spike.
Scan how Ulta Beauty’s momentum compares with other retailers by reviewing a curated shortlist of 21 high quality undiscovered gems that share strong fundamentals but attract far less attention.
Ulta Beauty has already rewarded holders with a sharp move, yet the stock now trades only slightly below the average analyst target. After that run, investors may ask whether the current valuation still leaves enough potential upside to justify taking on new risk.
Most Popular Narrative: 1% Undervalued
Ulta Beauty last closed at $624.46, while the most followed narrative pegs fair value at $631.44, leaving only a small implied discount yet still anchoring expectations on its newer profit engines.
The loyalty and data ecosystem, with about 47 million active members and 95% of sales coming through the program, is being leveraged into more granular personalization, AI powered search and an Ulta AI shopping agent. These capabilities can improve conversion, average ticket and marketing efficiency and therefore support revenue growth and SG&A leverage.
See why 76 investors see Ulta Beauty as 1% undervalued.
Result: Fair Value of $631.44 (ABOUT RIGHT)
Still, the Ulta Beauty story can break if heavy investment in wellness, AI and new regions inflates costs faster than sales, or if rising beauty competition squeezes merchandise margins.
Find out about the key risks to this Ulta Beauty narrative.
Another View: Ulta Beauty Looks Full on Earnings
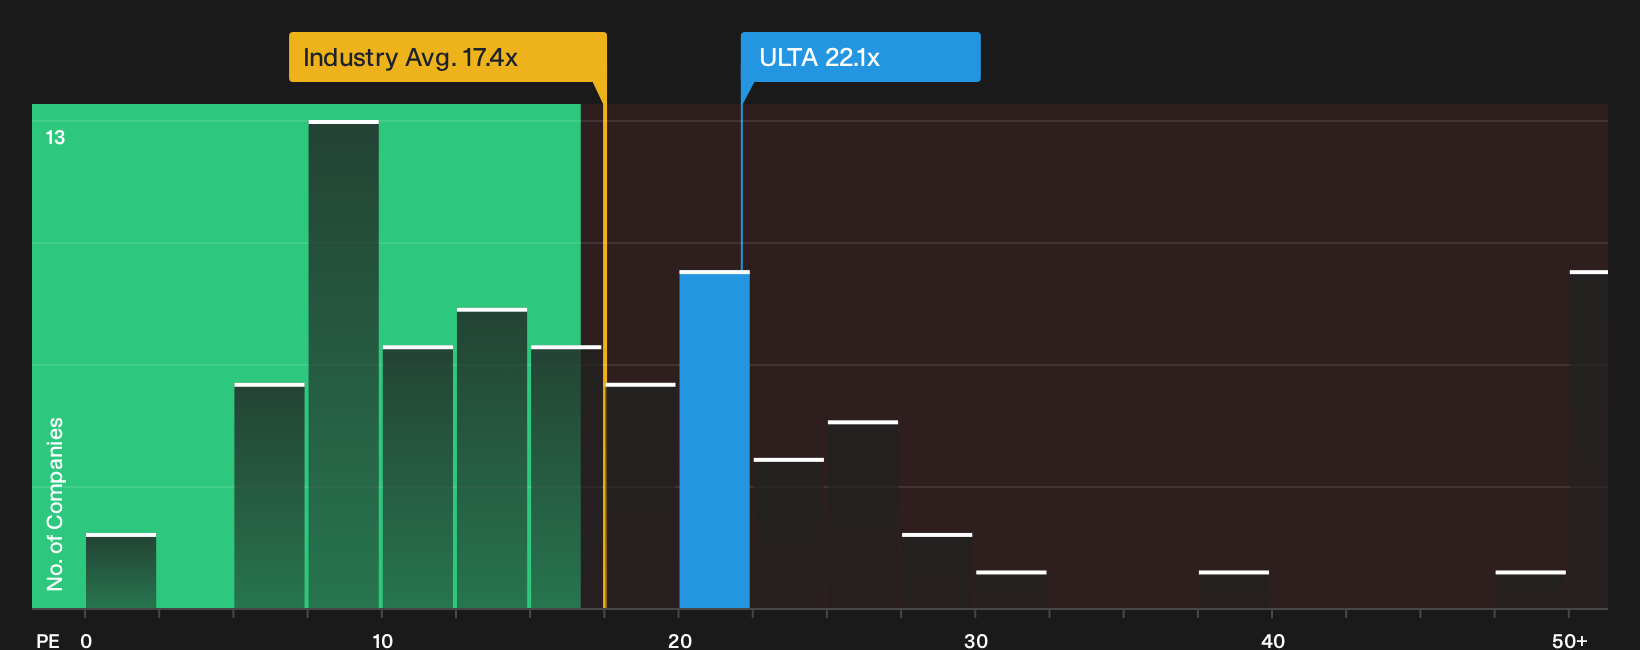
The first narrative framed Ulta Beauty as roughly fairly priced around $631.44. On a simple P/E check, the picture looks less forgiving. ULTA trades on 22.1x earnings, compared with 17.4x for the US Specialty Retail group, 21.3x for peers, and a fair ratio of 16.1x.
That gap means buyers today are paying a clear premium over both the sector and where the fair ratio suggests the multiple could drift over time. The question for investors is whether Ulta Beauty’s newer wellness and data engines justify that richer sticker, or whether that premium is already doing most of the heavy lifting.
To see what the numbers say about this valuation premium, and how it could adjust if expectations change, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ulta Beauty’s valuation and momentum can cut both ways, so move quickly through the data and weigh 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ulta Beauty?
If Ulta Beauty already sits on your radar, consider widening your opportunity set by screening for other candidates that match your return goals and risk comfort.
- Explore potential mispricings by scanning a focused set of 29 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (24 results) where conservative financing and cleaner balance sheets help limit financial shocks.
- Adjust volatility exposure by filtering for a 30 resilient stocks with low risk scores designed to highlight businesses with steadier profiles and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com