


EN
Bonesupport Holding (OM:BONEX) Could Be 11% Undervalued As Strong Q3 Earnings Land
Bonesupport Holding (OM:BONEX) just paired a fresh third quarter earnings update with news of a completed share buyback, putting both profitability and capital return firmly in focus for investors.
The fresh Q3 figures and completed buyback land against a powerful run in the BONEX share price, with a 31.46% 7 day share price return and 54.70% 30 day share price return feeding into an 86.85% year to date share price return. The 5 year total shareholder return of about 7x signals long term holders have already seen very large gains as sentiment around Bonesupport Holding has shifted toward stronger earnings delivery and capital returns.
Spot similar earnings momentum and balance sheet strength by scanning our hand-picked list of solid balance sheet and fundamentals (205 results) alongside Bonesupport Holding's latest move.It now looks like a strong, profitable orthobiologics specialist paired with an aggressive share price move. The real question is whether Bonesupport Holding at SEK 332.60 still reflects reasonable value or has already priced in the good news.
Most Popular Narrative: 11% Undervalued
Bonesupport Holding’s most followed narrative places fair value at SEK 373.83 per share, above the latest SEK 332.60 close. This puts the recent rally against a still supportive valuation anchor built on growth and margin expectations.
The launch momentum for CERAMENT G in the U.S. is accelerating, with a notable trend of high repeat usage and expansion into additional indications among existing customers, which is expected to positively impact future revenue growth.
The submission of the CERAMENT V application to the FDA and potential NTAP reimbursement provide future catalysts for revenue growth and improved margins once approved and implemented.
See why 32 investors see Bonesupport Holding as 11% undervalued.
Result: Fair Value of SEK373.83 (UNDERVALUED)
Still, the bullish Bonesupport Holding narrative leans heavily on CERAMENT reimbursement support and stable healthcare staffing, both of which could shift and pressure future profitability.
Find out about the key risks to this Bonesupport Holding narrative.
Another View: Bonesupport Holding Looks Expensive On Earnings
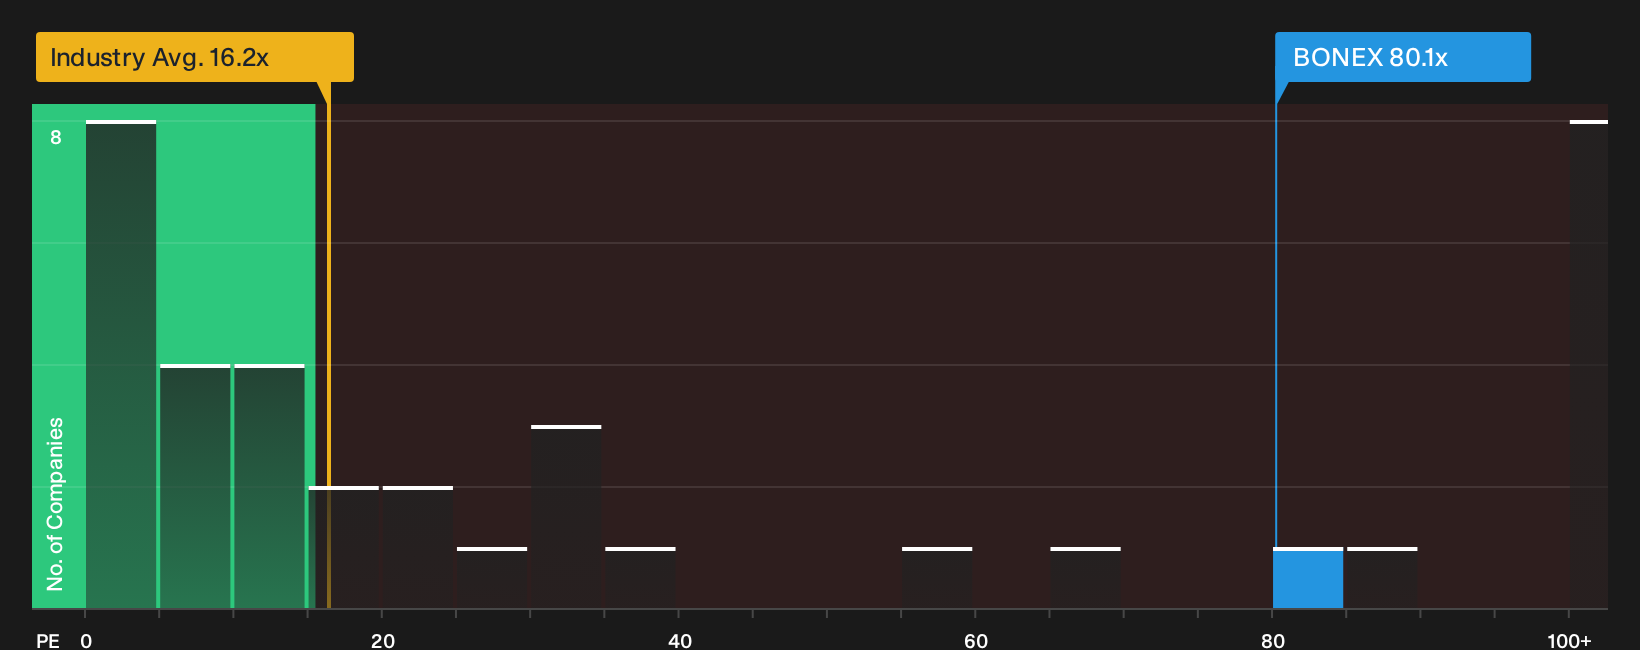
The upbeat fair value story around Bonesupport Holding runs into a very different picture when you look at its P/E. The stock trades on about 80.1x earnings, compared with 16.2x for the European biotech group, a peer average of 52.9x, and a fair ratio estimate of 52.7x.
This gap suggests investors today are paying a heavy premium for BONEX, rather than a clear discount. The real question is whether you see that extra multiple as justified upside potential or valuation risk if expectations cool.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Bonesupport Holding valuation and expectations can be useful, but only if you see the numbers for yourself and move quickly to form a view based on 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bonesupport Holding?
If you want a broader watchlist alongside Bonesupport Holding, use these curated stock lists to pressure test your thinking and avoid missing other compelling setups.
- Target steadier compounding potential by reviewing 221 resilient stocks with low risk scores that pair resilient balance sheets with lower measured business risk.
- Hunt for quality at a discount by scanning the 613 high quality undiscovered gems that combine strong fundamentals with limited current market attention.
- Build a more dependable income stream by checking companies in the 226 dividend fortresses that focus on higher yields backed by underlying cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com