


EN
ICL Group (ICL) Could Be 77% Undervalued Following Fresh DCF Commentary
Recent commentary around ICL Group (ICL) centers on a valuation gap. A fresh Discounted Cash Flow model points to an intrinsic value above the current share price, raising questions about how the market is pricing its future cash generation.
ICL Group’s recent share price tells a mixed story. The stock is up 1.27% on a 1-day share price return, yet down 17.62% year to date and the 1-year total shareholder return has fallen 25.31%. At the same time, the 3-year total shareholder return shows a 7.54% gain, which points to fading momentum in the near term while longer-term holders still sit on modest gains that frame the current DCF-based undervaluation debate.
Compare ICL Group's valuation gap with a curated set of potential deep value ideas by scanning the 29 high quality undervalued stocks that combine strong fundamentals with discounted prices.
ICL Group has slipped on a 1-year and year-to-date basis, while a fresh DCF model suggests a sizable gap to intrinsic value. Do you lean into that disconnect now, or wait for an even cheaper entry before the numbers do the talking?
Preferred P/E of 20.2x: Is it justified?
ICL Group screens as undervalued on the SWS DCF model, with an estimated future cash flow value of $8.42 against a last close of $4.77. However, the preferred P/E multiple of 20.2x puts that discount in the context of what investors are currently paying for each dollar of earnings.
The P/E ratio captures how much the market is willing to pay today for ICL Group's recent profit run rate. For a diversified minerals and chemicals producer with $7.7b in revenue and exposure across potash, phosphate, industrial products, and growing solutions, earnings often swing with pricing cycles and one-off items, so the earnings denominator itself can be volatile.
ICL is flagged as good value based on its 20.2x P/E compared to both its direct peer set on 26.3x and the wider US Chemicals industry at 22.1x. That meaningful discount suggests investors are paying less for each dollar of ICL's earnings than for sector alternatives, even though the SWS DCF model and analyst targets both point to upside potential in the share price.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 20.2x (UNDERVALUED)
Still, the investment case around ICL Group can weaken if fertilizer pricing declines further or if its diverse end markets reduce demand at the same time.
Find out about the key risks to this ICL Group narrative.
Another view on ICL Group’s value
ICL Group appears inexpensive based on its earnings, and the SWS DCF model presents an even stronger case, with an estimated future cash flow value of $8.42 compared with a $4.77 share price. That suggests potential undervaluation on a cash flow basis as well. Which perspective do you rely on when both signals point toward a discount?
Look into how the SWS DCF model arrives at its fair value.
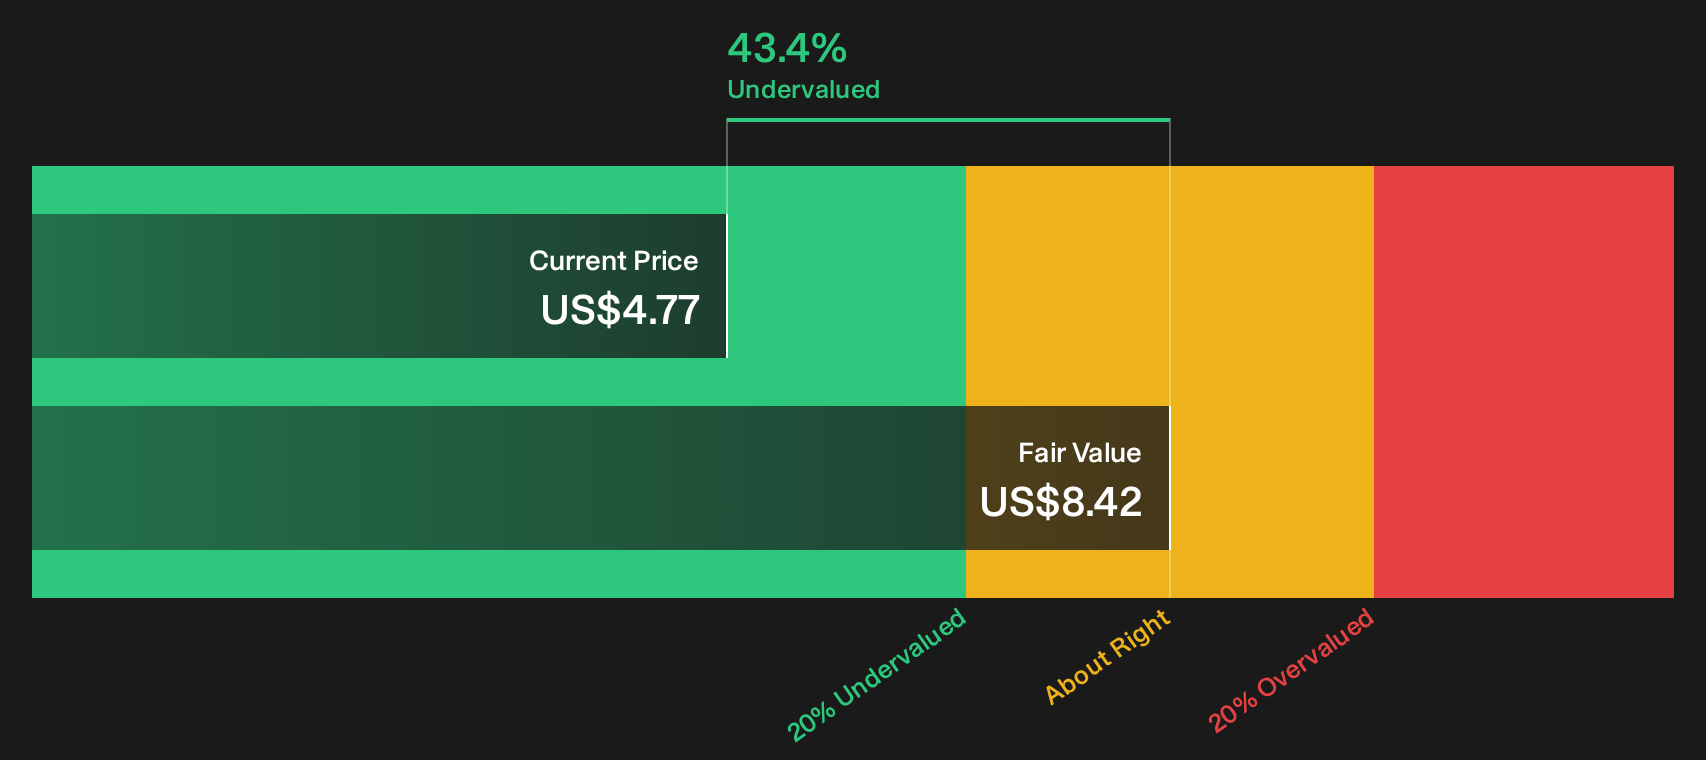
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ICL Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around ICL Group can feel uncomfortable when money is on the line, so move quickly, review the full data set, and decide where you stand after weighing 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond ICL Group?
If ICL Group has sharpened your focus on value and quality, do not stop here. Build a broader watchlist and let the data guide your next move.
- Target potential mispricing opportunities by scanning the 29 high quality undervalued stocks that pairs solid business quality with discounted valuations.
- Prioritize resilience in tougher markets by using the 30 resilient stocks with low risk scores that screens for companies with more robust risk profiles.
- Hunt for under-the-radar potential through the 21 high quality undiscovered gems that focuses on businesses with strong fundamentals that are not widely followed yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com