


EN
What Just Happened With Holcim (SWX:HOLN)?
Holcim (SWX:HOLN) moved back into focus after its Q3 2026 trading update, as management raised full-year earnings guidance and confirmed higher organic recurring EBIT growth expectations of 10% to 12%.
Holcim’s Q3 update hit a market that had been cautious for most of 2026, with the latest 1-day share price return of 5.03% lifting the stock to CHF66.8 after a year-to-date share price decline of 14.51%. The short-term bounce contrasts with a softer 90-day share price return of 9.80% and a 1-year total shareholder return down 2.08%. However, the 3-year and 5-year total shareholder returns of 159.28% and 244.43% respectively show that longer term holders have still seen very strong compounding. This helps frame today’s move as investors reassessing growth potential and risk after upgraded guidance and the planned Fermacell acquisition.
Scan how investors are repricing building materials after Holcim’s guidance upgrade by comparing it with a hand-picked 194 high quality undervalued stocks in similar cash generative businesses.
Bulls see Holcim’s upgraded 2026 earnings guidance and Fermacell deal as proof the recent share price dip has gone too far. Bears point to the weaker recent returns. Which side do the current valuation signals support?
Most Popular Narrative: 18% Undervalued
Holcim’s most followed narrative pegs fair value at CHF81.27, which sits well above the last close of CHF66.8 and frames the upgraded guidance in a more generous light.
Holcim's focus on sustainable products, targeted acquisitions, decarbonization, and disciplined financial management positions it for resilient growth, margin strength, and industry leadership.
Sustained investments and leadership in decarbonization, circular construction, and innovation (including net-zero cement initiatives and supplementary cementitious materials) position Holcim ahead of industry regulatory trends, enabling it to secure new revenue streams, access premium markets, and defend margins amid tightening climate rules.
See why 53 investors see Holcim as 18% undervalued.
Result: Fair Value of CHF81.27 (UNDERVALUED)
Still, the Holcim narrative could be knocked off course if acquisition integration disappoints, or if regulatory costs in key regions rise faster than expected.
Find out about the key risks to this Holcim narrative.
Another Angle On Holcim’s Valuation
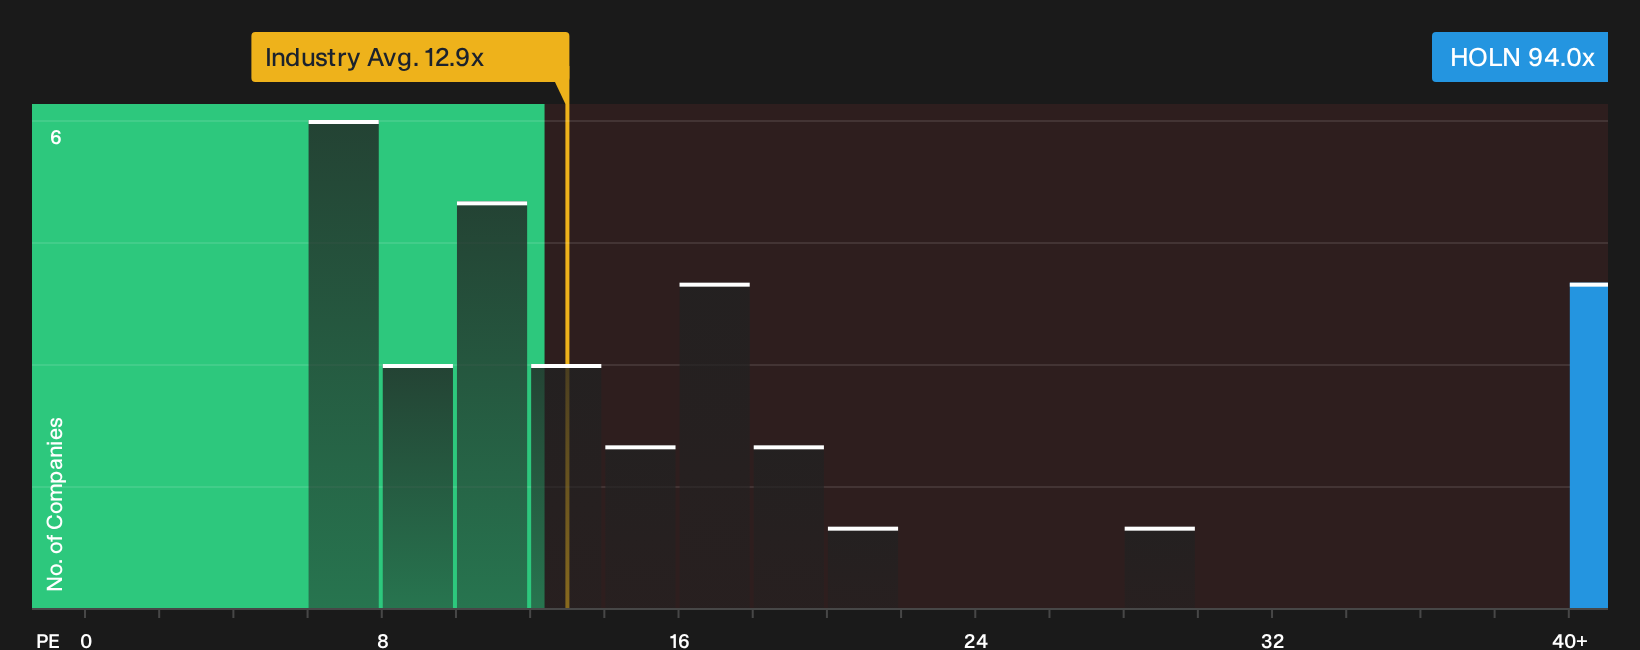
The DCF-driven fair value of CHF81.27 paints Holcim as undervalued at CHF66.8, yet the picture changes when looking at earnings multiples. The stock trades on a P/E of 94x, compared with a fair ratio of 41.9x and a European Basic Materials average of 12.9x. That gap raises a simple question: Is the market mispricing future profit, or is the cash flow model too optimistic?
To pressure test this richer earnings multiple against the cash flow view, it can help to take a closer look at how the ratio could move toward its fair ratio over time and what that might mean for both valuation risk and upside. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data, or a clear skew in sentiment around Holcim’s outlook? Step through the figures, weigh both sides of the story, then pressure test your own thesis against our breakdown of 3 key rewards and 4 important warning signs.
Looking for more Holcim-like investment ideas?
If Holcim’s story has you thinking bigger, do not stop here. Broaden your opportunity set and pressure test your thesis against other high quality prospects.
- Target resilient compounding potential by reviewing a 226 dividend fortresses that focuses on income strength paired with stability.
- Hunt for quality at a sensible price by scanning a 613 high quality undiscovered gems that highlights businesses with strong fundamentals yet limited attention.
- Reduce portfolio stress by weighing a 221 resilient stocks with low risk scores that filters for companies with more resilient risk profiles and steadier scorecards.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com