


EN
BAWAG Group (WBAG:BG) Could Be 21% Undervalued Following Reaffirmed 2026 Guidance
BAWAG Group (WBAG:BG) drew fresh attention after reporting third quarter net income of €247.5 million and reconfirming its 2026 targets, including net profit over €960 million and tight cost control metrics.
Despite the reaffirmed 2026 targets, BAWAG Group’s recent share price has cooled, with a 7-day share price return down 7.66% and a 30-day share price return down 14.05%. However, the year-to-date share price return is up 19.54% and the 5-year total shareholder return is up 303.99%, suggesting long term holders have still seen substantial gains while shorter term momentum has faded.
Scan for other banks showing similar earnings strength and cost discipline with our curated 221 resilient stocks with low risk scores while BAWAG Group’s guidance keeps the sector in focus.
BAWAG Group trades at a sizeable discount to both analyst targets and an implied intrinsic value, even after the pullback. Is that a sensible response to risk, or has caution now gone too far, as the valuation section shows?
Most Popular Narrative: 20.5% Undervalued
BAWAG Group’s most followed valuation narrative puts fair value at €195.37 compared with the last close of €155.40, framing the recent pullback against a higher implied earnings power anchored on its capital position and PTSB integration plan.
Planned use of excess CET1 capital, which currently sits well above the 12.5% target at 15.4% pro forma in Q1 2026 and 17.4% in Q2 2026, together with €14 to €15b of cash and an underinvested securities portfolio, gives BAWAG Group room to self-fund growth and potentially expand revenue and net income without relying on external capital.
Execution of the plan to deepen exposure in core euro-area retail markets such as Ireland through PTSB, where management sees attractive housing demand and retail deposit potential, could broaden BAWAG Group’s revenue base and support more stable earnings from a larger mix of mortgages and retail banking income.
See why 10 investors see BAWAG Group as 20% undervalued.
Result: Fair Value of €195.37 (UNDERVALUED)
Still, the BAWAG Group story could shift quickly if risk costs rise faster than guided as unsecured lending grows, or if the PTSB integration proves more expensive than planned.
Find out about the key risks to this BAWAG Group narrative.
Another View: What BAWAG Group’s P/E Is Really Saying
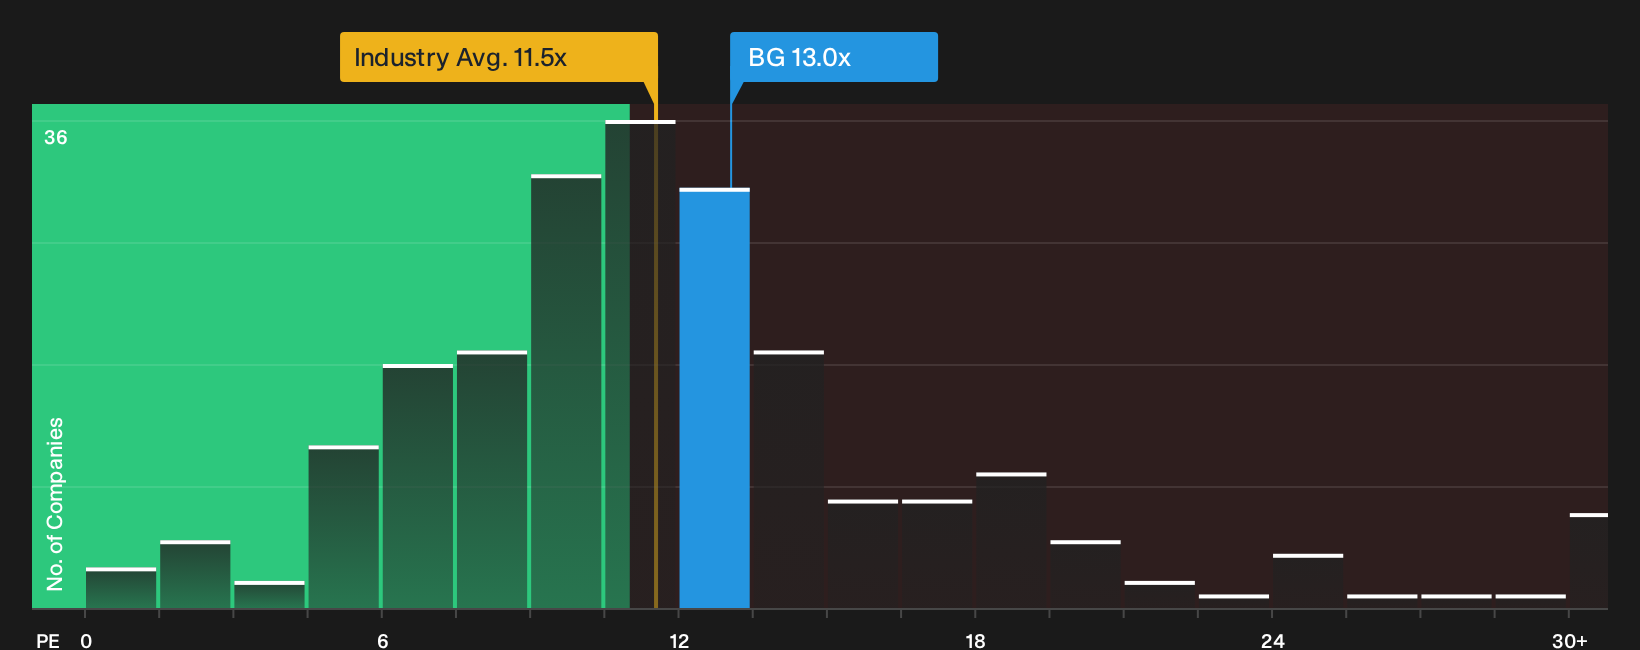
DCF and fair value models paint BAWAG Group as heavily undervalued at €155.40. The P/E ratio is more cautious. The shares trade on 13x earnings, above the European banks average of 11.5x and slightly above a fair ratio of 12.4x, which hints at some valuation risk if expectations cool.
Investors weighing these mixed valuation signals may want to see what the numbers say when lined up cleanly against peers, sector norms and that 12.4x fair ratio, then decide which yardstick feels more reliable for their process. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the BAWAG Group story so far, or a clear opportunity hiding in plain sight. Take a close look at the numbers, weigh the potential upsides against the open questions around risk, and then anchor your decision on the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond BAWAG Group?
If the BAWAG Group story has sharpened your focus, you could widen your opportunity set with other stocks that match clear, rules-based fundamentals and risk filters.
- Target reliable compounding potential by focusing on steady balance sheets and consistent metrics using our list of solid balance sheet and fundamentals (205 results).
- Look for value where quality and price appear aligned by running a focused search through our 194 high quality undervalued stocks.
- Prioritise cash returns today by concentrating on higher yielding candidates screened through our 226 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com