


EN
3 ASX Growth Stocks With High Insider Ownership Growing Earnings At 74%
In the midst of a challenging market environment marked by declining technology stocks, fluctuating commodity prices, and rising oil costs, Australian investors are navigating a complex landscape. As concerns about the sustainability of the AI boom and geopolitical tensions impact global markets, identifying growth companies with strong insider ownership can provide valuable insights into potential investment opportunities. In such conditions, stocks that demonstrate robust earnings growth coupled with significant insider ownership may offer a degree of confidence and stability for investors seeking to align their interests with those who have substantial stakes in the company's success.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 15.7% | 97.8% |
| Starpharma Holdings (ASX:SPL) | 17.3% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 14.7% | 28.3% |
| PDI Gold (ASX:PDI) | 11.1% | 62.3% |
| Innovaero Technologies (ASX:INN) | 37.9% | 66.2% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Barton Gold Holdings (ASX:BGD) | 20.8% | 86.7% |
| Austral Resources Australia (ASX:AR1) | 22.6% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
Let's review some notable picks from our screened stocks.
Cobram Estate Olives (ASX:CBO)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Cobram Estate Olives Limited produces and markets olive oil in Australia, the United States, and internationally with a market cap of A$1.24 billion.
Operations: The company's revenue segments include Olive Oil and Other Packaged Goods from USA Operations generating A$95.01 million and Australian Operations contributing A$180.09 million.
Insider Ownership: 13.1%
Earnings Growth Forecast: 56.2% p.a.
Cobram Estate Olives is experiencing substantial insider buying, indicating confidence in its growth potential. Despite a recent net loss of A$4.23 million, the company is expected to achieve profitability within three years with revenue forecasted to grow at 24.2% annually, outpacing the Australian market's 4.8%. Trading significantly below estimated fair value enhances its appeal as a growth investment, though low return on equity and interest coverage remain concerns. Recently added to the S&P Global BMI Index, it maintains strong insider ownership dynamics.
- Click here and access our complete growth analysis report to understand the dynamics of Cobram Estate Olives.
- Our comprehensive valuation report raises the possibility that Cobram Estate Olives is priced higher than what may be justified by its financials.
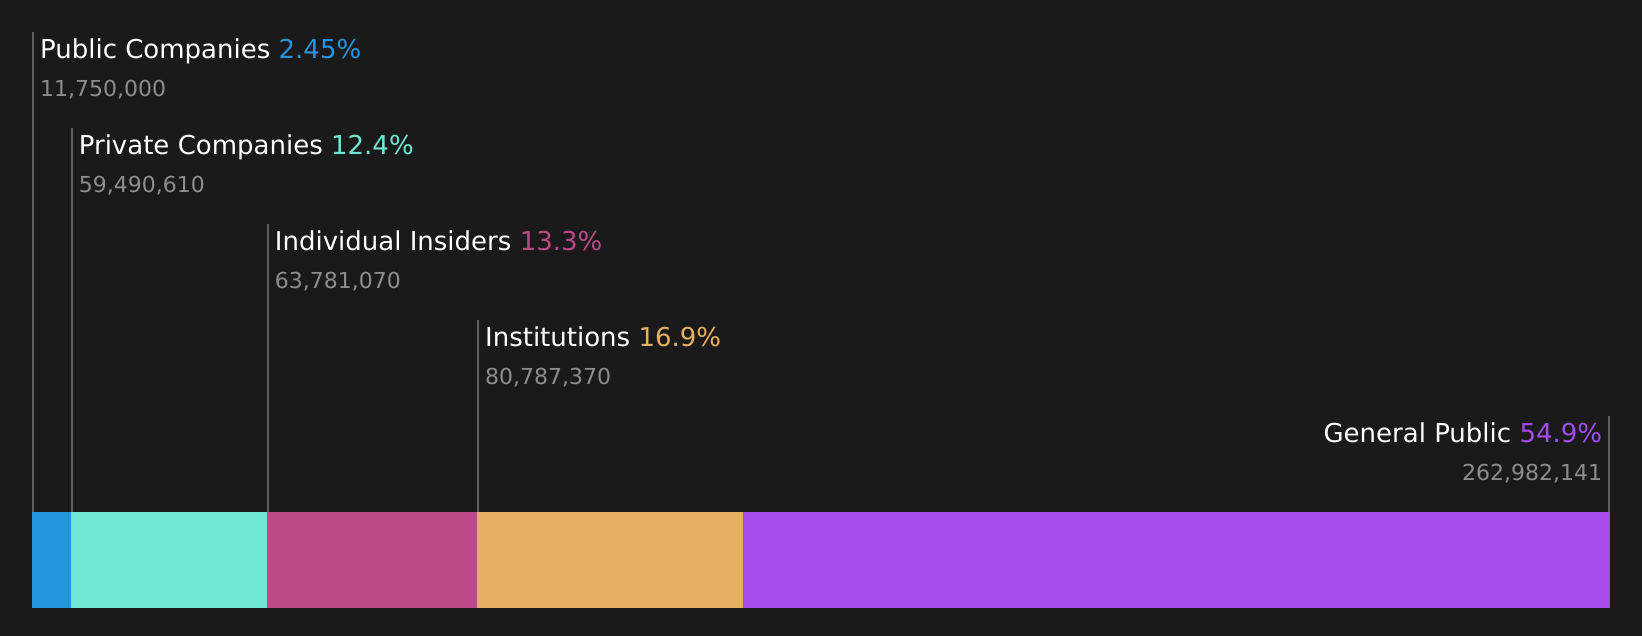
IperionX (ASX:IPX)
Simply Wall St Growth Rating: ★★★★★☆
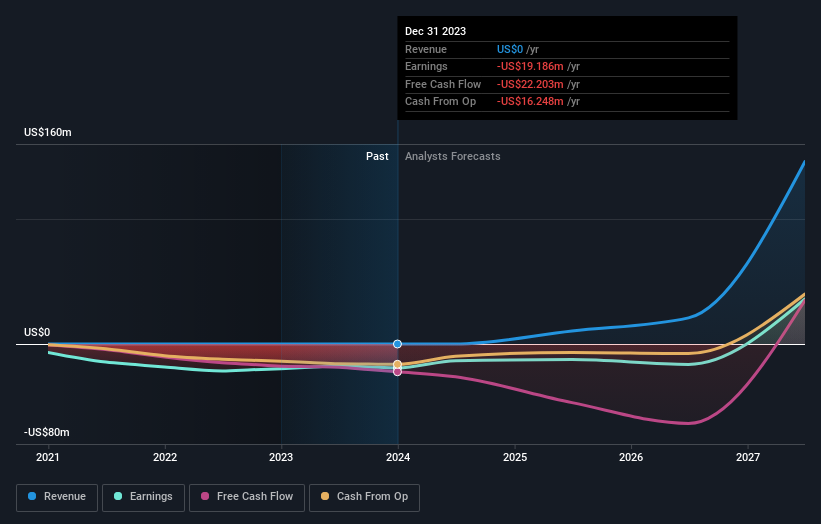
Overview: IperionX Limited focuses on developing mineral properties in the United States and has a market capitalization of A$642.98 million.
Operations: The company does not currently report any revenue segments.
Insider Ownership: 14.8%
Earnings Growth Forecast: 74.7% p.a.
IperionX is positioned for growth with its innovative GenX™ titanium production platform, which promises enhanced efficiency and cost reductions. Despite reporting a net loss of US$66.77 million for the year ended June 30, 2026, IperionX's revenue is forecast to grow significantly faster than the Australian market at 64% annually. The company benefits from substantial insider ownership and strategic contracts like the US$99 million IDIQ contract with the U.S. Army, supporting domestic titanium manufacturing expansion.
- Get an in-depth perspective on IperionX's performance by reading our analyst estimates report here.
- The analysis detailed in our IperionX valuation report hints at an inflated share price compared to its estimated value.
Temple & Webster Group (ASX:TPW)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Temple & Webster Group Ltd operates as an online retailer specializing in furniture, homewares, and home improvement products in Australia, with a market cap of A$632.85 million.
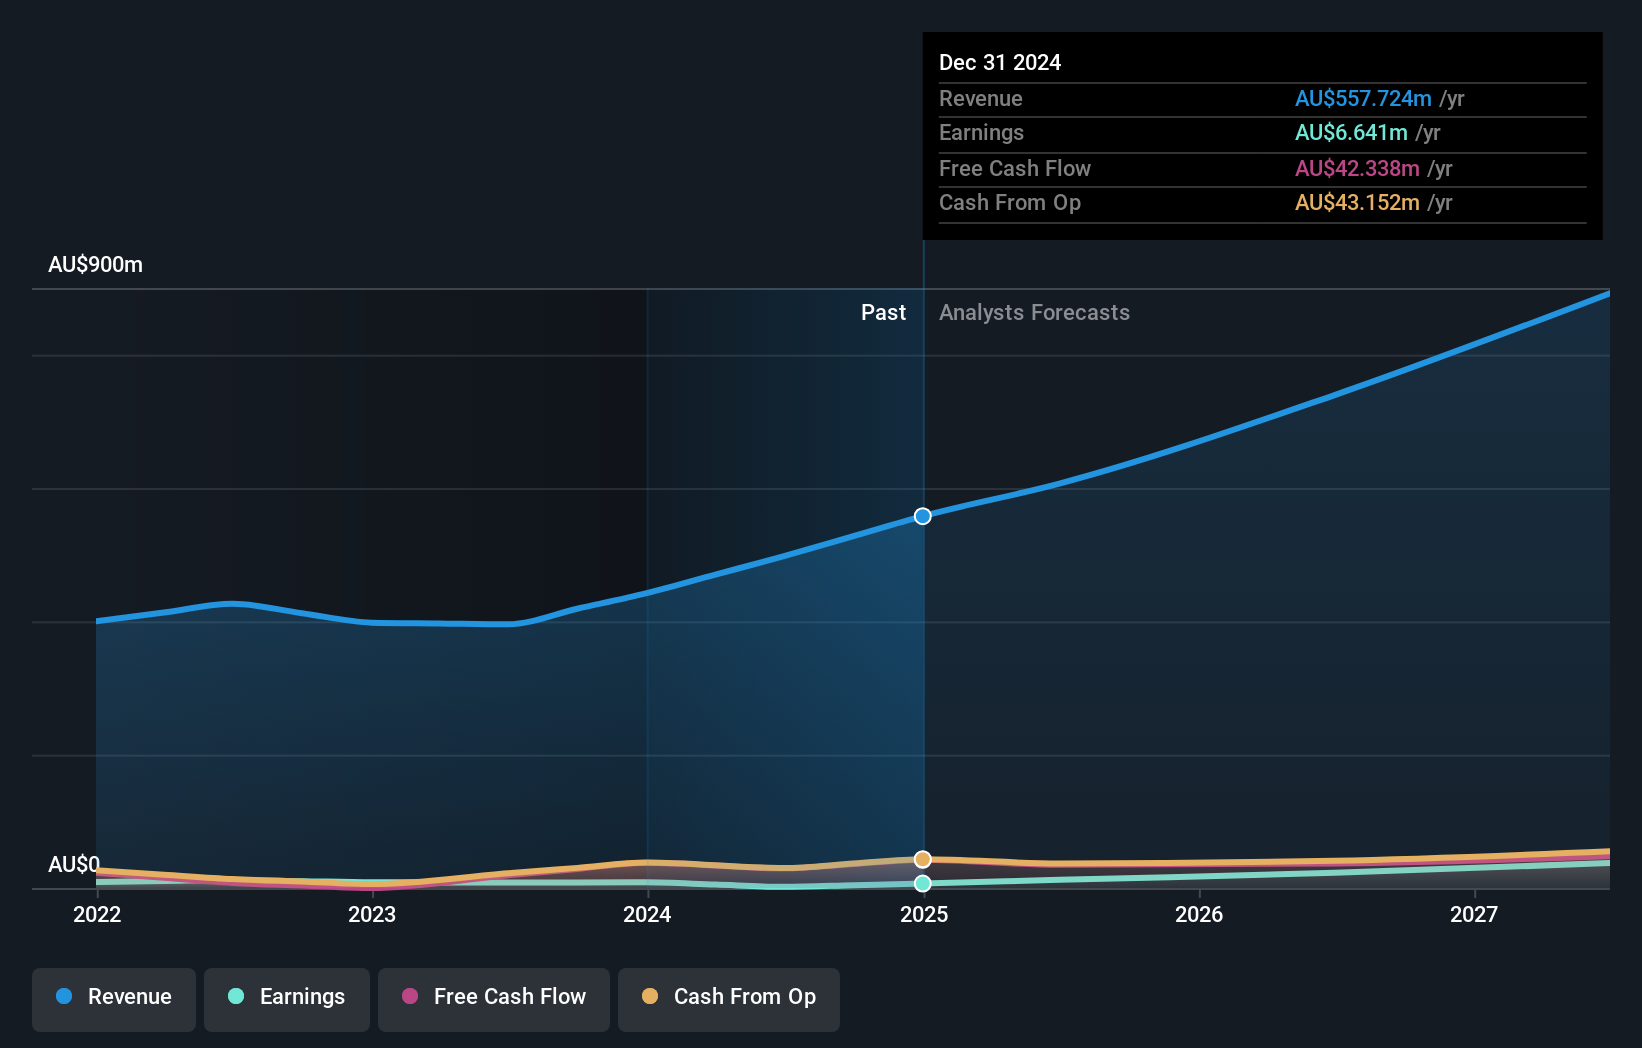
Operations: The company's revenue primarily comes from the sale of furniture, homewares, and home improvement products, totaling A$664.59 million.
Insider Ownership: 14.2%
Earnings Growth Forecast: 30.7% p.a.
Temple & Webster Group is poised for growth, with earnings expected to increase significantly at 30.7% annually, outpacing the Australian market's 11.1%. Despite a volatile share price and reduced profit margins (0.6% down from 1.9%), the stock trades at a discount of 25.1% below its estimated fair value. Insider confidence is evident with substantial insider buying over the past three months and no significant selling, underscoring potential long-term commitment to the company's prospects.
- Delve into the full analysis future growth report here for a deeper understanding of Temple & Webster Group.
- The valuation report we've compiled suggests that Temple & Webster Group's current price could be inflated.
Summing It All Up
- Explore the 120 names from our Fast Growing ASX Companies With High Insider Ownership screener here.
- Curious About Other Options? Outshine the giants: these 19 early-stage AI stocks could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com