


EN
Is Rail Leasing Expansion Altering The Investment Case For Ares Management (ARES)?
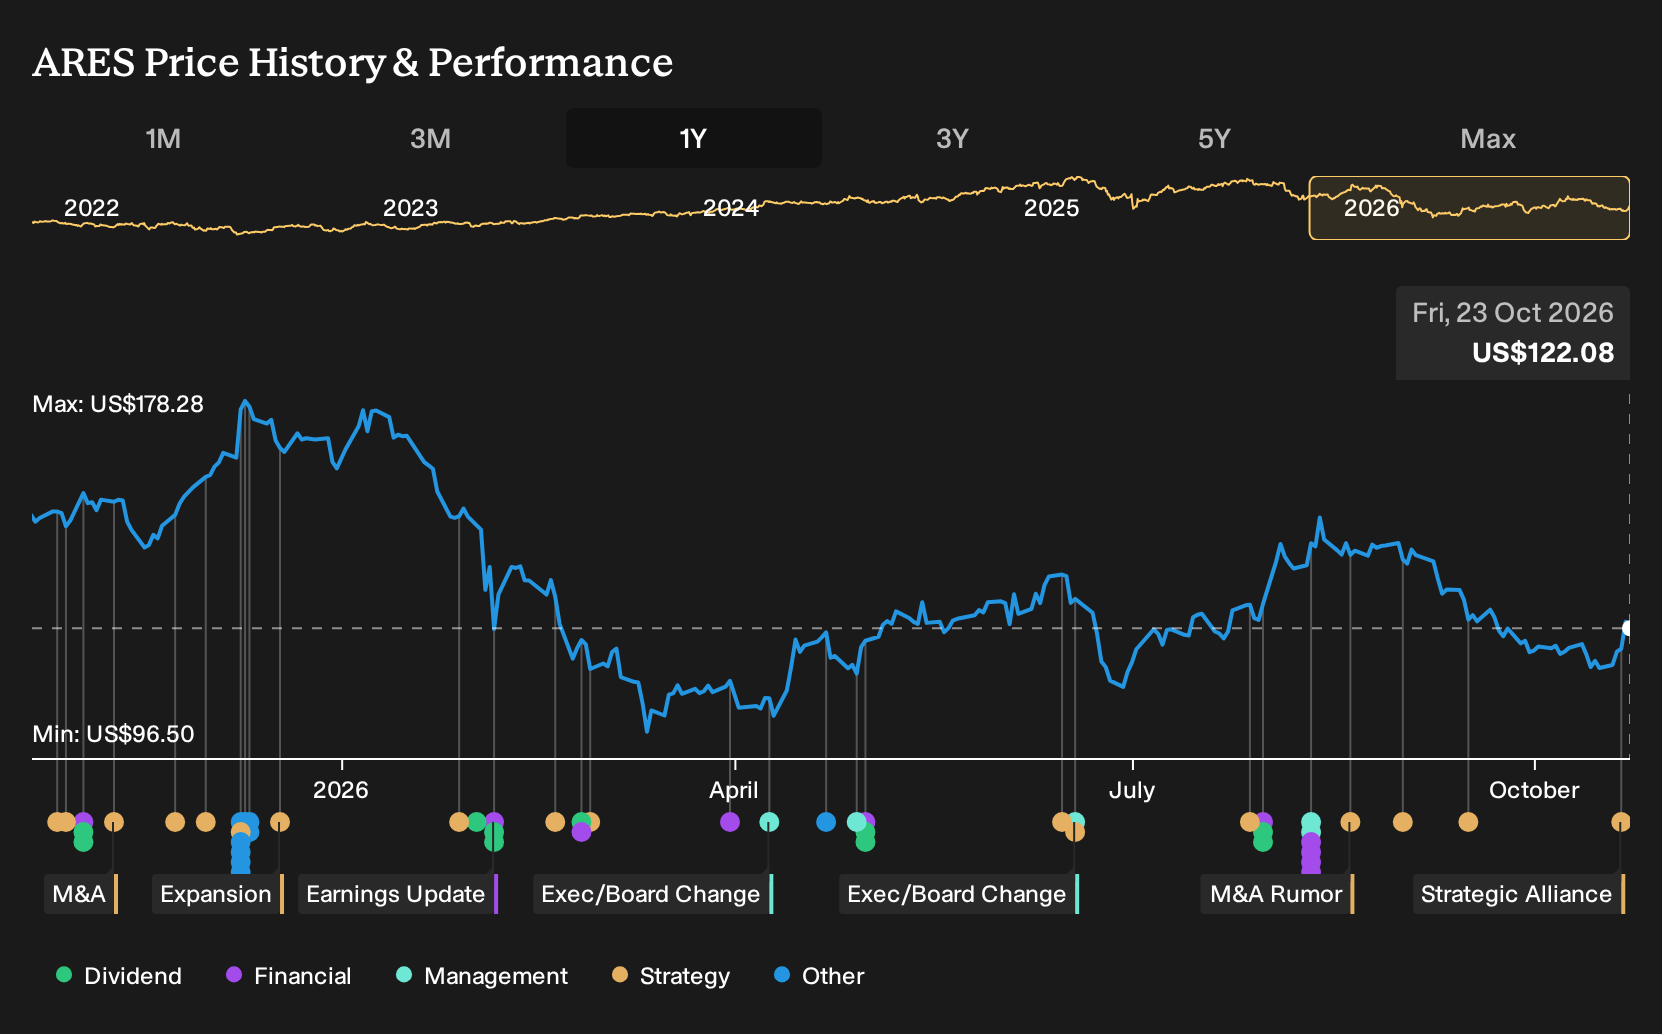
- Ares Management agreed to acquire Infinity Transportation for about US$2.9b and, through Ares Real Estate, formed a European logistics partnership with Norges Bank Investment Management backed by a €1.5b equity commitment.
- The combination of railcar leasing through Infinity and large scale European logistics investment with Norges Bank Investment Management strengthens Ares Management’s role across supply chain infrastructure used by transport, distribution and e commerce tenants.
- We will now examine how Ares Management’s Infinity Transportation acquisition may influence the existing investment narrative around its fee engine.
Ares Management Investment Narrative Recap
Owning Ares Management means buying into an asset manager that leans heavily on fee based income from private credit and real assets, plus a growing logistics footprint. For that to work for you, the fee engine needs to keep scaling while wealth channel redemption pressures and high funding costs stay contained. The newest logistics moves look additive rather than transformational to that near term story.
Right now the key swing factor is whether Ares Management converts its sizeable dry powder and newer platforms into fee related earnings that justify a P/E well above peer averages. The biggest operational risk remains that capital intensive real asset initiatives and rail leasing build outs fail to generate the fee margins needed to support both growth investments and a dividend that is not well covered by current cash flows.
The new European logistics partnership with Norges Bank Investment Management looks most relevant here because it plugs directly into Ares Management’s real assets and infrastructure push. A €1.5b equity commitment gives the real estate arm fresh capacity to pursue modern, high quality warehouses that match existing supply chain themes without changing the overall firm profile overnight.
For you as a shareholder, this raises the execution bar on real assets as a catalyst. The platform now spans Marq Logistics, existing Japan and U.S. logistics ventures, and the new European pool. Any slowdown in deployment, weaker fee economics or operational missteps could weigh on margins at a time when the stock already screens expensive on several P/E comparisons and debt is not well covered by operating cash flow.
What The Current Ares Management Forecasts Assume
Analyst models around Ares Management are already baking in a fairly punchy set of expectations before accounting for Infinity Transportation and the expanded European logistics push. The consensus view talks about a fee machine that can handle more capital intensive platforms and still reach higher profitability over time.
On the top line, the workhorse input is revenue growing at 10.2% a year over the next three years. That pace underpins the idea that Ares Management can keep scaling across private credit, real assets and newer infrastructure strategies without needing a step change in fundraising conditions.
Profitability assumptions stretch further. Forecasts point to margins moving from 9.3% today to 28.5% over roughly three years, which implies a very large uplift in earnings efficiency from platforms that include logistics, rail leasing and data centers. For you, that kind of margin reset is where execution on things like the Infinity integration and the Norges Bank Investment Management partnership really matters.
Earnings expectations are more concrete in the numbers. Analysts see net income reaching US$2.0b by 2029, compared with US$487.4m today. That is roughly a 4x step up in the profit pool that needs to be supported by higher fee related earnings, successful deployment of real asset capital and disciplined cost control as Ares Management broadens its footprint.
Valuation work in the consensus set ties all of this to a lower P/E over time. On those same US$2.0b 2029 earnings and US$7.0b of revenue, the stock would need to trade on about 23.3x earnings versus 52.7x today and below the 38.1x multiple quoted for the broader US capital markets group. That gap leaves less room for disappointment if logistics returns, railcar utilization or fundraising flows fall short of the script embedded in these models.
Ares Management's narrative projects US$7.0b revenue and US$2.0b earnings by 2029. This assumes revenue growth at 10.2% a year and roughly a 4x earnings increase from US$487.4m today.
Uncover why Ares Management's fair value indicates a 19% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view puts cost pressure, not logistics growth, at the center of the Ares Management story. The most cautious analysts were only looking for about US$7.0b of revenue and US$1.9b of earnings by 2029 before this news. That is a tighter, more expense focused narrative. Use it as a reference point as you weigh how the Norges partnership and Infinity deal might eventually reshape expectations.
Explore 2 other Ares Management fair value estimates, including one that suggests up to 15% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ares Management research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ares Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ares Management's overall financial health at a glance.
Looking for more Ares Management style ideas?
If the Ares Management story has sharpened your appetite for infrastructure and income opportunities, use the Simply Wall St Screener to surface other stocks that match the kind of risk and quality profile you want, rather than just following headlines.
- For investors who want income that aims to be both sizeable and supported, start with a shortlist of 5 dividend fortresses that focus on higher yields with stronger financial backing.
- If capital protection is your first line of defense, filter for resilience using a 30 resilient stocks with low risk scores that screens for companies with steadier risk profiles.
- When you are hunting for under-the-radar opportunities with solid fundamentals, cast a wider net through a 21 high quality undiscovered gems that highlights quality businesses the market may not be paying much attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com