


EN
Missed Out On Magazine Luiza's Run? Here Is What Holders Saw
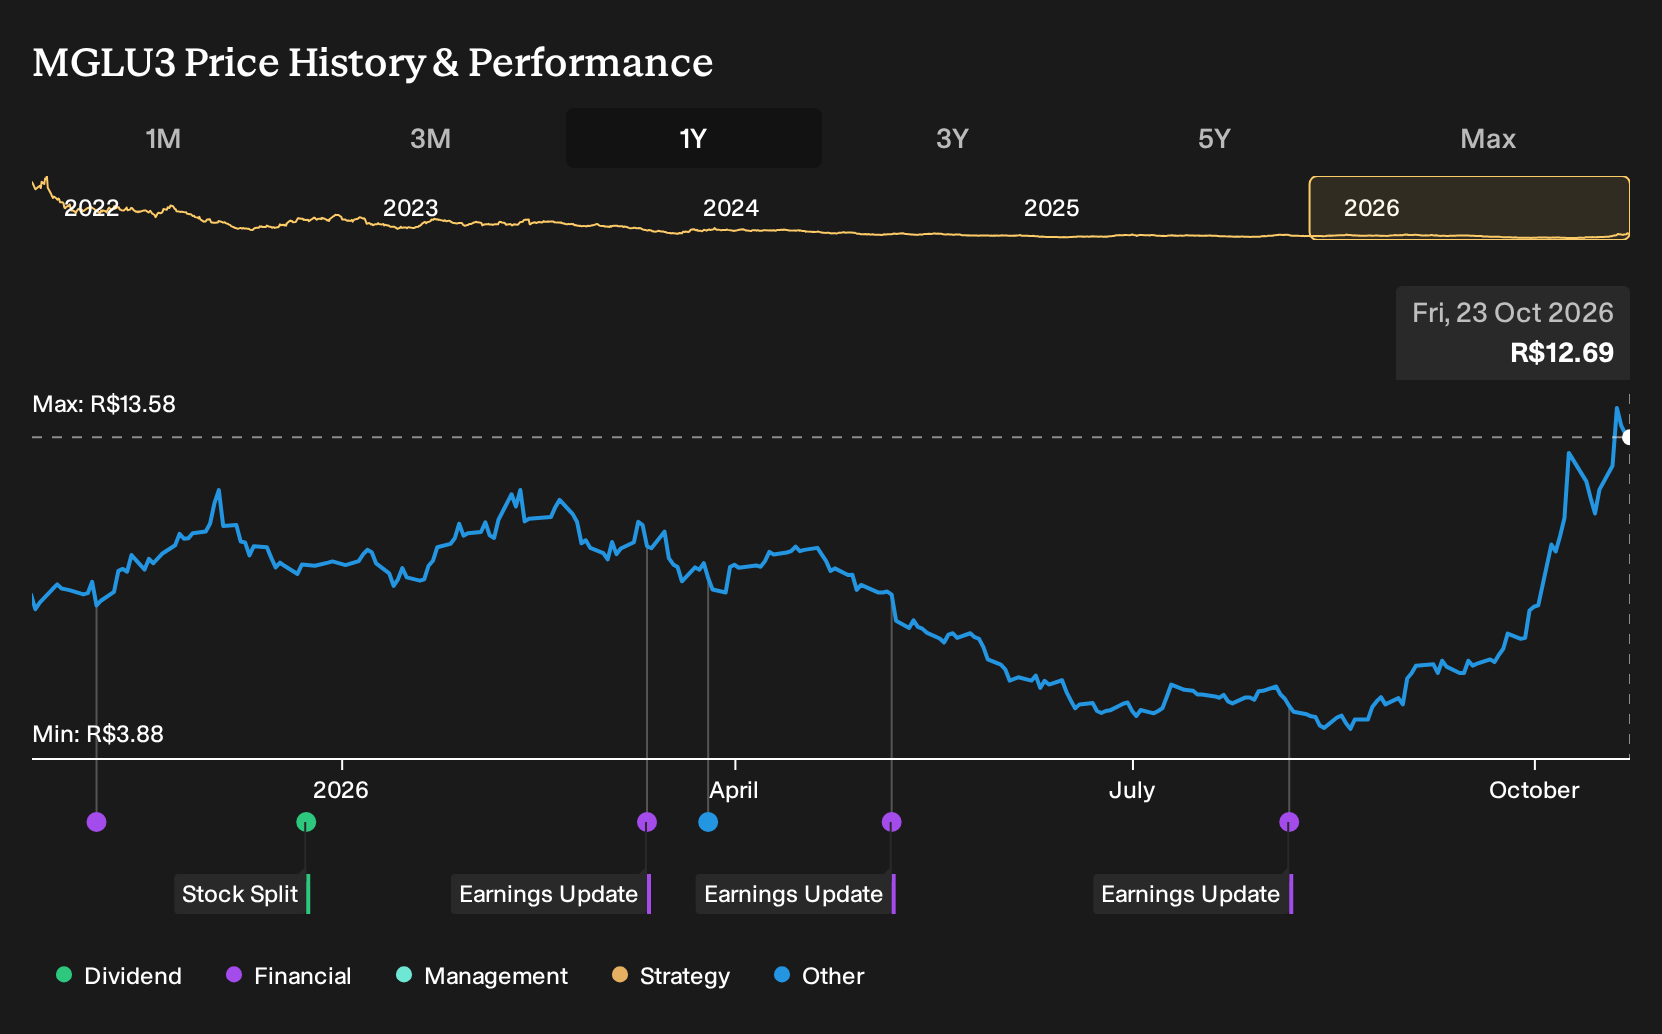
Investors who held Magazine Luiza over the past year are up 66.5%, including dividends. If you had bought on 23 October 2025, knowing only that bullish analysts saw digital finance and omnichannel retail as a growth engine while bearish voices warned Amazon and Alibaba could squeeze margins, how would you have weighed that split against a retailer still posting quarterly losses and a falling net margin, and which side of the argument would have felt more convincing at the time?
Magazine Luiza has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
What Magazine Luiza Investors Were Really Arguing About
The shares cost R$7.87 at the start of the period, and anyone looking at Magazine Luiza then was effectively choosing between two very different stories about its future.
On the optimistic side, the bull Narrative pointed to a Fair Value of R$15, a price those assumptions implied, built on digital finance and omnichannel retail. That view leaned on revenue growing 6.8% a year and profit margins reaching 3.1% within roughly three years.
The bear Narrative anchored to a Fair Value of R$6.2 and focused on pressure from Amazon and Alibaba. This camp highlighted rising digital marketing spend as a key risk that could erode margins even if revenue still increased by 3.7% a year.
What The Results Changed In The Magazine Luiza Debate
The Q2 2026 figures gave Magazine Luiza investors fresh ground to test both stories. Revenue slipped from R$9,134.666m in Q2 2025 to R$8,898.727m, and the business still reported a loss, with net income excluding extra items falling from R$24.356m lost to R$72.462m lost. With net margin weakening from -0.3% to -0.8%, the profitability leg of the bullish case remained unproven and the evidence cut both ways.
The key assumption here was margin repair. For any other retailer with a similar debate, focus on whether net margin is actually moving toward the target level in results, rather than only on top-line direction or on what analysts expect a few years out.
What Magazine Luiza's Price Already Bakes In
Magazine Luiza now trades at R$12.69. The selected Narrative sees Fair Value below that level and links the gap to how much faith you place in margin repair and scalable omnichannel execution.
Buying at today’s quote means assuming those higher margins arrive and hold. The question is how that sits against the risks it highlights around interest rates, competition and credit quality.
"Elevated interest rates and rising competition threaten Magazine Luiza's growth, profitability, and credit quality, while operational scaling and expense control pose ongoing risks."
The price and this Narrative do not agree. → Uncover what this Narrative says Magazine Luiza is actually worth
Beyond Magazine Luiza’s Storefront
Magazine Luiza pulls you into retail and credit. Just beyond that familiar interface, another layer of infrastructure quietly does the work.
Every online purchase, credit check, or delivery update relies on intensive computing. Those systems run on processors built from blueprints licensed by a specialist designer.
Instead of fabricating hardware, this business packages designs and development tools. Customers then produce chips that keep phones, data centers, and connected devices running.
As AI workloads spread through commerce and logistics, efficient processing grows more important. A company shaping that architecture could shift from quiet utility to pivotal building block.
One Narrative has put that dependency into a written case. → See the robotics company one Narrative values 104% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com