


EN
New CEO Appointment Could Be A Big Moment For CSL (ASX:CSL)
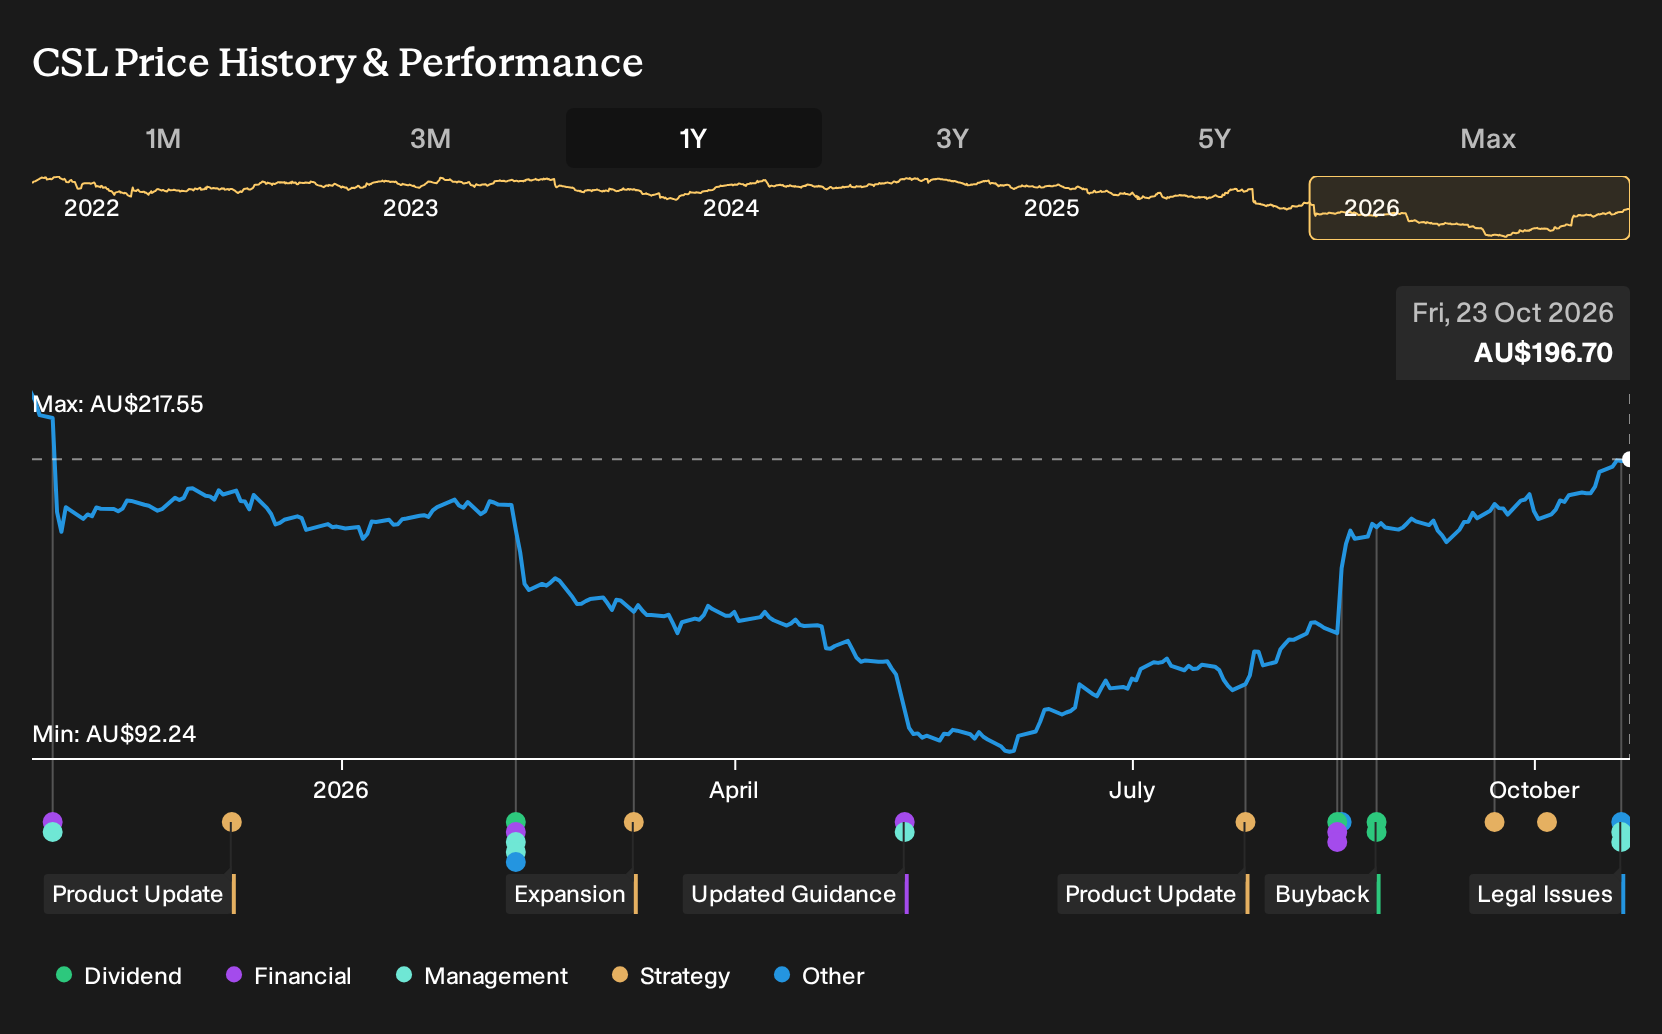
- CSL has confirmed that a shareholder class action was filed in the Supreme Court of Victoria for investors who bought certain securities between 11 February 2025 and 11 May 2026, and also announced that experienced pharma executive Deborah Waterhouse will become CEO and Managing Director from 1 February 2027.
- The legal claim challenges CSL’s past disclosures and guidance on expected FY26 performance at the same time that the board is bringing in an external leader with deep global specialty pharma experience. This combination puts governance, communication quality and execution on future turnaround efforts firmly in focus for investors.
- Attention now turns to how CSL’s broader investment narrative could be reshaped by Deborah Waterhouse’s appointment and the parallel class action.
What Is CSL's Investment Narrative?
To stay invested in CSL, you really need to believe the core engine still rests on global demand for plasma therapies, vaccines and iron and kidney treatments, backed by A$15,797.0m in revenue and a broad geographic footprint. The near term story is about execution. Management has to integrate CSL Vifor more cleanly, improve returns from a capital intensive portfolio and work back from a net loss of A$2,579.0m toward the profitability that forecasts point to over the next few years.
In the short term, the class action raises a question about past FY26 communication rather than day to day operations. The appointment of Deborah Waterhouse points directly at future delivery on that guidance culture. The legal claim could still absorb time and management focus, and it lands on top of already high debt and slower 3% forecast revenue growth, which keeps funding flexibility and balance sheet risk front of mind.
That said, the more interesting tension in the CSL story sits where legal scrutiny, higher leverage and a still unproven turnaround in Vifor all meet.
There's only one way to know the right time to buy, sell or hold CSL. Head to Simply Wall St's company report for the latest analysis of CSL's Fair Value.
Exploring Other Perspectives
One alternate angle on CSL focuses on the cost saving program as a potential upside catalyst. The most optimistic analysts were modelling revenue of about $16.7b and earnings of roughly $3.9b by 2029, compared with $3.5b for the bearish group. Those views came before this class action and leadership change, so you may see forecasts shift from here.
Explore 7 other CSL fair value estimates, including one that suggests as much as 29% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your CSL research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CSL. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CSL's overall financial health at a glance.
Looking For More Ideas Beyond CSL?
CSL's situation may have put governance and balance sheet strength on your radar. If you want to widen your watchlist, the Simply Wall St Screener can surface other businesses that better fit the mix of risk, quality and income you are aiming for.
- If you are hunting for resilient financial positions with less balance sheet stress, start with this list of solid balance sheet and fundamentals (12 results) that could handle tougher conditions without as many surprises.
- For investors who want potential mispricing opportunities backed by fundamentals, scan this curated set of 15 high quality undiscovered gems that the market might not be paying full attention to yet.
- If your priority is price discipline and quality together, filter for value focused opportunities through a list of 2 high quality undervalued stocks that combine strong cash generation with more modest expectations baked into the share price.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com