


EN
What MKS Holders Got Right
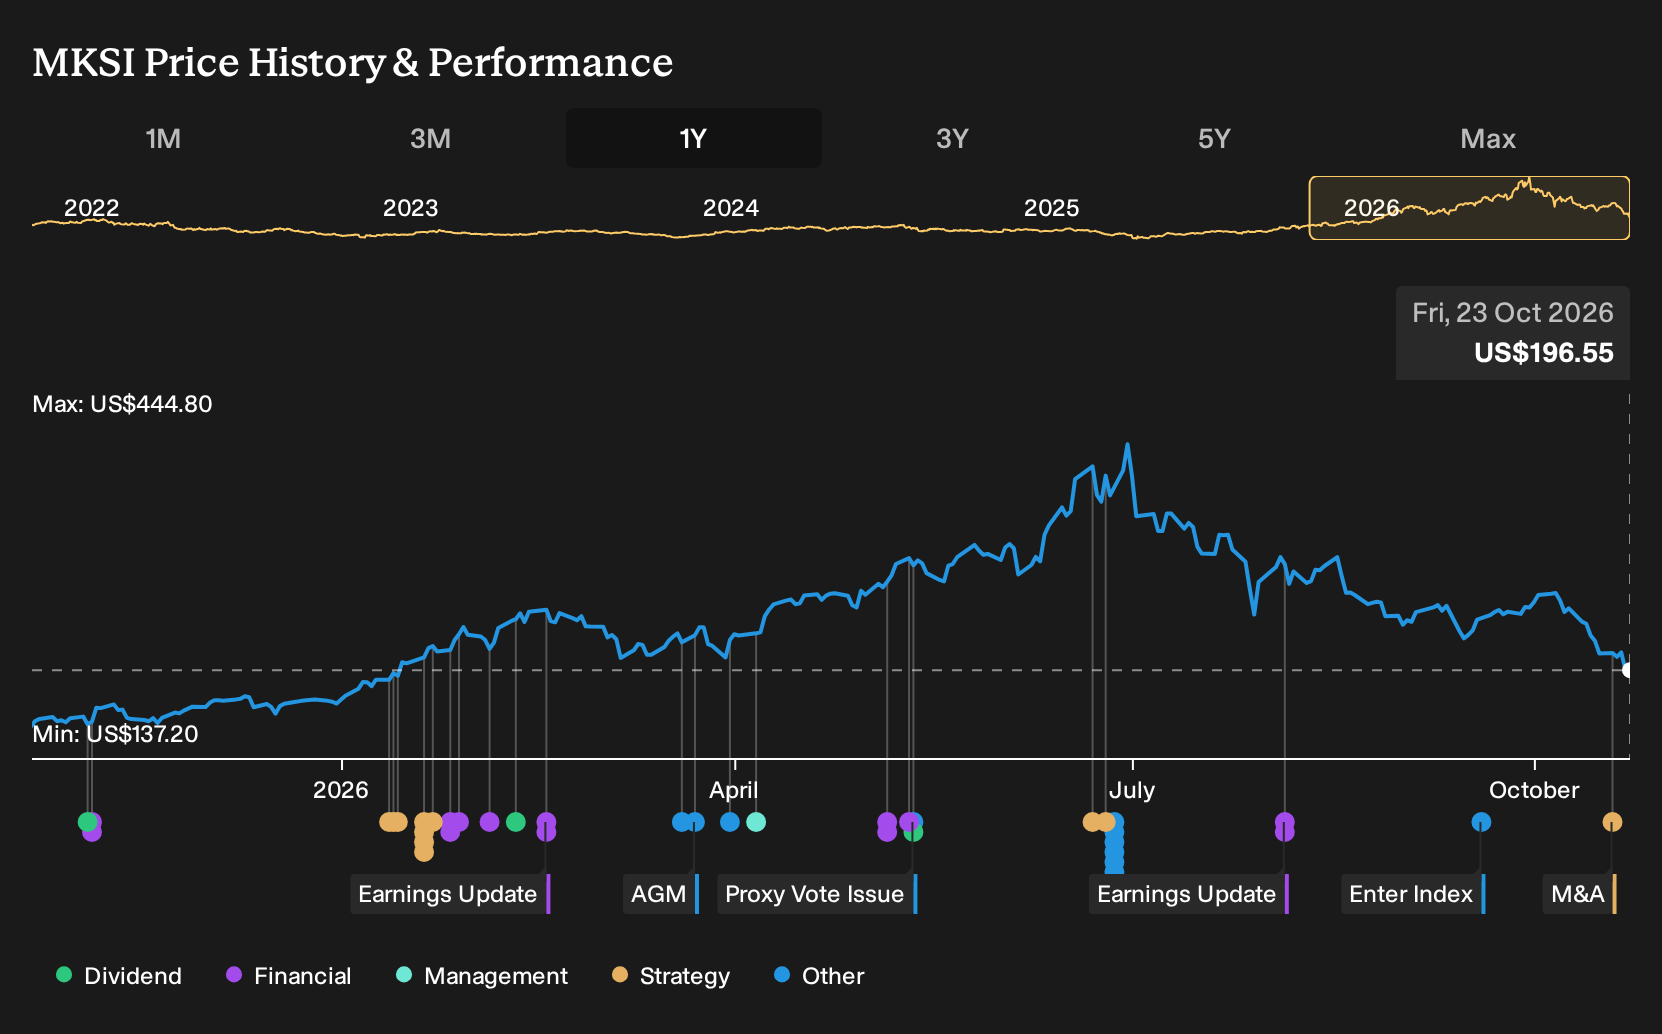
If you had bought MKS on 23 October 2025 and simply sat tight through the AI-fueled semiconductor headlines and warnings about overvaluation, the outcome looks very different today. Investors who held MKS over the past year are up 38.1%, including dividends. Early buyers had to weigh booming chemistry and packaging demand against high debt, customer concentration, and frothy sentiment. Which of those trade offs should matter most now?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The move put MKS in the middle of this trade. Scan 55 AI infrastructure stocks for other companies exposed to it.
The Argument MKS Investors Were Really Having
The shares cost US$141 at the start of the period, so anyone looking at MKS had to decide which story about the business felt more realistic.
The bullish narrative put Fair Value at US$160 and leaned on strong, recurring chemistry revenue tied to AI, advanced packaging, and digital transformation, along with high switching costs from integrated chemistry, equipment, and service bundles.
The sceptical case pointed to a Fair Value of US$122 and focused on risks such as heavy leverage around 4x EBITDA, trade disruption, and customer concentration that could pressure earnings stability.
What The Evidence Did To The MKS Argument
MKS Inc. reported Q2 2026 revenue of US$1.25b and net income of US$175m, with net margin at 14.0% versus 6.4% in Q2 2025. That shift toward higher profitability and chemistry driven demand leaned toward the bullish story about recurring, AI linked orders and better mix. Rising insider selling and overvaluation flags meant the results still cut both ways.
The real assumption on trial here was margin resilience. For any similar supplier, you would track net margin and segment mix against earlier claims about stickier, recurring chemistry or service revenue, rather than just watching headline growth.
What MKS' Current Price Already Assumes
With MKS now at US$197 after a 38.1% gain over the past year, the selected Narrative still sees Fair Value above that level, based on its own assumptions.
That view leans on AI linked semiconductor and packaging demand, recurring chemistry and service revenue, and ongoing deleveraging. It argues buyers are not fully crediting successful ramp up of new Asian manufacturing capacity while keeping margins near guided levels.
"The deepening integration of advanced materials and chemistry equipment within MKS, supported by record chemistry equipment orders for several quarters and a rising share of AI related chemistry revenue, increases the opportunity for tools plus consumables cross selling and can support both revenue growth and higher gross margins."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where MKS Demand Rhymes Elsewhere
MKS has tied its story to chemistry and AI heavy manufacturing demand. You could stop there, or look sideways.
Every AI server, sensor, and gadget that MKS touches still needs somewhere to store and recall data quickly.
Another supplier focuses on that layer, providing memory and storage products that keep AI hardware useful between training runs and everyday inference work.
Its customers wrestle with similar questions to MKS buyers, from capital intensity to contract structures that try to smooth a historically choppy business.
If AI keeps leaning on both chemistry inputs and memory capacity, the parallel between those two business models becomes harder to ignore.
That argument has a Narrative and a number behind it. → See the company one Narrative values 42% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com