


EN
Graham Holdings (GHC) Could Be 56% Below Fair Value On Its Recent Pullback
Graham Holdings: Recent Moves And Current Profile
Graham Holdings (GHC) has drawn fresh attention after recent share price moves, with the stock last closing at US$1,213.48. Investors are weighing that valuation against the group’s diversified education, media, healthcare, manufacturing, and automotive operations.
The recent pullback of 2.1% on the day sits against a firmer backdrop, with Graham Holdings posting an 11.6% year to date share price return and a 19.5% total shareholder return over the past year, and multi year total shareholder returns above 100% indicating sustained investor confidence rather than a short lived burst of momentum.
Compare Graham Holdings’ multi segment profile with a curated shortlist of diversified businesses using the 21 high quality undiscovered gems to see what else is moving under the radar.
After that kind of multi year run and a fresh pullback from the recent high, does Graham Holdings look like a fair buy today, or is this a case where patience on a better entry makes more sense once you see the valuation work?
Preferred Price-to-Earnings of 9.5x: Is it justified?
On the valuation side, Graham Holdings trades on a P/E of 9.5x, while the last close sits at $1,213.48. Relative to peers, that multiple aligns with a stock that the market currently prices more cautiously than many consumer services comparables.
The P/E ratio compares what investors are paying today for each dollar of earnings. For a diversified group like Graham Holdings, that single figure pulls together very different activities, from Kaplan education to television broadcasting, healthcare services, manufacturing, and automotive retail.
GHC is described as good value on this basis, with its 9.5x P/E below both the peer average of 18x and the broader US Consumer Services industry average of 13.3x. At the same time, earnings quality flags matter, because recent net profit includes a large one off gain of $166.4m and net profit margins of 10.7% compare to 14% the previous year, so some investors may treat the headline earnings with caution.
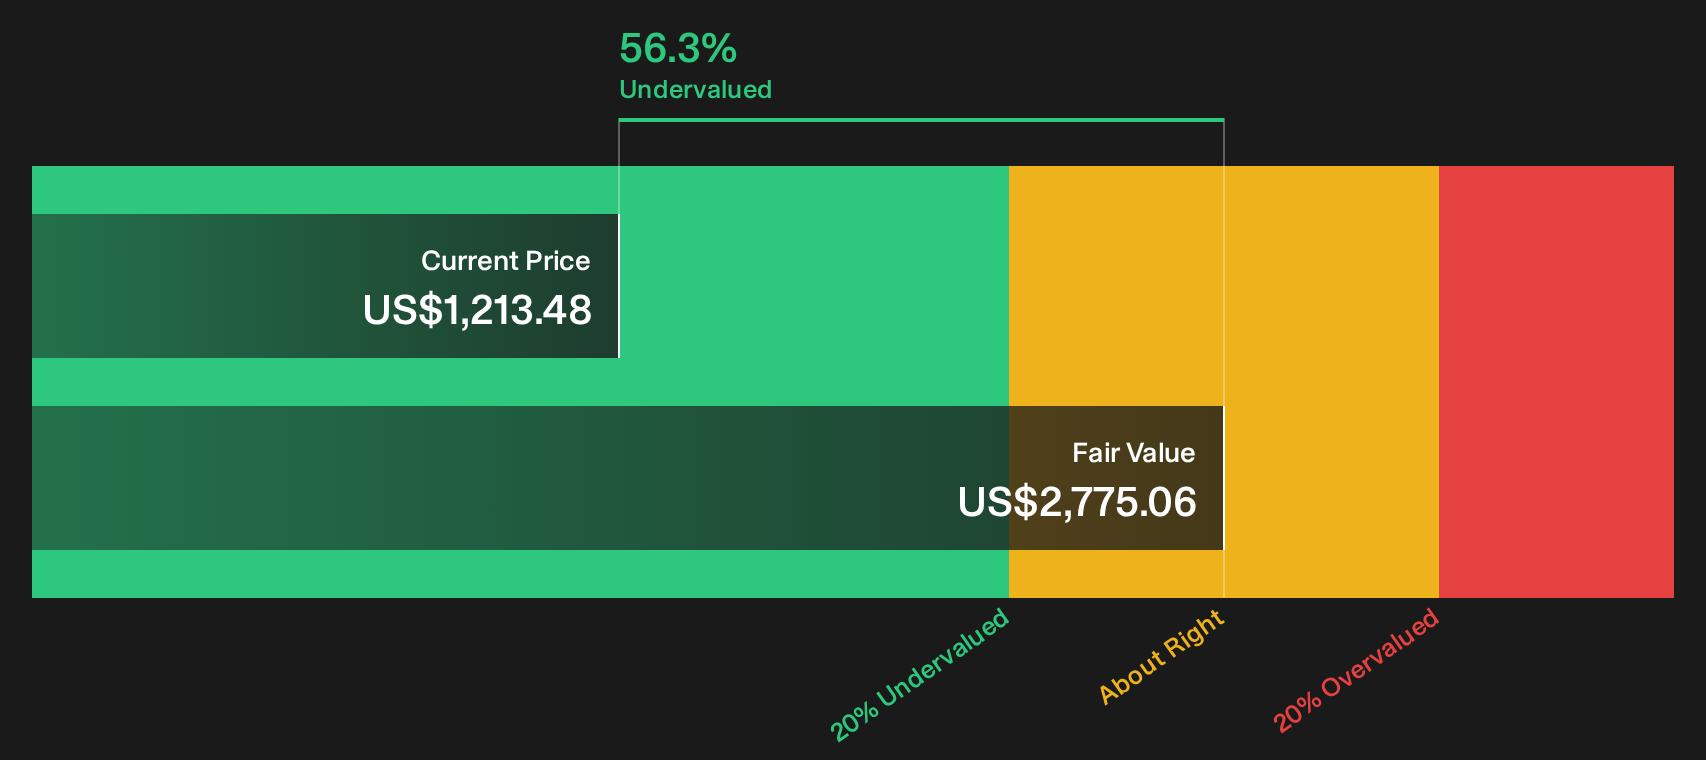
Given that backdrop, the SWS DCF model indicates the stock is trading at a steep discount. Graham Holdings is reported as trading at 56.3% below the modelled future cash flow value, with an estimated fair value of $2,775.06 against the current $1,213.48 price. That framework projects future cash flows from the various segments, then discounts them back to today using a required rate of return to arrive at a single value for the equity.
For a holding company with established operations, mixed segment growth profiles, and uneven earnings from one off items, a discounted cash flow lens can be useful because it focuses on longer term cash generation rather than any single year of reported profit. Revenue of $5.07b and earnings that have grown by 13.9% per year over the past 5 years provide some history for the model, even as the most recent year included a 20.3% decline in earnings and a large non recurring gain.
Look into how the SWS DCF model arrives at its fair value.
Result: Price-to-Earnings of 9.5x (UNDERVALUED).
Still, the Graham Holdings story can be knocked off course if one-off gains fade from earnings or if any large segment, such as automotive or education, hits a bump.
Find out about the key risks to this Graham Holdings narrative.
Another View On Graham Holdings’ Value
Price based metrics tell one story for Graham Holdings, but the SWS DCF model tells another. That framework points to an estimated fair value of $2,775.06 per share versus the current $1,213.48, which suggests the gap between market price and modelled cash flows is wide enough for investors to question what the market might be missing.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Graham Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in Graham Holdings’ valuation story make this a good moment to check the underlying numbers and decide where you stand. To weigh both the concern and the optimism, start with the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Graham Holdings?
If Graham Holdings has sharpened your focus, do not stop here. Give yourself options by lining up a few more ideas before you commit fresh capital.
- Scan for resilient payers that prioritise income and staying power through the 5 dividend fortresses.
- Zero in on quality at a discount by running the 29 high quality undervalued stocks before the crowd catches on.
- Protect your downside first and hunt for steadier performers using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com