


EN
Scotts Miracle Gro (SMG) Could Be 26% Undervalued Following UBS Upgrade
UBS recently upgraded Scotts Miracle-Gro (SMG), highlighting expectations for steadier revenue and productivity that could support stronger cash generation. That shift in sentiment comes after a period of sharp share price swings.
Recent trading reflects that changing mood. Scotts Miracle-Gro’s 7-day share price return of 8.65% and 30-day share price gain of 16.51% follow a 90-day share price decline of 15.13%, while the 1-year total shareholder return of 11.67% contrasts with a 5-year total shareholder return that is down 51.42%. This pattern suggests momentum has picked up in the short term despite a weak long-term record.
Scan how other potential turnaround stories compare by jumping into our curated list of 29 high quality undervalued stocks that, like Scotts Miracle-Gro, are being weighed against their underlying cash generation.
Scotts Miracle-Gro now trades at a clear discount to both analyst targets and intrinsic value estimates after a sharp rebound. Is that a genuine margin of safety, or a warning that the market’s caution still has a point?
Most Popular Narrative: 25.9% Undervalued
Against the last close of $59.29, the most followed fair value narrative for Scotts Miracle-Gro sits at $80.00. This frames the recent upgrade as part of a bigger debate about how far a margin and cash flow plan can carry the equity story.
Ongoing cost savings and automation in the supply chain, with over US$100 million in cost reductions already captured toward a US$180 million target, and continued investment in robotics, AI and SKU rationalization, which management directly ties to gross margin gains, improved EBITDA and stronger free cash flow.
See why 0 investors see Scotts Miracle-Gro as 26% undervalued.
Result: Fair Value of $80.00 (UNDERVALUED)
Still, this bullish Scotts Miracle-Gro narrative leans heavily on execution, from selling Hawthorne on acceptable terms to turning higher advertising and tech spend into real, profitable demand.
Find out about the key risks to this Scotts Miracle-Gro narrative.
Another View: What Multiples Say About Scotts Miracle-Gro
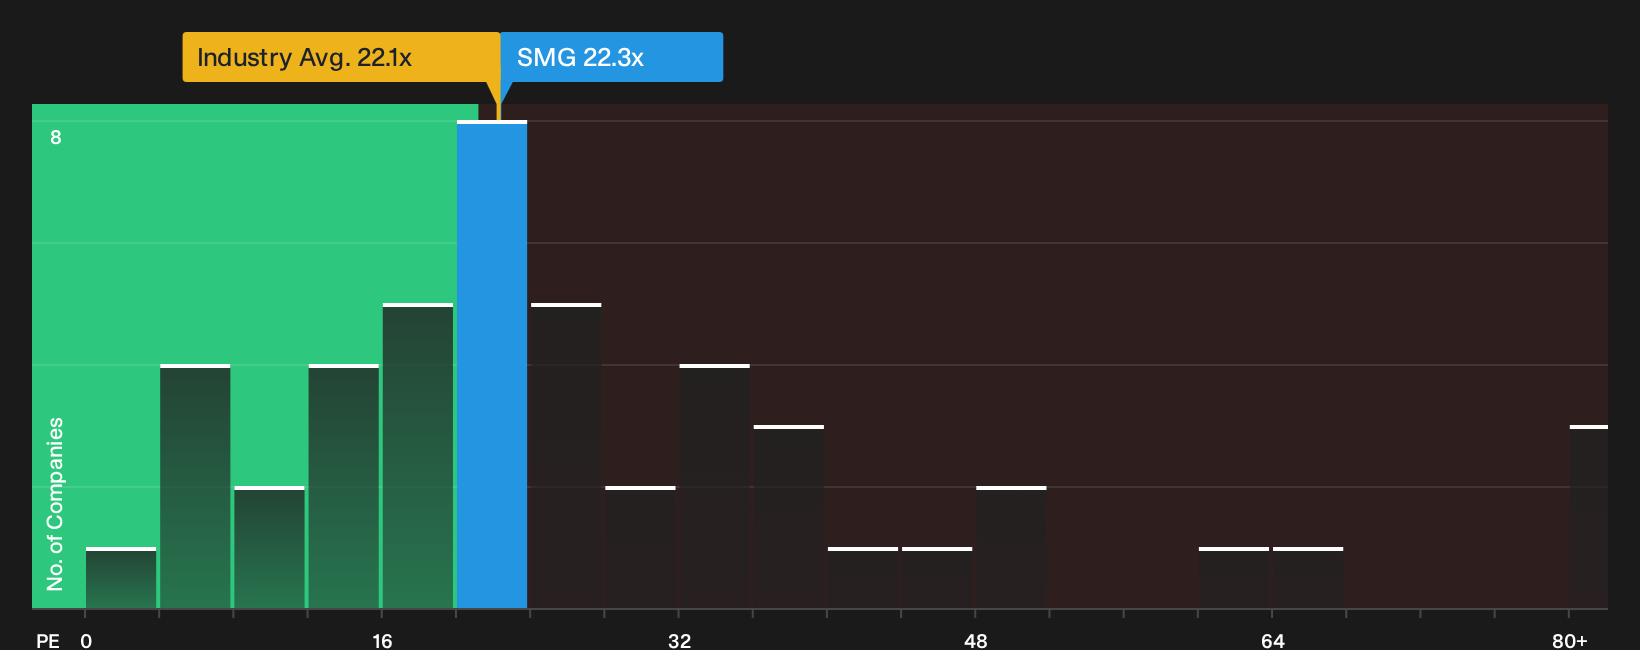
There is a catch. While the narrative fair value for Scotts Miracle-Gro flags the stock as undervalued, the current P/E of 22.3x is slightly higher than the US Chemicals industry on 22.1x and above a fair ratio of 18.2x, which points to some valuation risk if sentiment cools.
For investors comparing price tags as much as storylines, that premium versus the fair ratio suggests less room for error if earnings or margins fall short, even if the discounted cash flow story looks supportive on paper.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across cash flow, valuation and execution can create plenty of noise. Act quickly on your own homework and weigh up the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Scotts Miracle-Gro?
If you stop with Scotts Miracle-Gro, you risk missing other opportunities that match your goals just as well or even better.
- Zero in on potential mispricings by scanning a curated set of 29 high quality undervalued stocks that pair strong fundamentals with attractive entry points.
- Lock in income-focused opportunities by reviewing a hand picked group of 5 dividend fortresses that target reliable payouts backed by underlying cash flows.
- Reduce downside surprises by filtering for companies in the 30 resilient stocks with low risk scores that score well on balance sheet strength and risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com